
Penumbra’s Thrombectomy Platform at an Inflection Point: Innovation Momentum, Margin Pressures, and the Boston Scientific Acquisition
Penumbra’s leadership in mechanical thrombectomy is underscored by a robust product portfolio, steady operational gains, and a pending $14.5 billion acquisition by Boston Scientific. Yet, margin compression and integration risks highlight the tension between innovation-driven growth and sector headwinds.
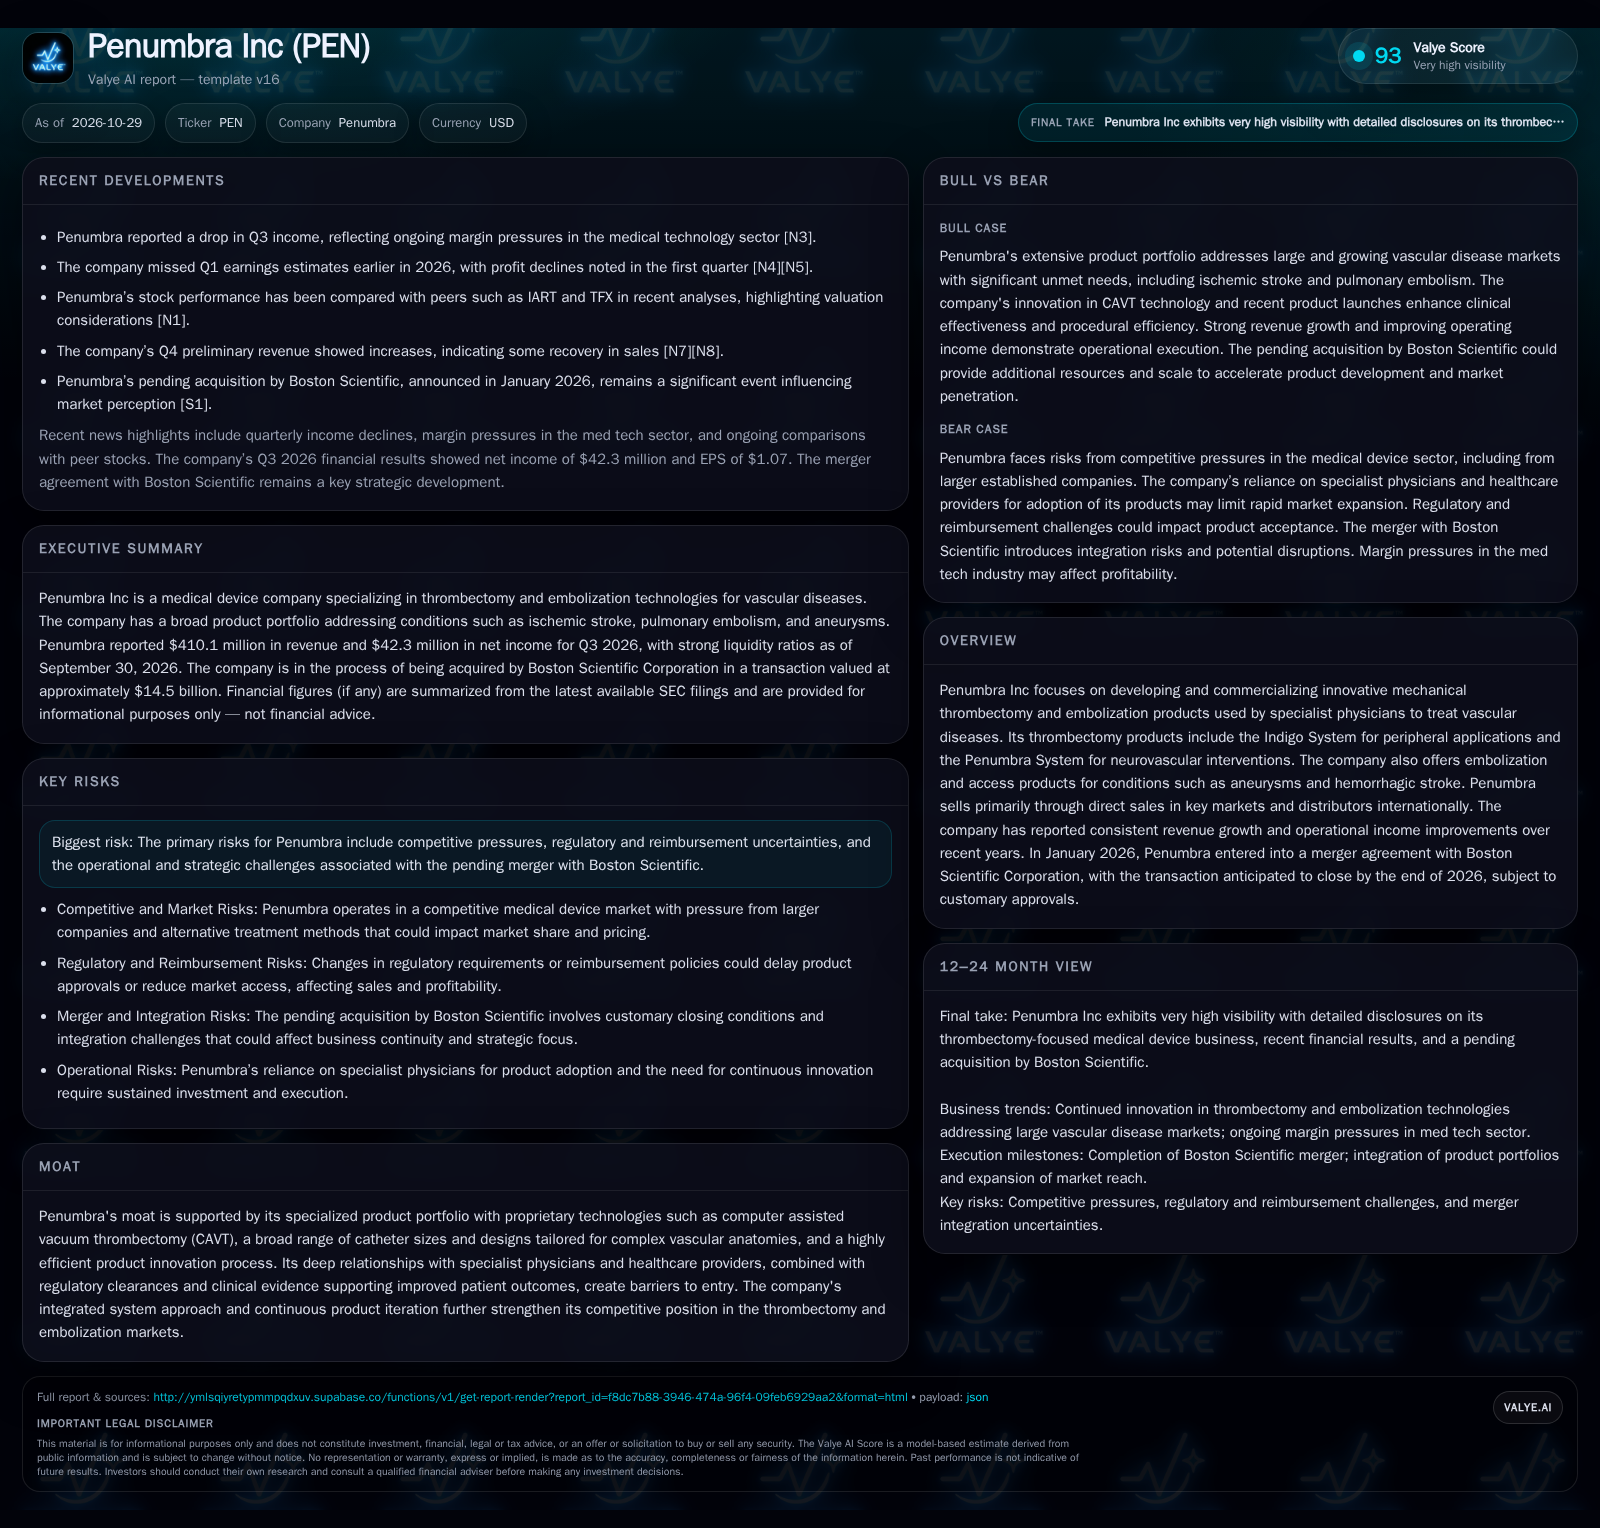
The pending Boston Scientific acquisition, valued at $14.5 billion, positions Penumbra for greater scale but introduces integration risks and exposes the business to sector-wide margin pressures. The next phase will hinge on sustaining product differentiation, navigating competitive and regulatory hurdles, and realizing merger synergies. [S1] [S2]
Penumbra Inc stands at a pivotal moment in its growth story, combining category-defining thrombectomy technologies with a broadening global reach and improving operational results. The company’s recent product launches and consistent revenue growth showcase its capacity for medical device innovation, but sector-wide margin pressure and the complexities of a $14.5 billion pending acquisition by Boston Scientific introduce new questions about sustained profitability and execution. As the vascular intervention market evolves, Penumbra’s next phase will be shaped by its ability to maintain clinical differentiation, scale globally, and navigate the integration of two major portfolios.
Merger, Margin Compression, and Next-Generation Launches Define the Current Landscape
Three facts dominate Penumbra’s strategic context in late 2026. First, the company reported $1,403.7 million in 2025 revenue, with $947.9 million from thrombectomy products and $455.7 million from embolization and access lines—demonstrating breadth and scale in core vascular segments. Second, Penumbra is in the midst of a $14.5 billion acquisition by Boston Scientific, with the transaction expected to close by the end of 2026, subject to approvals. This event will reshape the competitive landscape and operational structure. Third, despite continued innovation—evidenced by the Lightning Flash 3.0 and Lightning Bolt 12 launches—Penumbra faces margin pressure, as seen in Q3 2026’s $42.3 million net income and recent news of sector-wide profitability challenges. These dynamics set the stage for a high-stakes integration and a test of Penumbra’s ability to sustain innovation-led growth under new ownership. [S1] [S2] [N3] [N4] [N5]
How Penumbra’s Revenue Model and Cost Structure Shape Its Scalability
Penumbra’s business model is anchored in selling high-value, single-use devices for mechanical thrombectomy and embolization procedures—targeting specialist physicians in acute care settings. Revenue growth is primarily driven by procedure volume expansion, new product introductions, and increased penetration of advanced systems (such as CAVT-enabled catheters). Pricing power is possible when a device offers clear clinical advantages or workflow efficiencies, though reimbursement constraints and hospital budget cycles can limit upward price moves.
Gross margins in the medical device sector are typically high, benefiting from the consumable nature of products and relatively fixed manufacturing overhead once scale is reached. However, Penumbra’s recent margin pressures suggest increased competition and cost inflation are eating into profitability, or that product mix is shifting to newer, possibly lower-margin lines. Operating leverage can be significant as R&D and SG&A are spread across a growing installed base, but ongoing investment in salesforce expansion, clinical trials, and regulatory compliance is required to sustain momentum—especially in international markets where distributor economics differ.
Penumbra’s capital needs are moderate compared to more infrastructure-intensive medtech peers; however, product innovation cycles and regulatory hurdles can make cash flow lumpy. The company reported a current ratio of 5.89 for the period. [S2]
The scalability of Penumbra’s revenue model is also influenced by the evolving reimbursement landscape, which varies significantly across geographies and payers. In markets with fee-for-service reimbursement, increased procedure volumes directly translate to revenue growth, but in value-based care environments, there is growing pressure to demonstrate cost-effectiveness and improved patient outcomes. This dynamic may incentivize Penumbra to invest more heavily in real-world evidence generation and health economics studies to could support premium pricing and adoption. Additionally, penetration into emerging markets could be constrained by lower reimbursement rates and different hospital purchasing behaviors, requiring tailored commercial strategies and potentially impacting margin profiles in those regions.
Technological Differentiation Versus Scale: Penumbra’s Place in the Vascular Device Hierarchy
Penumbra’s defensibility rests on its proprietary CAVT technology, broad catheter portfolio, and a track record of rapid product iteration. The Indigo and Penumbra Systems have established a reputation for efficacy in challenging vascular interventions, supporting strong relationships with neurointerventionalists and vascular specialists. The company’s direct sales force in major geographies enhances physician engagement and feedback loops, while distributor channels allow for global reach—albeit with less margin control.
Competitive threats come from diversified medtech giants with larger R&D budgets and broader hospital relationships, as well as from emerging device makers targeting the same indications. Alternative treatments (such as pharmaceutical thrombolysis or surgical intervention) remain relevant for some patient populations, but mechanical thrombectomy is increasingly the standard of care for large-vessel occlusion and acute embolic events. The pending Boston Scientific acquisition raises the stakes: integration could amplify Penumbra’s reach and portfolio depth but may also dilute its focused innovation culture. Regulatory barriers and clinical data requirements create some moat, but technology cycles are shortening, making continuous advancement essential.
Penumbra’s technological differentiation also hinges on its ability to maintain a rapid innovation cycle, which requires substantial and sustained investment in R&D. While this can create a barrier to entry for smaller competitors, it also exposes the company to the risk of technological obsolescence if emerging modalities or alternative treatment paradigms gain traction. For instance, advances in pharmacological thrombolysis or minimally invasive surgical techniques could alter the competitive landscape, necessitating strategic pivots or partnerships. Additionally, the growing emphasis on personalized medicine and device customization may compel Penumbra to enhance its capabilities in data analytics and patient-specific device design to stay ahead.
The competitive interplay between scale and innovation culture is particularly critical in the context of the Boston Scientific acquisition. While Boston Scientific’s global infrastructure can accelerate market penetration and provide economies of scale, integration risks include potential dilution of Penumbra’s entrepreneurial agility and slower decision-making processes. Preserving the innovative mindset that drives product differentiation will require deliberate organizational design choices, such as maintaining dedicated innovation units or fostering cross-company collaboration platforms. Furthermore, harmonizing salesforce incentives and aligning clinical education programs post-merger will be essential to leverage combined strengths without losing the specialized focus that underpins Penumbra’s competitive advantage.
If Integration Unlocks Synergies, Penumbra Could Accelerate Global Adoption and Margin Expansion
In a favorable scenario, the Boston Scientific merger closes smoothly, combining Penumbra’s innovation engine with Boston Scientific’s global scale, reimbursement expertise, and hospital access. This could accelerate international adoption of newer systems like Lightning Flash 3.0, increase cross-selling opportunities in neurovascular and peripheral markets, and unlock cost savings from integrated supply chains and SG&A rationalization.
Upside confirmation would come from: (1) sustained double-digit revenue growth post-merger, (2) gross margin expansion as manufacturing efficiencies are realized, (3) new regulatory approvals or guideline endorsements for CAVT-enabled products, and (4) evidence of successful cross-selling or bundled sales to large hospital systems. A marked increase in R&D output or faster international product launches would further validate the thesis.
Stable Growth Amid Margin Headwinds and Incremental Integration Progress
The most plausible outcome is that Penumbra continues to grow, but at a moderated pace as it absorbs integration costs and faces persistent margin pressure. Revenue gains are likely to track procedure growth in core indications (ischemic stroke, pulmonary embolism) and incremental share gains from recent launches, but competitive pricing and higher SG&A may limit near-term margin improvement.
Any signs of salesforce turnover or physician adoption slowdowns would challenge this scenario.
Integration Complexity or Clinical Setbacks Could Disrupt Momentum and Erode Profitability
If integration with Boston Scientific proves difficult—whether due to cultural clashes, operational missteps, or regulatory delays—Penumbra could lose momentum in both innovation and commercial execution. Product overlap, salesforce disruption, or delayed launches could cede share to established competitors or new entrants. Further, if margin pressures worsen due to price competition or reimbursement changes, profitability could deteriorate even as revenue grows.
Downside evidence would include: (1) missed revenue or margin targets post-merger, (2) public reports of salesforce or R&D attrition, (3) delayed regulatory approvals or product recalls, and (4) negative shifts in clinical guideline recommendations or reimbursement policy. Any write-downs or restructuring charges related to the merger would also be red flags.
Milestones That Will Reveal Whether Penumbra’s Model Remains Disruptive Under New Ownership
Quarterly revenue growth in thrombectomy and embolization product lines, with breakout by geography and segment if disclosed.
Gross margin trends and commentary on cost pressures or manufacturing efficiencies.
Updates on the timing and regulatory progress of the Boston Scientific acquisition closing.
Evidence of cross-selling or portfolio integration success post-merger, such as bundled contracts or new hospital wins.
New product launch cadence and regulatory approvals, particularly for CAVT-enabled systems.
Retention rates of key sales and R&D personnel, especially through the integration phase, if disclosed.
Changes in reimbursement policy or clinical guideline endorsements for mechanical thrombectomy and embolization procedures.
Any early signals of product recalls, adverse events, or negative clinical trial outcomes impacting core platforms.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments