
Beam Global’s Strategic Shift: Expanding Commercial Reach and European Presence While Scaling Profitably
Beam Global’s shift from U.S. federal contracts to commercial and international customers has redefined its revenue mix, while acquisitions and new product launches target the world’s largest EV markets.
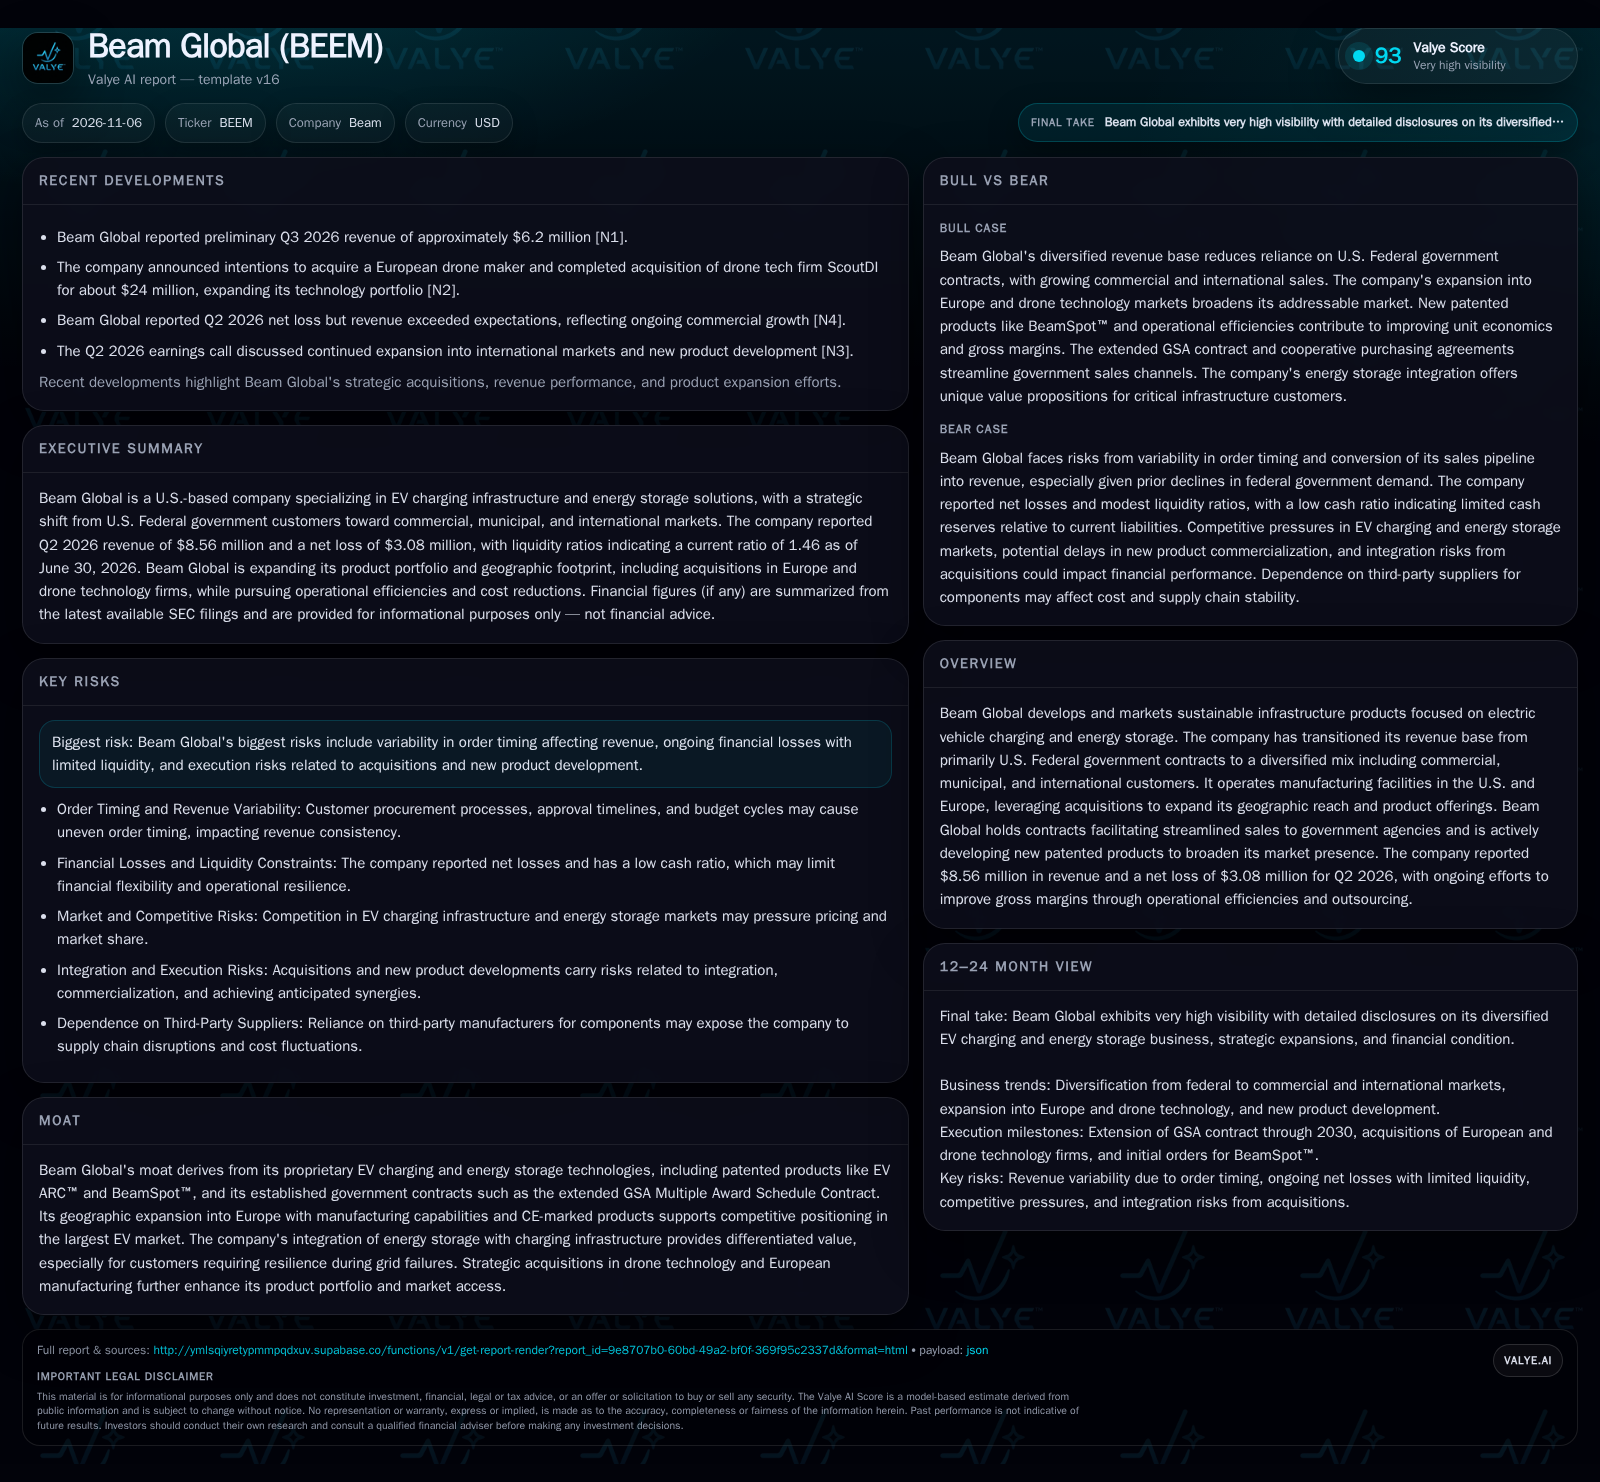
Beam Global has rapidly diversified away from U.S. federal government reliance, growing commercial and international revenue to the majority of its mix, especially with European expansion and new patented products.While operational efficiencies and acquisitions are aimed at improving margins and scale, persistent net losses and a reported cash ratio highlight continuing financial pressures. How well Beam can convert its broadened market access and product innovation into sustained, profitable growth remains the core question.
Beam Global’s business model is in the midst of a transformative pivot. Once heavily reliant on U.S. federal government contracts, the company now draws most of its revenue from commercial, municipal, and especially international customers, propelled by strategic acquisitions and a broadened product suite. This shift has opened up the European market—currently the world’s largest for EV infrastructure—while operational and product innovations aim to address both resiliency and regulatory needs.
From Federal Reliance to International Diversification: The Latest Operating Realities
Beam Global has fundamentally restructured its revenue streams. In 2025, federal government-related sales dropped to just 4% of total revenue from 32% in 2024, while non-government sources surged to 72% [S1]. International customers now account for 42% of revenues, up from 25% the prior year, reflecting deliberate expansion into Europe via acquisitions in Serbia and elsewhere [S1]. This strategic pivot is not academic: Q2 2026 revenue hit $8.56 million, but the company posted a net loss of $3.08 million and basic EPS of -$0.14 [S2]. Liquidity remains tight, with only $1.03 million in cash and equivalents and a cash ratio of 0.08 as of June 30, 2026 [S2]. Preliminary Q3 2026 revenue of $6.2 million suggests material quarter-to-quarter volatility [N1].
Beam’s product evolution continues, with the BeamSpot™ receiving initial orders and CE markings now allowing several products to be sold freely across the European Economic Area [S1]. The company’s operational focus is on driving gross margin improvement through lean manufacturing, outsourcing, and leveraging recent acquisitions [S1].
Economics of Scale, Margin Pressure, and Capital Constraints in EV Infrastructure
Beam Global’s business economics are shaped by the capital-intensive nature of EV charging and energy storage infrastructure. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. The company reported a declining gross margin in 2025 due to lower sales volume, but operational efficiency initiatives and the exclusion of non-cash items have led to an adjusted margin improvement [S1].
A critical economic question is whether Beam’s capital-light strategies—such as outsourcing, lean manufacturing, and leveraging acquired European capacity—can drive sustainable margin expansion. The business appears to rely on project-based sales (e.g., BeamSpot™ installations), but it is not clear if these are structured as recurring contracts, subscriptions, or one-off hardware deployments—each with different implications for revenue visibility and operating leverage.
Operational leverage is plausible but not yet demonstrated: as production scales and fixed costs are spread, gross margins could improve, especially if new products gain traction.
Strategic Positioning: Proprietary Tech and European Manufacturing vs. Industry Giants
Beam Global’s competitive positioning hinges on its proprietary, patented products—such as the EV ARC™, BeamSpot™, and new offerings like BeamFlight™—alongside its ability to deliver integrated energy storage with EV charging. This integration targets a unique value proposition for customers needing grid resilience, such as municipalities, hospitals, and fleet operators [S1].
Entry into Europe via acquisitions and CE-marked products gives Beam access to the world’s largest EV infrastructure market, but it also exposes the company to intense competition from established EV charging network operators, diversified industrials, and energy storage specialists. Many of these competitors have deeper capital bases, broader channel relationships, and economies of scale.
Beam’s extended GSA contract provides streamlined U.S. government sales, but with federal revenue now a small share, the company must win in commercial and municipal markets where procurement cycles, price sensitivity, and technical standards vary widely. The question is whether its differentiated technology and modular, off-grid solutions can carve out defensible niches against larger, better-funded rivals.
Unlocking Profitable Scale: Pathways to Margin Expansion and Market Share Gains
The favorable scenario for Beam Global is predicated on successfully scaling its commercial and international presence, translating new product launches like BeamSpot™ into recurring, high-margin revenue streams, and leveraging operational efficiencies to drive gross margin expansion. If Beam’s CE-marked products gain traction in Europe—especially among municipal and fleet customers facing grid resiliency mandates—the company could see accelerating order flow and improved project economics.
Confirmation of this scenario would require evidence of sequential revenue growth with stable or expanding gross margins, successful conversion of the sales pipeline into contracted orders, and a demonstrable reduction in cash burn. Additional signs would include repeat orders from key international customers, successful integration of acquisitions, and an reported liquidity-ratio trends or access to new, non-dilutive funding sources.
Falsification would come from stalled order momentum, persistent margin compression, or ongoing reliance on external capital to fund operations, suggesting that market access and product innovation are insufficient to overcome competitive and economic headwinds.
Commercial Diversification and European Growth Tempered by Financial Headwinds
The most plausible near-term path is one of continued commercial and international revenue growth, underpinned by new product adoption and the operational benefits of European manufacturing. However, quarter-to-quarter revenue volatility is likely as Beam transitions from large, lumpy federal contracts to a more fragmented, competitive commercial landscape.
Gross margin may gradually improve as cost-reduction initiatives take hold and as the product mix shifts toward higher-value, proprietary offerings.
Evidence supporting this scenario would include continued diversification of the customer base, signs of operational discipline (e.g., stable or improving adjusted gross margin), and careful management of working capital. Conversely, any deterioration in liquidity or inability to control operating costs would increase the risk of needing external financing or curtailing growth initiatives.
Execution Risks and Liquidity Constraints Collide: When Growth Outpaces Resources
Adverse outcomes for Beam Global would likely stem from a combination of execution missteps, order timing volatility, and financial pressures. If new product commercialization stalls or integration challenges from recent acquisitions (such as in Serbia or potential drone tech additions) disrupt operations, expected revenue growth could fail to materialize.
Supply chain disruptions or increased component costs—given reliance on third-party manufacturers—could further erode margins.
This downside would be confirmed by declining or erratic revenues, rising operating losses, negative working capital trends, and evidence of strained supplier or customer relationships.
Milestones That Will Determine Whether Beam Global’s Strategic Shift Delivers Profitable Scale
Sequential revenue growth by geography and product line—especially the traction of BeamSpot™ and other new offerings in Europe—would help test whether recent expansion is translating into market share.
Adjusted gross margin trends (if disclosed), particularly the impact of operational efficiencies and product mix, will indicate whether Beam can move toward sustained profitability.
Cash ratio and quarterly cash burn: monitoring whether liquidity improves or deteriorates is essential given the reported cash balance and ongoing net losses.
Order backlog or contracted sales pipeline (if disclosed) would provide visibility into demand consistency and conversion of opportunities into revenue.
Repeat customer orders and customer concentration—especially among commercial and municipal clients—would signal progress toward recurring revenue and reduced order volatility.
Integration progress and cost synergies from European acquisitions, including manufacturing ramp-up and supply chain rationalization, would demonstrate execution capability.
Evidence of successful new product commercialization, such as volume shipments, expanded CE-marked product sales, or cross-selling into new markets, would be a leading indicator of future growth.
Access to new, non-dilutive capital or improvement in working capital management would reduce financial risk and support ongoing investment in growth.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments