
Gyrodyne’s Liquidation Strategy: Entitlement Hurdles, Asset Value Realization, and the Stakes of Execution
Gyrodyne, LLC is in the final act of its corporate life, seeking to maximize shareholder distributions through strategic entitlements and asset sales of its medical and industrial properties in New York. With a single executive at the helm, ongoing legal challenges, and conditional sale agreements in play, the company’s outcome now hinges on the successful navigation of regulatory, market, and management risks.
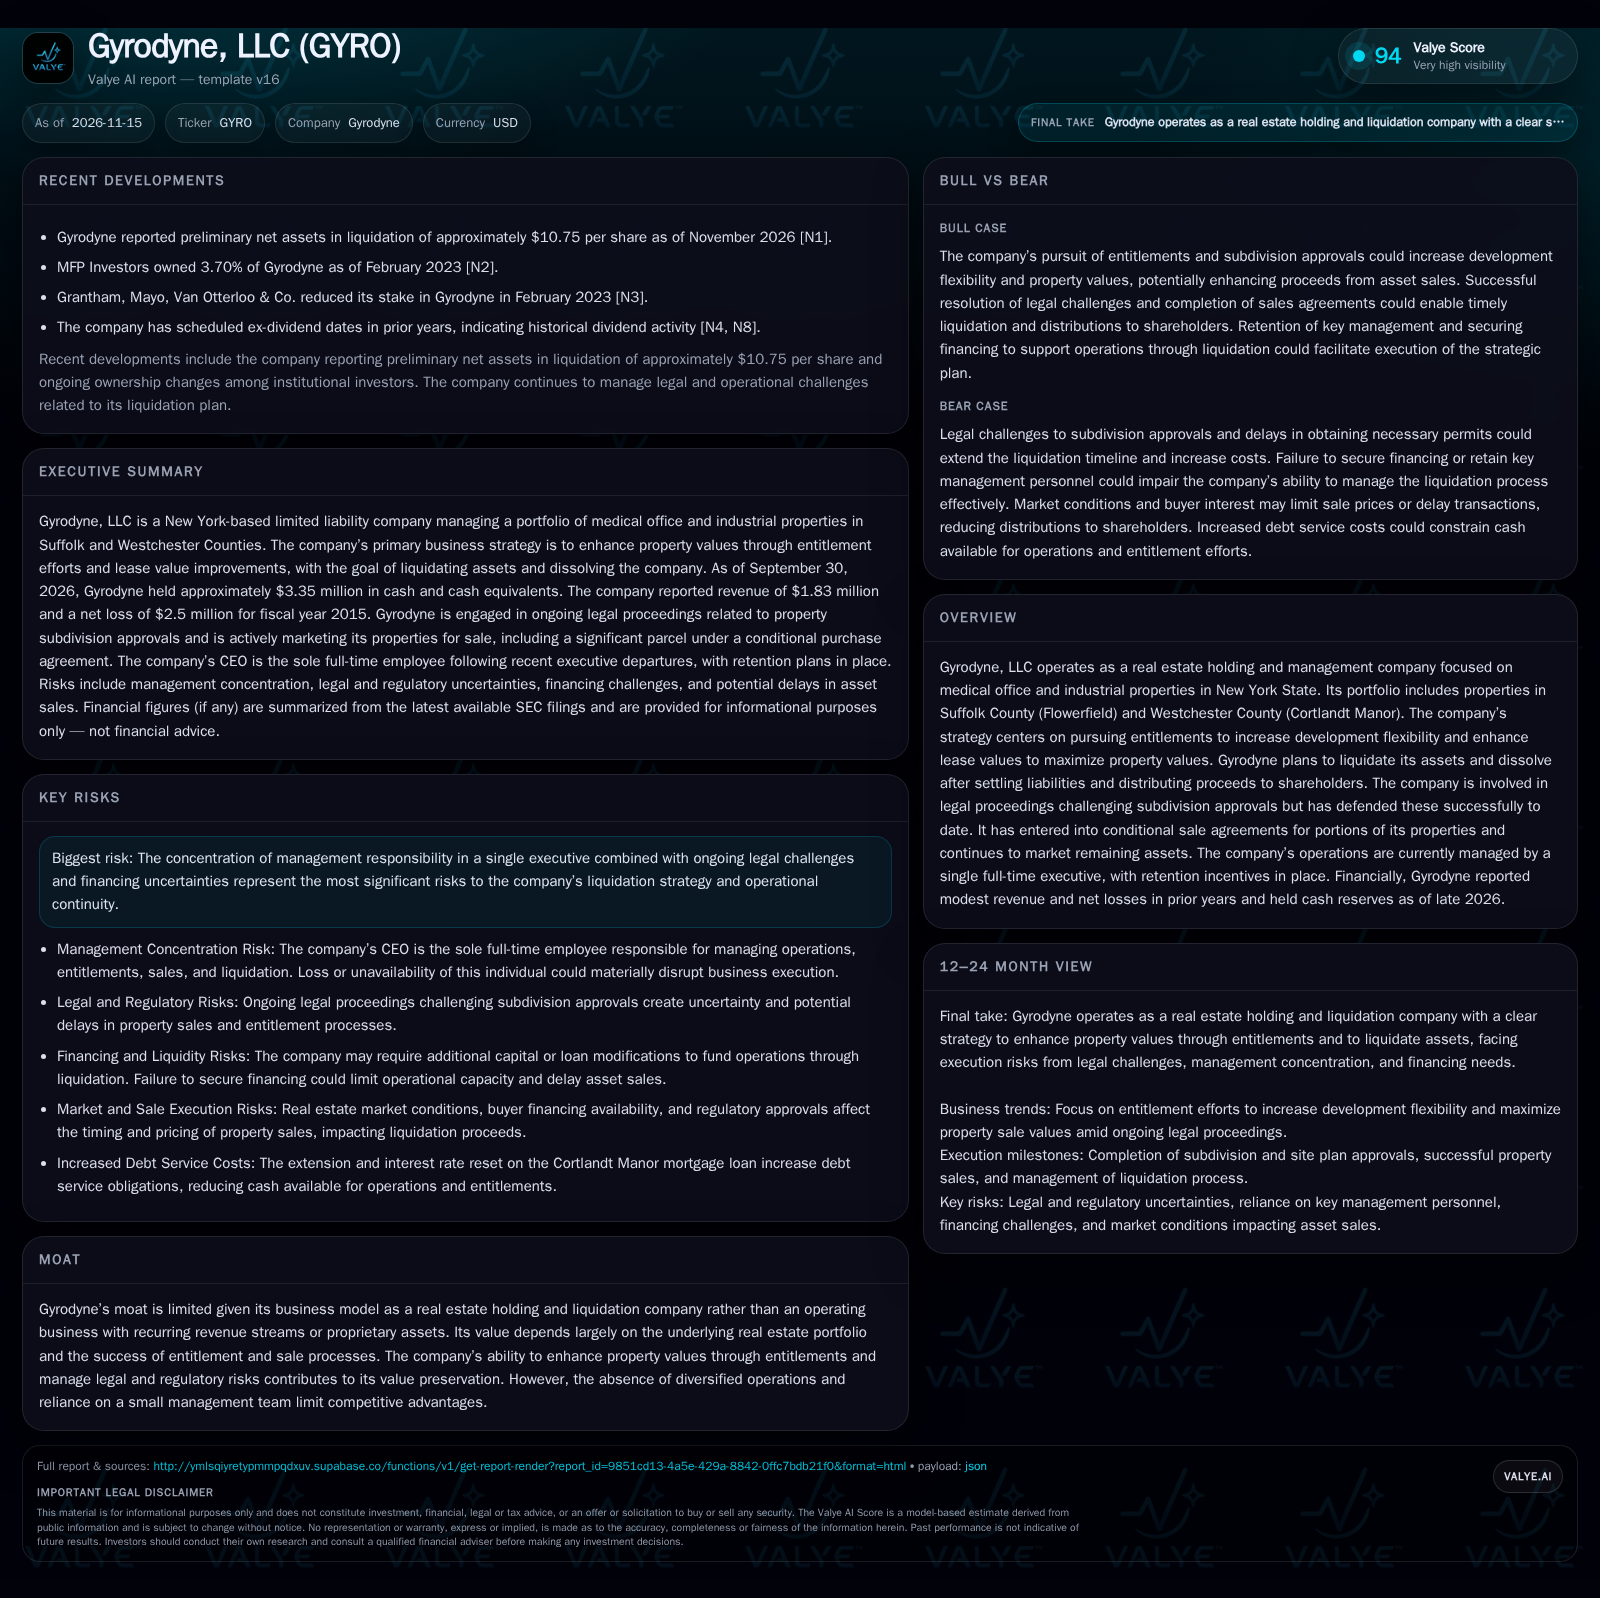
Gyrodyne, LLC is actively liquidating its New York real estate portfolio, aiming to increase asset value through entitlements and subdivision approvals. A major sale agreement for a portion of its Flowerfield property is contingent on regulatory success, while legal appeals and management concentration present execution risks. Net assets in liquidation are preliminarily reported at $10.75 per share, but the realization of this value depends on resolving legal, market, and operational uncertainties. [S1] [N1]
Gyrodyne, LLC is winding down, with a clear objective: maximize the value of its New York medical and industrial real estate holdings through entitlements and strategic asset sales, then distribute the proceeds to shareholders and dissolve. The stakes are high, as the company faces regulatory and legal headwinds, a concentrated management structure, and the pressure to execute sale transactions before market or operational risks erode asset value. With a major conditional sale pending and preliminary liquidation value estimated at $10.75 per share, Gyrodyne’s path to value realization is now defined by its ability to overcome approval challenges, close deals, and manage its final chapter efficiently. [S1] [N1]
Recent Events Define the Liquidation Landscape
As of November 2026, Gyrodyne has reported preliminary net assets in liquidation of approximately $10.75 per share, providing a reference point for potential shareholder distributions upon dissolution. [N1] The company’s most significant near-term transaction is a conditional Purchase and Sale Agreement for a 49-acre parcel of its Flowerfield property, with a price range of $24 million to $28.74 million, contingent on receiving subdivision and site plan approvals. [S1] Legal appeals under Article 78 continue to challenge these approvals, though Gyrodyne has successfully defended the Planning Board’s determinations at earlier stages. [S1] Operationally, the company is now managed by a single executive, CEO and CFO Gary Fitlin, following the COO’s recent departure, with retention incentives in place to mitigate the risk of management loss. [S2] These developments set the stage for the company’s final efforts to maximize and realize asset value.
How Gyrodyne’s Value Is Unlocked (or Erodes) Through Asset Sales
Gyrodyne’s economics are fundamentally transactional rather than recurring: the company generates value by enhancing and selling its real estate holdings, not by operating them for ongoing rental income. Its approach focuses on securing entitlements—particularly subdivision and site plan approvals—to increase the attractiveness and potential sale value of its properties. The largest economic lever is the successful sale of subdivided parcels at premium prices, which can only be realized if regulatory and legal hurdles are cleared.
The capital structure is relatively simple, but the company’s cash position ($3.35 million as of September 2026) [S2] must fund ongoing legal, operational, and marketing efforts until all assets are disposed. Debt service costs have increased following the extension and rate reset on the Cortlandt Manor mortgage, raising the cost of delay or failed execution. [S2] Operating leverage is minimal—there are few fixed operating costs left, but the company is exposed to potentially large one-time expenses (legal costs, transaction fees, property maintenance) that could impact final distributions.
The company’s economics are highly sensitive to timing and sale prices. If entitlements are delayed or buyers retrench, carrying costs and debt service will erode net asset value. Conversely, swift approvals and competitive bidding for parcels could push realized proceeds toward the upper end of current estimates.
Entitlement Strategy and Market Dynamics Shape Competitive Outcomes
Gyrodyne’s competitive position is defined less by traditional real estate rivalry and more by its ability to successfully navigate local regulatory systems and execute asset sales before value decays. The core challenge is not outcompeting other landlords, but rather maximizing the value of unique parcels through regulatory approvals and optimal timing.
There is no proprietary product or recurring customer relationship to protect; instead, the company’s ‘moat’ rests on its ability to extract value from unique locations and its success in managing the entitlement process. This is a fragile advantage: legal and regulatory setbacks can erase months or years of value creation, while market conditions—interest rates, capital availability, and local real estate demand—determine buyer appetite.
Peer groups include other real estate liquidators and special situation property companies, but Gyrodyne’s exposure to legal and entitlement risk is unusually concentrated due to its small portfolio and the binary nature of its primary sale processes.
If Approvals and Transactions Align, Shareholder Value Could Top Current Estimates
The most favorable outcome for Gyrodyne would be a rapid and successful conclusion to ongoing legal appeals, resulting in final subdivision and site plan approvals for the Flowerfield and Cortlandt Manor properties. This would allow the $24–$28.74 million Flowerfield parcel sale to proceed, potentially at the higher end of the range if buyer demand intensifies. Subsequent marketing and sale of remaining parcels, either individually or as a package, could benefit from similar entitlement-driven value enhancement.
Confirmation of this scenario would require public announcements of resolved legal proceedings, finalized approvals, and executed sales at or above the current contractual price ranges. Additional upside could materialize if market conditions produce competitive bidding or if the company receives an attractive acquisition offer for all remaining assets.
Falsification would be evident if legal delays persist, approvals are denied or overturned, or sale prices fall below expectations due to weak demand or adverse market shifts.
Asset Value Realization Hinges on Legal Resolution and Market Absorption
The most plausible scenario is a drawn-out but ultimately successful entitlement process, with Gyrodyne gradually securing the necessary approvals to complete its planned asset sales. The $24–$28.74 million Flowerfield sale is likely to close if legal appeals are resolved within a reasonable timeframe, with remaining assets marketed and sold in line with their entitlement status and local real estate trends.
Shareholder distributions would approximate the preliminary net assets in liquidation ($10.75 per share), with modest adjustments for final transaction costs, legal expenses, and any divergence in sale prices versus estimates. The process may extend longer than management hopes, and the risk of further legal or market setbacks is non-trivial, but the fundamental asset value is likely to be realized in some form barring a material adverse event.
Evidence confirming this scenario would include steady progress on regulatory milestones, incremental asset sales at prices near estimates, and continued management retention. Falsification would involve major legal reversals, loss of key executive leadership, or significant market deterioration leading to forced sales at discounts.
Execution Slips: Legal, Management, or Market Failures Erode Liquidation Proceeds
The downside risk is that legal appeals stall or reverse subdivision approvals, preventing key asset sales and forcing Gyrodyne into a protracted holding pattern. Mounting legal costs, increased debt service from the higher Cortlandt Manor mortgage rate, and ongoing property maintenance expenses could steadily erode net asset value.
Another risk vector is the loss or unavailability of the sole remaining executive. Management concentration means that illness, departure, or burnout could materially disrupt execution, delaying sales or compromising negotiations. If buyer demand weakens—due to rising interest rates, local market oversupply, or broader economic downturn—sale prices could fall below current estimates, reducing or even eliminating distributions to shareholders.
Confirmation of this scenario would be visible in failed or excessively delayed sales, renewed or escalated legal challenges, distress-driven asset disposals, or a decline in reported net assets in liquidation in future filings.
Milestones That Will Define Gyrodyne’s Liquidation Outcome
Resolution status and timing of Article 78 legal appeals related to the Flowerfield subdivision and site plan approvals.
Public disclosure of final sale terms and closing of the 49-acre Flowerfield parcel to B2K Smithtown LLC, including any price adjustments.
Progress announcements on additional parcel sales or combined property transactions, and whether these meet or exceed internal valuation estimates.
Updates on management continuity—specifically, retention of Gary Fitlin or any sudden executive turnover.
Operating expense and debt service trends, particularly if legal or holding costs begin to materially reduce net assets in liquidation.
Any change in reported net assets in liquidation per share in future filings, which would signal value realization or erosion.
Evidence of new financing arrangements or the need for additional capital to cover extended holding or legal periods, if disclosed.
Market demand signals for medical office and industrial properties in Suffolk and Westchester counties, which could impact sale prices and timing.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments