
Omega Flex: Product Concentration, Innovation, and Margin Pressures in a Specialized Piping Market
Omega Flex faces a critical inflection as product re-engineering and regulatory wins seek to offset rising cost pressures and a heavily concentrated revenue base. The company’s high-margin niche is being tested by raw material volatility, competition from larger peers, and the need to prove that recent product and channel moves can sustain growth beyond core gas piping systems.
Omega Flex’s core business in flexible metal hose and gas piping systems is under pressure as raw material costs and competition erode profitability. [N1] [S2]
Omega Flex, a specialist in flexible metal hose and gas piping systems, stands at a crossroads as margin pressures intensify and its product concentration risk becomes more pronounced. While the company’s recent product re-engineering initiatives and regulatory certifications signal a drive toward innovation and market expansion, these steps must counterbalance both rising input costs and the persistent threat from larger, well-capitalized competitors. With most of its revenue still tied to a narrow set of offerings, Omega Flex’s ability to diversify its portfolio and defend profitability will shape its trajectory over the next several years.
Recent Developments Test Omega Flex’s Resilience
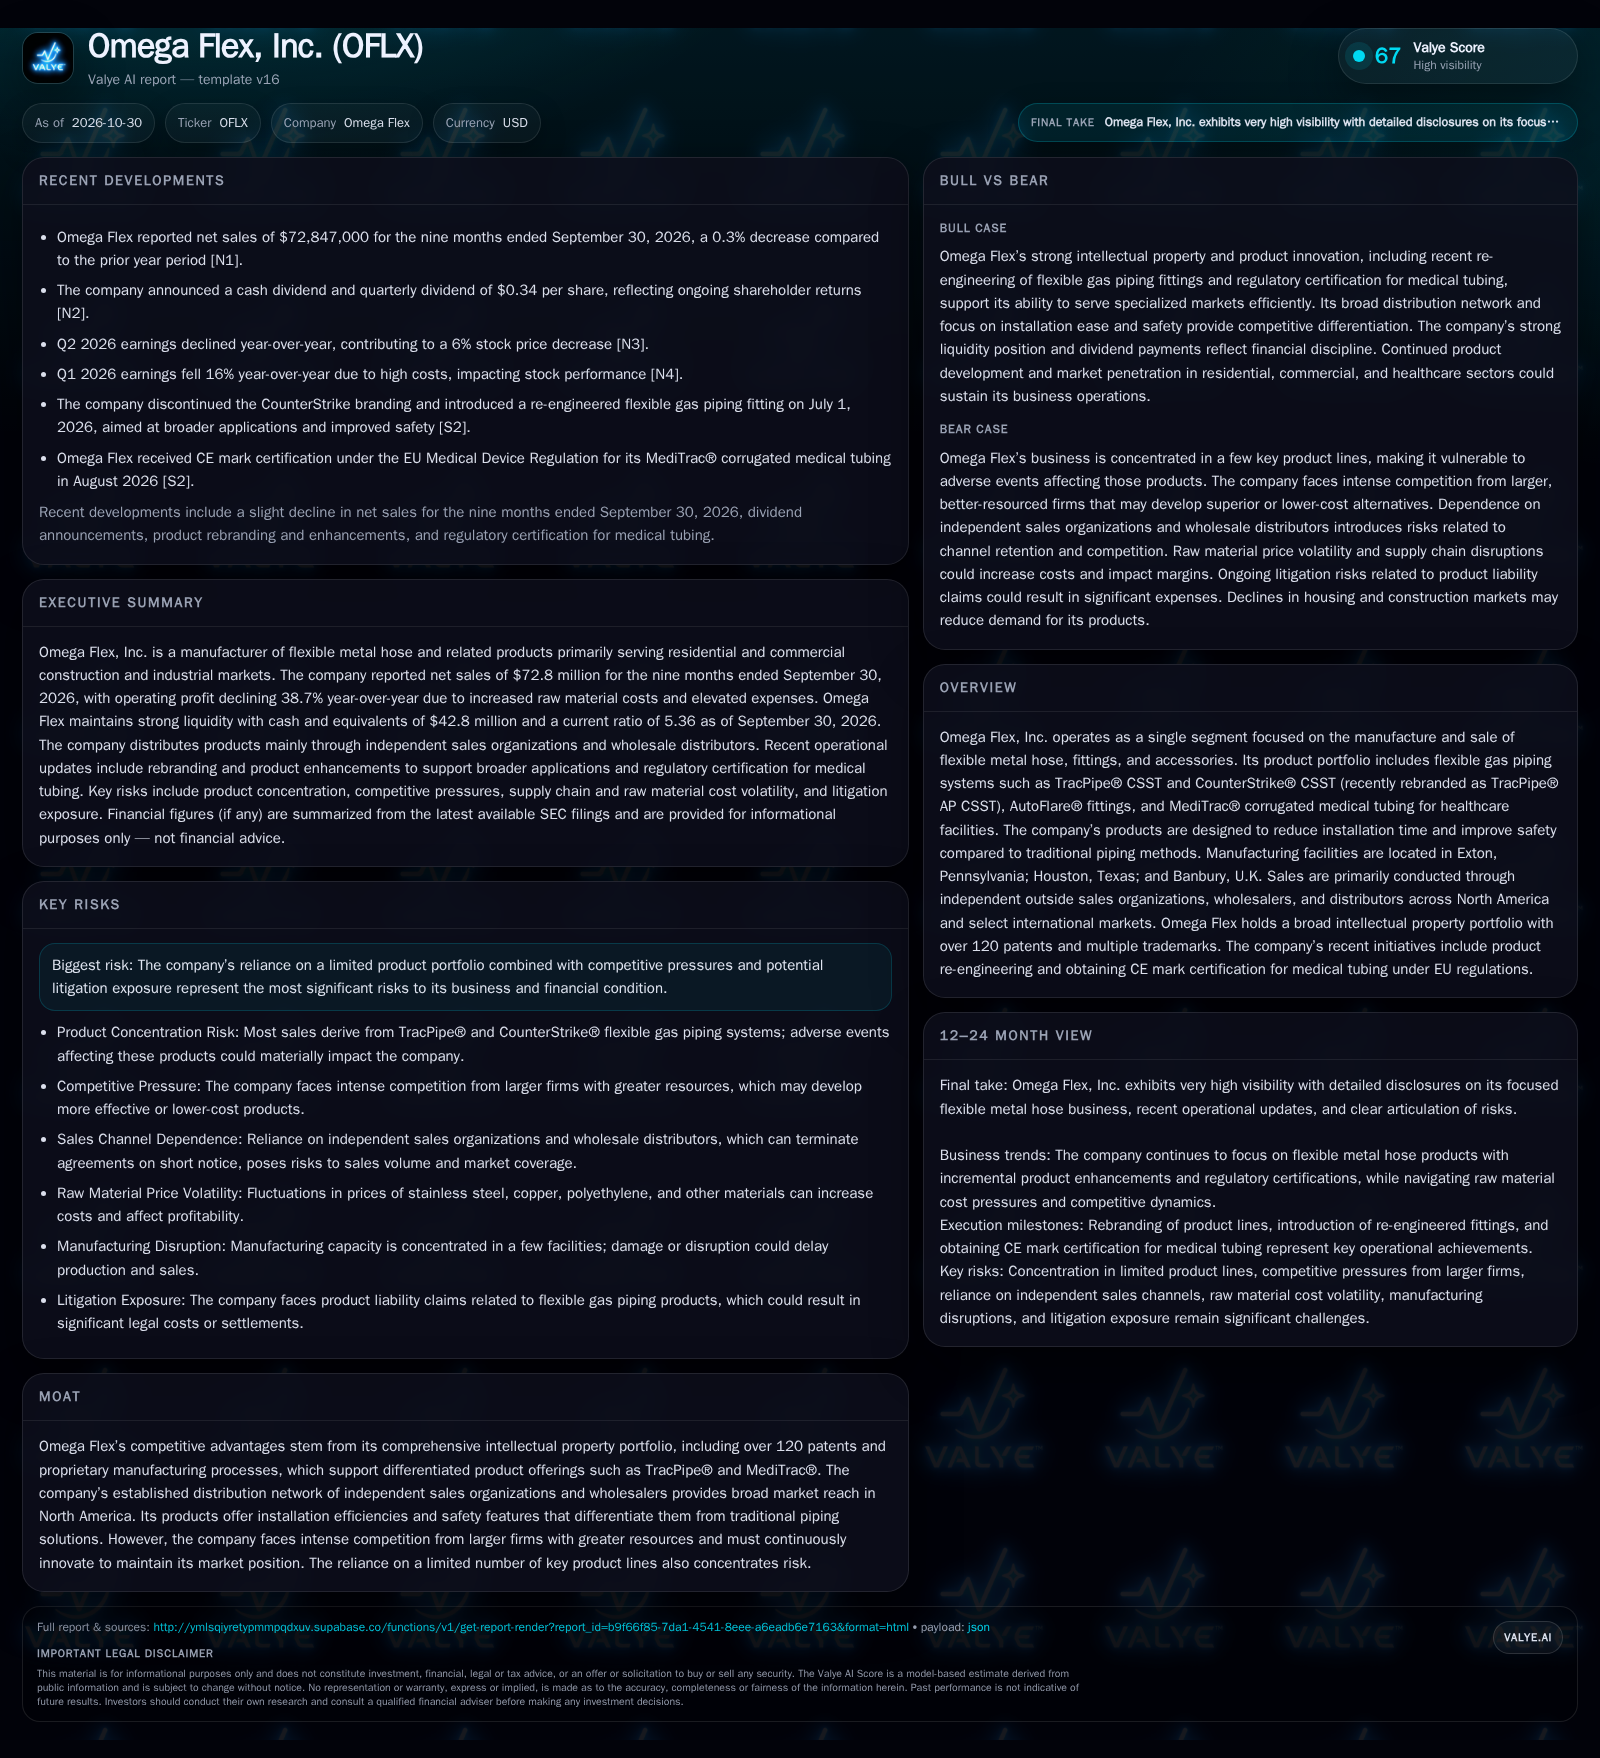
Omega Flex reported net sales of $72.8 million for the nine months ended September 30, 2026, a marginal 0.3% decrease from the prior year, indicating stagnant top-line momentum amid a challenging operating environment. However, the company’s operating profit fell sharply by 38.7% year-over-year, primarily due to increased raw material costs and elevated operating expenses. This margin compression has been reflected in stock performance, with notable declines following both Q1 and Q2 earnings releases. [N1] [S2]
Margin Dynamics and the Economics of Specialized Piping
Omega Flex’s revenue model is heavily reliant on sales of flexible gas piping systems and related fittings, primarily through wholesale and distribution channels. The company’s products, such as TracPipe® CSST and AutoFlare® fittings, are marketed on the basis of installation speed and safety, which can command premium pricing versus traditional rigid piping. However, with most sales concentrated in a few core product lines, the business faces high product concentration risk—any disruption or obsolescence could have outsized impact on both revenue and fixed-cost absorption.
Gross margins in this niche have historically been robust, benefiting from proprietary manufacturing processes and IP protection. Yet, the company’s exposure to commodity inputs such as stainless steel and copper introduces significant cost volatility. These raw material swings are difficult to fully pass through to customers in real time, especially in competitive bidding or distributor-driven sales environments. As a result, periods of rising input costs can compress margins quickly, as seen in the recent financial results.
Operating leverage is present but can be a double-edged sword: incremental sales from new products or regulatory wins could disproportionately benefit profits, but volume declines or persistent cost inflation erode profitability due to the company’s fixed manufacturing overhead. Capital needs are relatively modest, with no indication of large-scale expansion projects, but working capital swings can be material during periods of inventory buildup or distributor de-stocking. The cited source reports dividend-related activity; that disclosure alone does not establish dividend-policy continuity, management confidence, or a material constraint on capital flexibility.
Innovation and IP Versus Scale-Driven Rivals
Omega Flex’s competitive posture is anchored by its portfolio of over 120 patents and trademarks, which underpin differentiated offerings in flexible gas and medical piping. The company’s value proposition—ease of installation and enhanced safety—has enabled it to carve out a defensible niche, particularly in retrofit and specialty construction applications. However, this moat is not absolute: larger building products manufacturers and diversified industrials possess greater scale, lower input costs, and broader product portfolios, allowing them to bundle solutions or undercut on price.
The distribution model, relying on independent sales organizations and wholesalers, provides broad reach but also limits direct customer engagement and increases channel risk. Distributors can switch suppliers if price or service falters, and the absence of direct end-customer relationships may make it harder to defend share when competitors launch similar or improved products. Furthermore, the company’s exposure to product liability litigation—common in the gas piping sector—can be more destabilizing for a specialized player than for multi-line conglomerates.
Technology substitution risk is present but gradual. While flexible metal hose has clear advantages in certain applications, advances in composite materials, plastic piping, or integrated building systems could erode the company’s addressable market over time if Omega Flex does not stay ahead with innovation or regulatory adaptation.
How Product Innovation and Regulatory Wins Could Shift the Growth Curve
A favorable scenario for Omega Flex involves successful commercialization of its recently re-engineered gas piping fittings and expanded adoption of MediTrac® medical tubing, particularly in international markets following CE certification. If the new fitting demonstrably improves safety and installation efficiency, it could recapture share lost to competitors or expand the addressable market to new construction segments. The CE mark for MediTrac® opens the door to EU healthcare projects, which could provide a higher-margin, less cyclical revenue stream if the company can establish meaningful distribution partnerships and win reference accounts.
Upside would be confirmed by a return to sales growth above industry averages, stabilization or expansion of operating margins, and evidence that new products are gaining traction—such as increased sales mix from MediTrac® or the re-engineered fitting, or entry into new geographies. Additional signs would include successful litigation defense, major new distributor or OEM wins, and a shift in channel commentary from price to value or technology differentiation.
Incremental Progress Amid Persistent Margin Pressure
The most plausible trajectory is one of incremental product improvement and modest revenue growth, offset by continued margin pressure from raw material costs and channel competition. Omega Flex may succeed in defending its share in core gas piping applications, with the re-engineered fitting and rebranding offsetting some competitive encroachment but not dramatically altering the company’s growth profile. The MediTrac® CE mark may yield some international wins, but ramp-up is likely to be gradual given regulatory, distribution, and hospital procurement cycles.
Confirmation of this scenario would include continued flat-to-low single-digit sales growth, periodic margin compression during input cost spikes, and an ongoing need to refresh legacy products to maintain relevance. Distributor and channel stability would underpin this path, but the company would remain vulnerable to any major shift in construction activity, litigation outcomes, or distributor alignment.
When Cost Volatility and Channel Dependence Compound
An adverse outcome could develop if raw material prices remain persistently high or spike further, and Omega Flex is unable to either pass through these costs or offset them with volume gains. In this scenario, operating margins could erode to unsustainable levels, particularly if distributors push back on price increases or switch to alternative suppliers. Product concentration risk would be acute if a safety event, regulatory change, or successful competitor innovation undermines demand for TracPipe® or its replacement.
Evidence of downside would include sequential sales declines, sustained negative operating leverage, distributor defections, adverse litigation outcomes, and a material drop in cash reserves as the company attempts to defend share or settle claims. A failure to gain traction with new products or regulatory certifications, or negative feedback from early adopters in the EU medical market, would further validate this scenario.
Milestones That Will Determine Omega Flex’s Future Profitability and Market Reach
Quarterly gross and operating margin trends, reflecting the company’s ability to manage input cost inflation and maintain pricing power.
Revenue contribution and sales mix from newly launched products such as the re-engineered gas piping fitting and MediTrac® medical tubing, if disclosed.
Progress in securing new distribution agreements or expanding into international markets, particularly following the CE mark for medical tubing.
Channel retention rates and feedback from key distributors and independent sales organizations—any sign of share loss or channel churn would be material.
Litigation developments, settlements, or new claims related to product liability, which could materially impact cash flow and reputation.
Raw material price trends for stainless steel, copper, and related inputs, as well as the company’s ability to adjust pricing or hedge costs.
Inventory levels and working capital swings, which may signal distributor de-stocking or demand volatility.
Dividends and capital allocation decisions—whether continued payouts constrain investment in R&D or new product launches.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments