
USA TODAY Co.: Digital Transformation, Platform Reliance, and Indebtedness in a Shifting Media Landscape
As USA TODAY Co. leans into digital subscriptions and marketing solutions, the company faces shrinking legacy revenues, heavy debt, and mounting dependence on third-party platforms and AI-driven distribution—raising the stakes for execution and strategic adaptation.
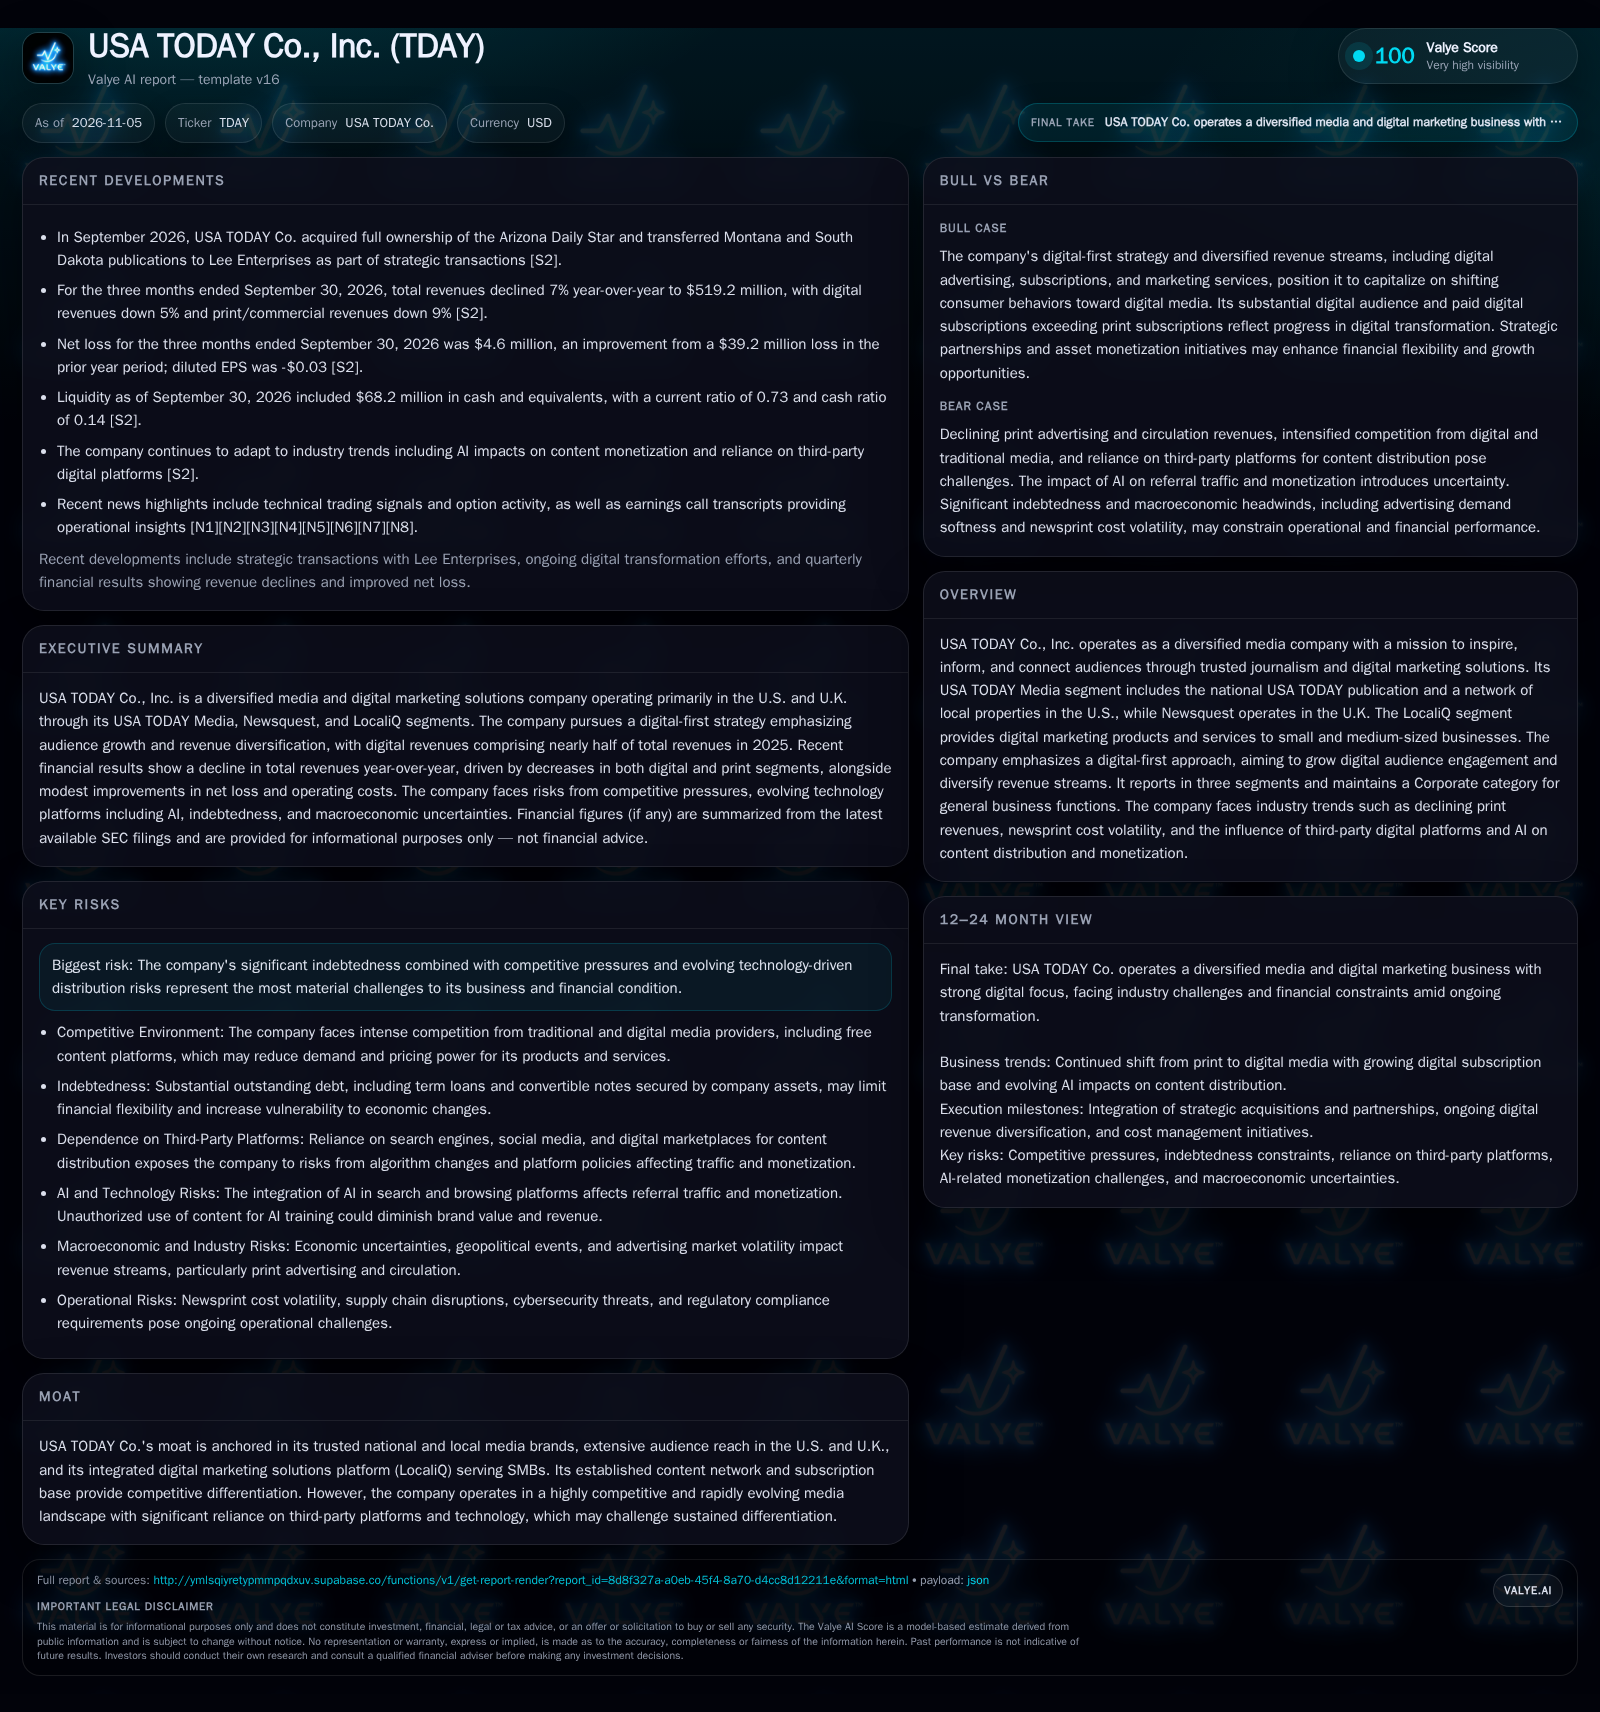
USA TODAY Co. has surpassed 1.5 million paid digital-only subscriptions and digital revenues now represent nearly half of its total business. However, year-over-year declines in both digital and print revenue, significant indebtedness, and heightened reliance on third-party platforms for distribution and monetization complicate its digital-first ambitions. The company’s next phase hinges on execution in content innovation, cost management, and adaptation to rapidly evolving digital and AI-driven ecosystems [S1] [S2].
USA TODAY Co. stands at a critical juncture in the transformation of legacy media. With digital revenues now representing nearly half of its business and paid digital-only subscriptions exceeding print, the company is executing on a digital-first strategy in an industry pressured by secular print declines and unpredictable advertising markets. Yet, persistent revenue contraction, mounting debt, and a business model increasingly tied to the policies and algorithms of tech platforms and AI intermediaries expose it to new risks and execution challenges. The company’s trajectory over the next several years will be shaped by its ability to innovate and monetize digital audiences, manage its capital structure, and adapt swiftly to both competitive threats and platform-driven change [S1] [S2].
Recent Operating Trends: Digital Gains, Revenue Pressure, and Capital Constraints
USA TODAY Co. reported total revenues of $519.2 million for the quarter ended September 30, 2026, down 7% from the prior year. Digital revenues declined 5% while print and commercial revenues fell 9%. Despite these declines, the company’s net loss improved sharply to $4.6 million (from $39.2 million a year ago), reflecting cost control and operational efficiencies. Digital revenues comprised 46% of the company’s total in 2025, reaching $1.1 billion, and paid digital-only subscriptions surpassed print subscriptions, signaling traction in the digital transformation. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S1] [S2]
Revenue Mix and the Economics of Digital-First Transformation
The company’s core economics are in flux as it shifts from print-dependent advertising and circulation to a digitally driven model. Digital revenues now represent nearly half of the business, sourced from a mix of advertising, subscriptions, and digital marketing services (through LocaliQ) [S1]. This transition offers potential for higher margins due to lower distribution costs and scalable platforms, especially if digital subscription growth continues. However, digital advertising is intensely competitive, with pricing and volume dictated by broader ad market cycles and the company’s ability to target, measure, and retain audiences. LocaliQ’s marketing services for SMBs provide a diversified revenue stream, but customer acquisition and retention costs can be substantial in the fragmented digital marketing sector.
Print revenues remain in structural decline, with newsprint cost volatility adding uncertainty to legacy economics. The company’s significant fixed costs—legacy infrastructure, content creation, and servicing debt—create operating leverage, making revenue declines acutely painful and cost discipline critical. The capital structure, weighted by $900 million in secured loans and convertible notes, constrains investment flexibility and heightens sensitivity to cash flow swings [S1] [S2].
Content Scale, Platform Dependence, and the Shifting Moat
USA TODAY Co. benefits from national and local brand equity, a substantial digital audience, and a growing base of paid digital subscriptions—assets that offer some differentiation in a crowded market. Its integrated digital marketing solutions, especially for SMBs, broaden its relevance beyond traditional news. However, the company’s moat is under constant pressure from both legacy and digital-native competitors, including global platforms, local publishers, and free content providers.
A crucial vulnerability is the heavy reliance on third-party platforms—search engines, social media, and increasingly, AI-powered aggregators—for content distribution, audience acquisition, and monetization. Algorithm changes or platform policy shifts can sharply impact referral traffic, advertising rates, and subscription funnels. The emergence of generative AI and large language models as intermediaries further complicates the economics, raising risks of content commodification and challenges in asserting pricing power or negotiating licensing terms. The company’s ability to innovate in content formats, user engagement, and direct-to-consumer relationships will determine the sustainability of its competitive advantages [S1] [S2].
Unlocking Digital Leverage Through Audience Growth and Platform Innovation
If USA TODAY Co. can accelerate digital subscription growth, deepen engagement, and expand its digital marketing services, the business could achieve renewed revenue growth and margin expansion. Success would likely require effective content innovation (including formats tailored for mobile and AI-driven discovery), improved data-driven audience targeting, and strategic partnerships to secure favorable content distribution or licensing arrangements with tech platforms and AI intermediaries.
Evidence of this scenario would include a sustained increase in digital-only subscriptions, stabilization or growth in digital advertising and marketing services revenues, and improved operating margins despite ongoing print decline. Additional signs would be successful renegotiation of content licensing deals with major platforms, higher customer retention rates for LocaliQ, and visible cost discipline enabling deleveraging or reinvestment. Confirmation could also come through updates on direct-to-consumer initiatives or proprietary platform development that reduces reliance on external channels.
A falsification of this scenario would be persistent digital revenue stagnation, further margin erosion, or public evidence that major platforms are diverting traffic or devaluing licensed content.
Navigating Flat Digital Growth and Managed Print Decline
The most plausible trajectory is one of ongoing print revenue erosion, modest digital subscription and marketing service growth, and continued pressure on digital advertising yield due to industry-wide competition and evolving platform dynamics. In this scenario, operating cost reductions and portfolio rationalization (such as the Arizona Daily Star acquisition and other strategic transactions) help offset top-line pressure, but overall revenue remains flat to declining.
Financial performance stabilizes around breakeven or modest losses, with periodic refinancing or asset sales needed to manage debt obligations. The company maintains its relevance through brand strength and a loyal digital subscriber base, but does not achieve breakout growth. Evidence would include steady or slightly rising digital subscription counts, continued cost control, and no material improvement in revenue or margin trends. A reversal in digital audience growth or a significant negative shock from platform changes would challenge this scenario.
Platform Shocks, Ad Volatility, and Debt Constraints Trigger a Downturn
A more adverse trajectory unfolds if major technology platforms or AI-powered aggregators alter their algorithms or policies in ways that sharply reduce referral traffic or devalue distributed content, leading to rapid declines in digital advertising and subscription funnels. If this occurs alongside a weak advertising market, persistent print cost inflation, or macroeconomic shocks, revenue could contract faster than cost reductions can be implemented.
In this environment, high fixed costs and debt service quickly strain liquidity, potentially forcing distressed asset sales, restructuring, or covenant breaches. Evidence would include a sudden drop in digital traffic or ad rates, rising churn in digital subscriptions or SMB marketing services, negative working capital trends, and signals of financial distress such as debt covenant concerns or emergency financings. Confirmation could also come from public company guidance downgrades or regulatory disclosures about platform-related revenue impacts.
Milestones and Metrics That Will Shape USA TODAY Co.’s Next Chapter
Quarterly growth in paid digital-only subscriptions, including churn and conversion rates if disclosed, to gauge the durability of digital transformation.
Digital advertising and marketing services revenue trends, especially in relation to industry benchmarks and platform policy changes.
Updates on content licensing negotiations and partnerships with major technology and AI platforms, including any revenue-sharing or exclusivity terms if disclosed.
Operating margin progression and cost management initiatives, with attention to the impact of further print rationalization or digital investment.
Liquidity developments, including cash flow from operations, working capital changes, or any refinancing or asset sale activity.
Debt service coverage and any changes to loan covenants, refinancing terms, or capital structure adjustments.
Evidence of platform-driven traffic or monetization shocks—such as sharp changes in referral sources, search/social visibility, or AI-driven content aggregation impacts.
Retention and growth of LocaliQ customers, with customer acquisition costs and gross margin trends, if disclosed.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments