
Armlogi Holding Corp.: Scaling E-Commerce Logistics While Navigating Financial and Compliance Headwinds
Armlogi has expanded its operational footprint through workforce growth and key e-commerce partnerships, but its financial constraints, internal control weaknesses, and Nasdaq compliance risks present a complex road ahead.
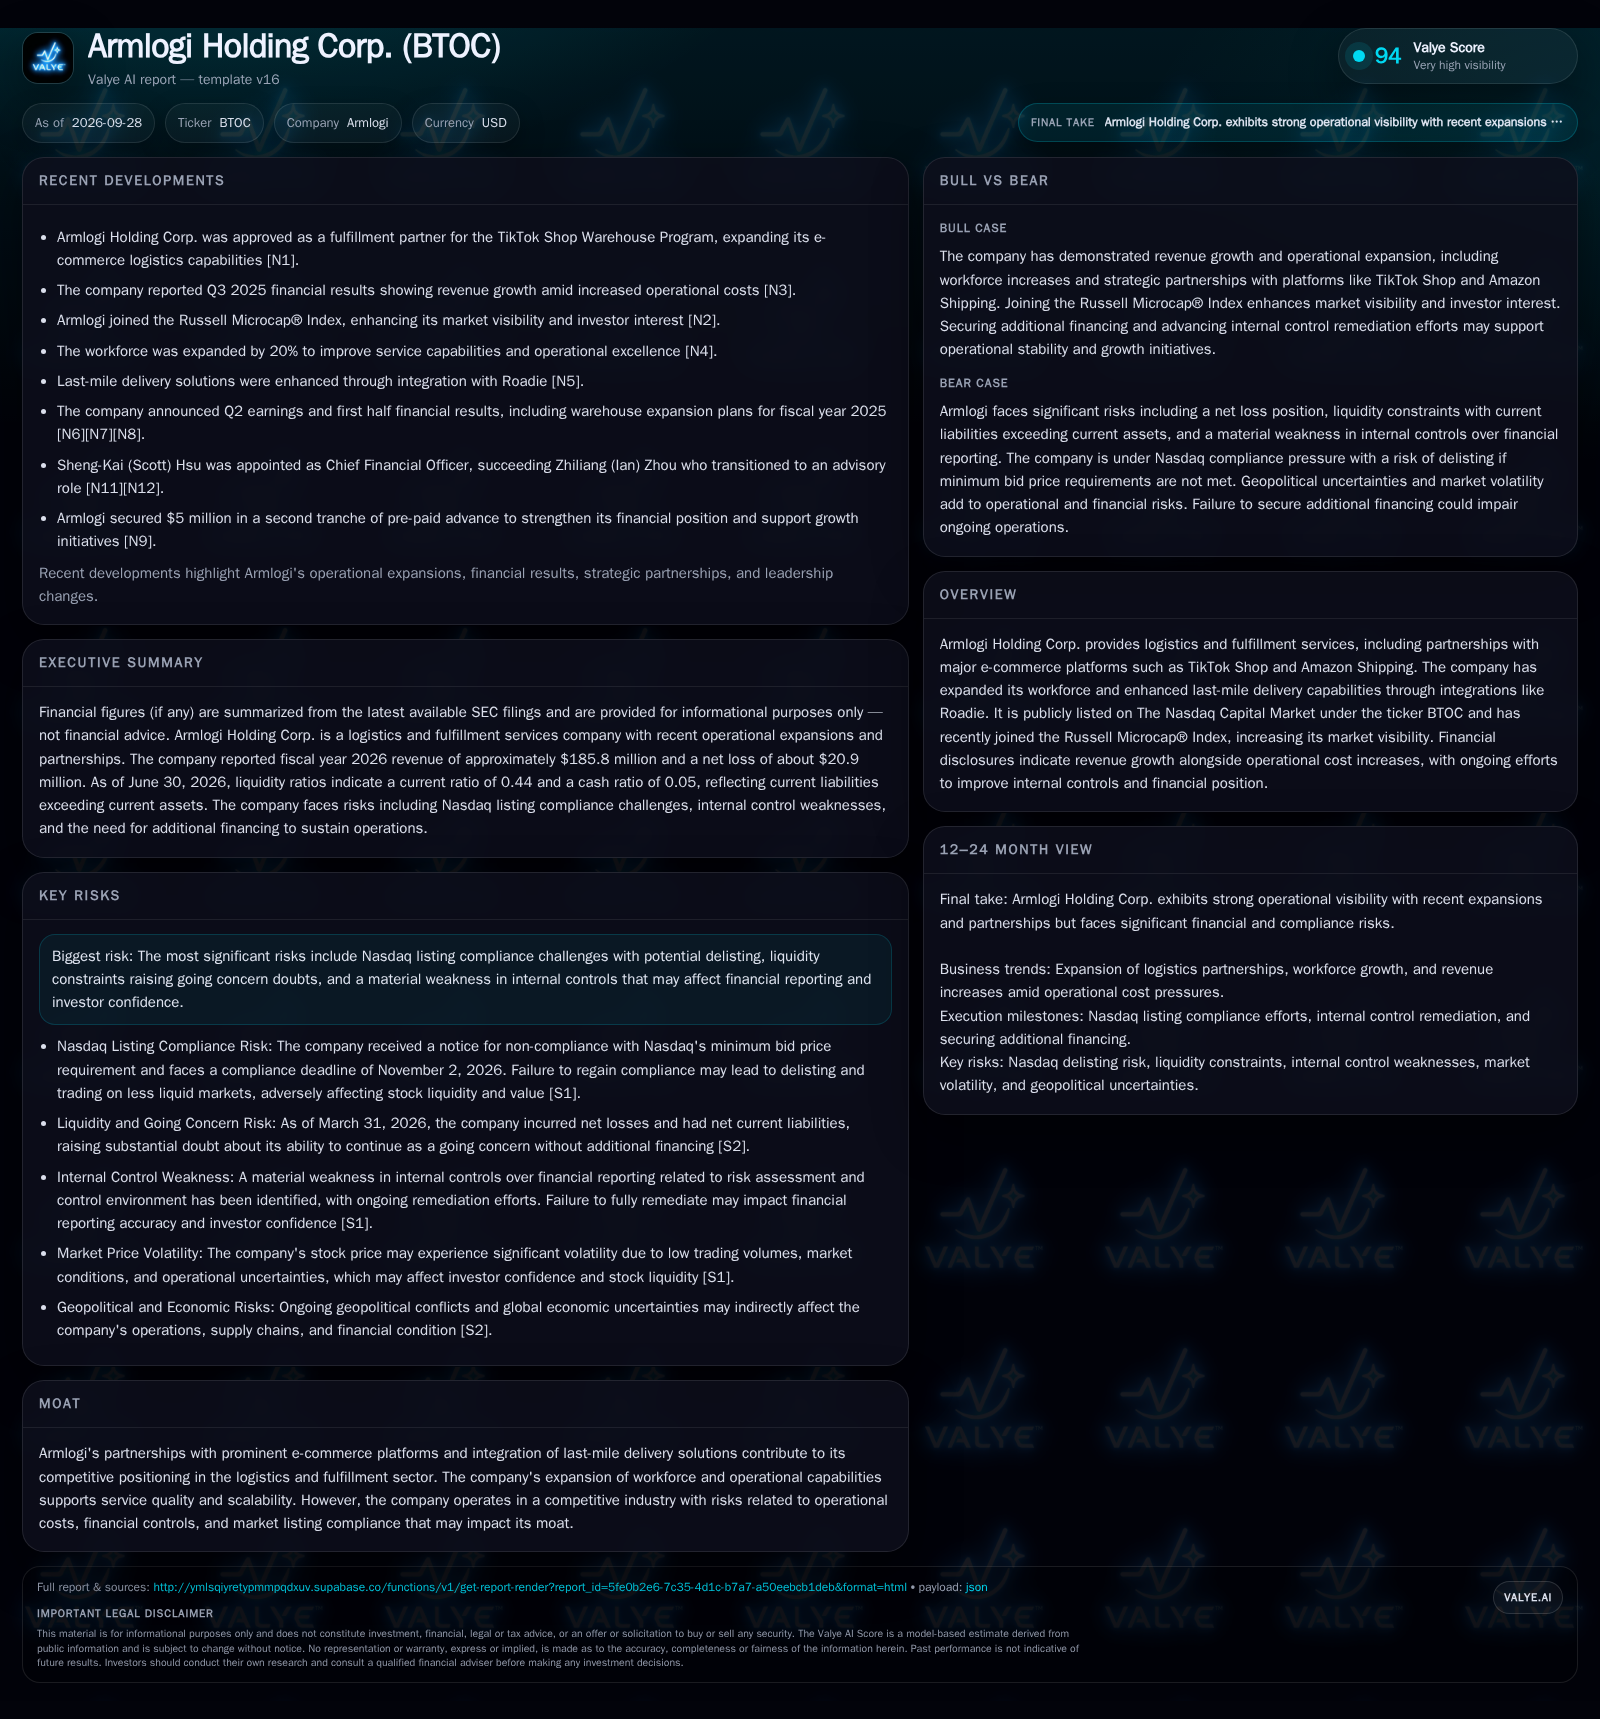
Armlogi Holding Corp. reported $185.8 million in revenue and a net loss of $20.9 million for fiscal 2026, with significant increases in operational costs and a current ratio of just 0.44. [S1] [N1] [N2] [N3] [N4]
Armlogi Holding Corp. is attempting to scale its logistics and fulfillment business at the intersection of surging e-commerce demand and intensifying competition. With partnerships secured with major platforms like TikTok Shop and Amazon Shipping, and a 20% workforce expansion, Armlogi has made strategic moves to boost its service capacity and reach. The looming risk of Nasdaq delisting due to bid price non-compliance further clouds the outlook, making the company’s ability to secure additional funding and execute operational improvements essential to its future.
Recent Expansions Collide with Financial and Compliance Pressure
Armlogi reported $185.8 million in revenue for fiscal 2026 but recorded a net loss of $20.9 million, underscoring that top-line growth has not translated into profitability. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. This signals acute liquidity stress and an urgent need for additional financing. [S1]
Operationally, Armlogi has expanded its workforce by 20% and reinforced its logistics platform through last-mile integrations and partnerships with major e-commerce players like TikTok Shop and Amazon Shipping, aiming to capture more volume in a rapidly growing market. [N1] [N4] [N5]
On the capital markets front, Armlogi was transferred from The Nasdaq Global Market to The Nasdaq Capital Market in May 2026 due to bid price non-compliance, with a compliance deadline of November 2, 2026. The risk of delisting adds pressure at a time when investor confidence is already challenged by a material weakness in internal controls over financial reporting. [S1]
E-Commerce Fulfillment: Scale Ambitions Meet Margin Compression
Armlogi’s business model is built around logistics and fulfillment services, leveraging partnerships with high-volume e-commerce platforms to drive throughput and warehouse utilization. The core economics in this industry are typically volume-driven, with gross margins sensitive to labor, transportation, and facility costs. Fixed costs (warehousing, IT infrastructure, and managerial overhead) are high, while variable costs scale with shipment volume and last-mile delivery complexity.
Recent workforce expansion and operational investments suggest Armlogi is attempting to build scale and service quality, which are prerequisites for winning and retaining major platform partnerships. However, the company’s reported net loss and increased operational expenses indicate margin compression, likely stemming from competitive pricing, rising labor and transportation costs, and the upfront investment required to meet large platform SLAs (service-level agreements).
Capital requirements remain significant. The $5 million pre-paid advance provides some breathing room but is not sufficient to fundamentally alter the company’s liquidity profile. To achieve operating leverage, Armlogi must increase order volume and revenue per warehouse without proportionally increasing costs—a challenge in a sector where customer bargaining power and price sensitivity can erode margins quickly.
Strategic Partnerships and Scale: Competitive Edge or Commodity Trap?
Armlogi’s partnerships with TikTok Shop and Amazon Shipping provide access to large e-commerce flows, which is crucial for volume aggregation and network optimization. The integration of last-mile delivery solutions via Roadie potentially differentiates Armlogi by offering more flexible delivery options, but such integrations are rapidly becoming table stakes in the sector. [N1] [N5]
The logistics and fulfillment industry is intensely competitive, with established players ranging from multinational 3PLs to asset-light digital platforms. Barriers to entry are moderate—requiring capital, technology, and a trusted track record, but service is often commoditized, and switching costs for large e-commerce partners are typically low unless differentiated by reliability, technology integration, or specialized services.
Armlogi’s ability to scale and maintain service levels while containing costs is central to its competitive position. However, persistent operational losses and unresolved internal control issues may impair its ability to negotiate favorable contract terms or win long-term, sticky relationships—especially if competitors offer greater financial stability or proprietary logistics technology.
Volume Growth and Platform Stickiness Could Transform Economics
If Armlogi successfully leverages its partnerships with TikTok Shop and Amazon Shipping to capture a significantly higher share of e-commerce fulfillment volume, it could achieve the scale necessary for operating leverage. Increased throughput would allow fixed costs to be spread over more orders, potentially improving margins even in a competitive pricing environment.
A scenario where operational investments (such as the 20% workforce expansion and last-mile integrations) result in higher service reliability and customer satisfaction could lead to recurring, multi-year contracts or preferred vendor status with major platforms. This would enhance revenue visibility and possibly could support premium pricing for differentiated service levels.
Evidence that would confirm this scenario includes sustained double-digit revenue growth, improving gross and operating margins, customer concentration shifting toward large platform partners with multi-year commitments, and successful remediation of internal control weaknesses, restoring investor confidence.
Balancing Growth Initiatives with Persistent Margin and Liquidity Constraints
The most plausible outcome is that Armlogi continues to grow its revenue base through incremental gains in e-commerce volume, but margin improvement lags due to ongoing competitive pricing and rising operational costs. The company may secure additional short-term financing or working capital solutions but will likely remain under liquidity pressure unless it can materially improve its cost structure or negotiate higher-margin contracts.
Operational improvements may gradually address internal control weaknesses, but a full turnaround in financial reporting quality and investor confidence could take multiple quarters. The risk of Nasdaq delisting remains a persistent overhang unless the stock price recovers or the company executes a reverse split or other compliance action.
Confirmation of this scenario would come from moderate revenue growth, continued net losses (albeit improving), partial remediation of internal controls, and periodic but not transformative capital raises. Falsification would occur if margin improvement accelerates sharply or if the company is unable to access needed financing.
Liquidity Crunch and Compliance Failures Trigger Strategic Setbacks
Should Armlogi fail to secure additional financing or experience further deterioration in its current ratio, it may be forced to curtail operational investments, delay expansion, or even divest assets to raise cash. Acute liquidity stress could result in missed payments to suppliers or employees, damaging its reputation with both customers and partners.
If the company does not remediate its internal control weaknesses, it risks continued financial reporting errors or regulatory scrutiny, further eroding investor trust. Failure to regain Nasdaq compliance could lead to delisting, reducing access to capital markets and limiting institutional investor participation.
Confirmation of this scenario would be signaled by further increases in net losses, a declining cash balance, inability to raise new funds, customer or partner defections, or a formal delisting announcement.
Data Points That Will Determine Armlogi’s Ability to Convert Scale Into Sustainable Value
Quarterly revenue and gross margin trends: Sustained growth and margin expansion would indicate successful scale and operational leverage.
Net cash flow from operations and changes in cash balance: These will reveal whether the business model is moving toward self-sufficiency or deepening its reliance on external financing.
Progress on remediation of internal control weaknesses: Updates here will be critical for restoring investor confidence.
Nasdaq bid price compliance status and any actions taken to regain compliance: Reverse splits, recapitalizations, or price recovery will be important signals.
Customer concentration and contract duration (if disclosed): Increasing share of revenue from major platform partners, especially under multi-year agreements, would support the upside scenario.
Operational cost structure and workforce productivity: Monitoring cost per order, employee utilization, or fulfillment center efficiency (if disclosed) could clarify whether investments are translating into improved economics.
Announcements regarding new financing, equity raises, or debt facilities: The terms and frequency of such events will clarify the company’s financial runway and negotiating leverage.
Churn or retention rates for key e-commerce partners (if disclosed): Loss of a major platform partner would be a negative inflection point for both volume and reputation.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments