
Incannex Healthcare: Progress in OSA and Anxiety, but Commercial Validation Still a Distant Hurdle
Incannex Healthcare advances its lead drug IHL-42X for obstructive sleep apnea and PSX-001 for anxiety, supported by reported liquidity position and FDA Fast Track status. The challenge remains translating clinical milestones into regulatory approval and eventual commercial traction in competitive, high-need markets.
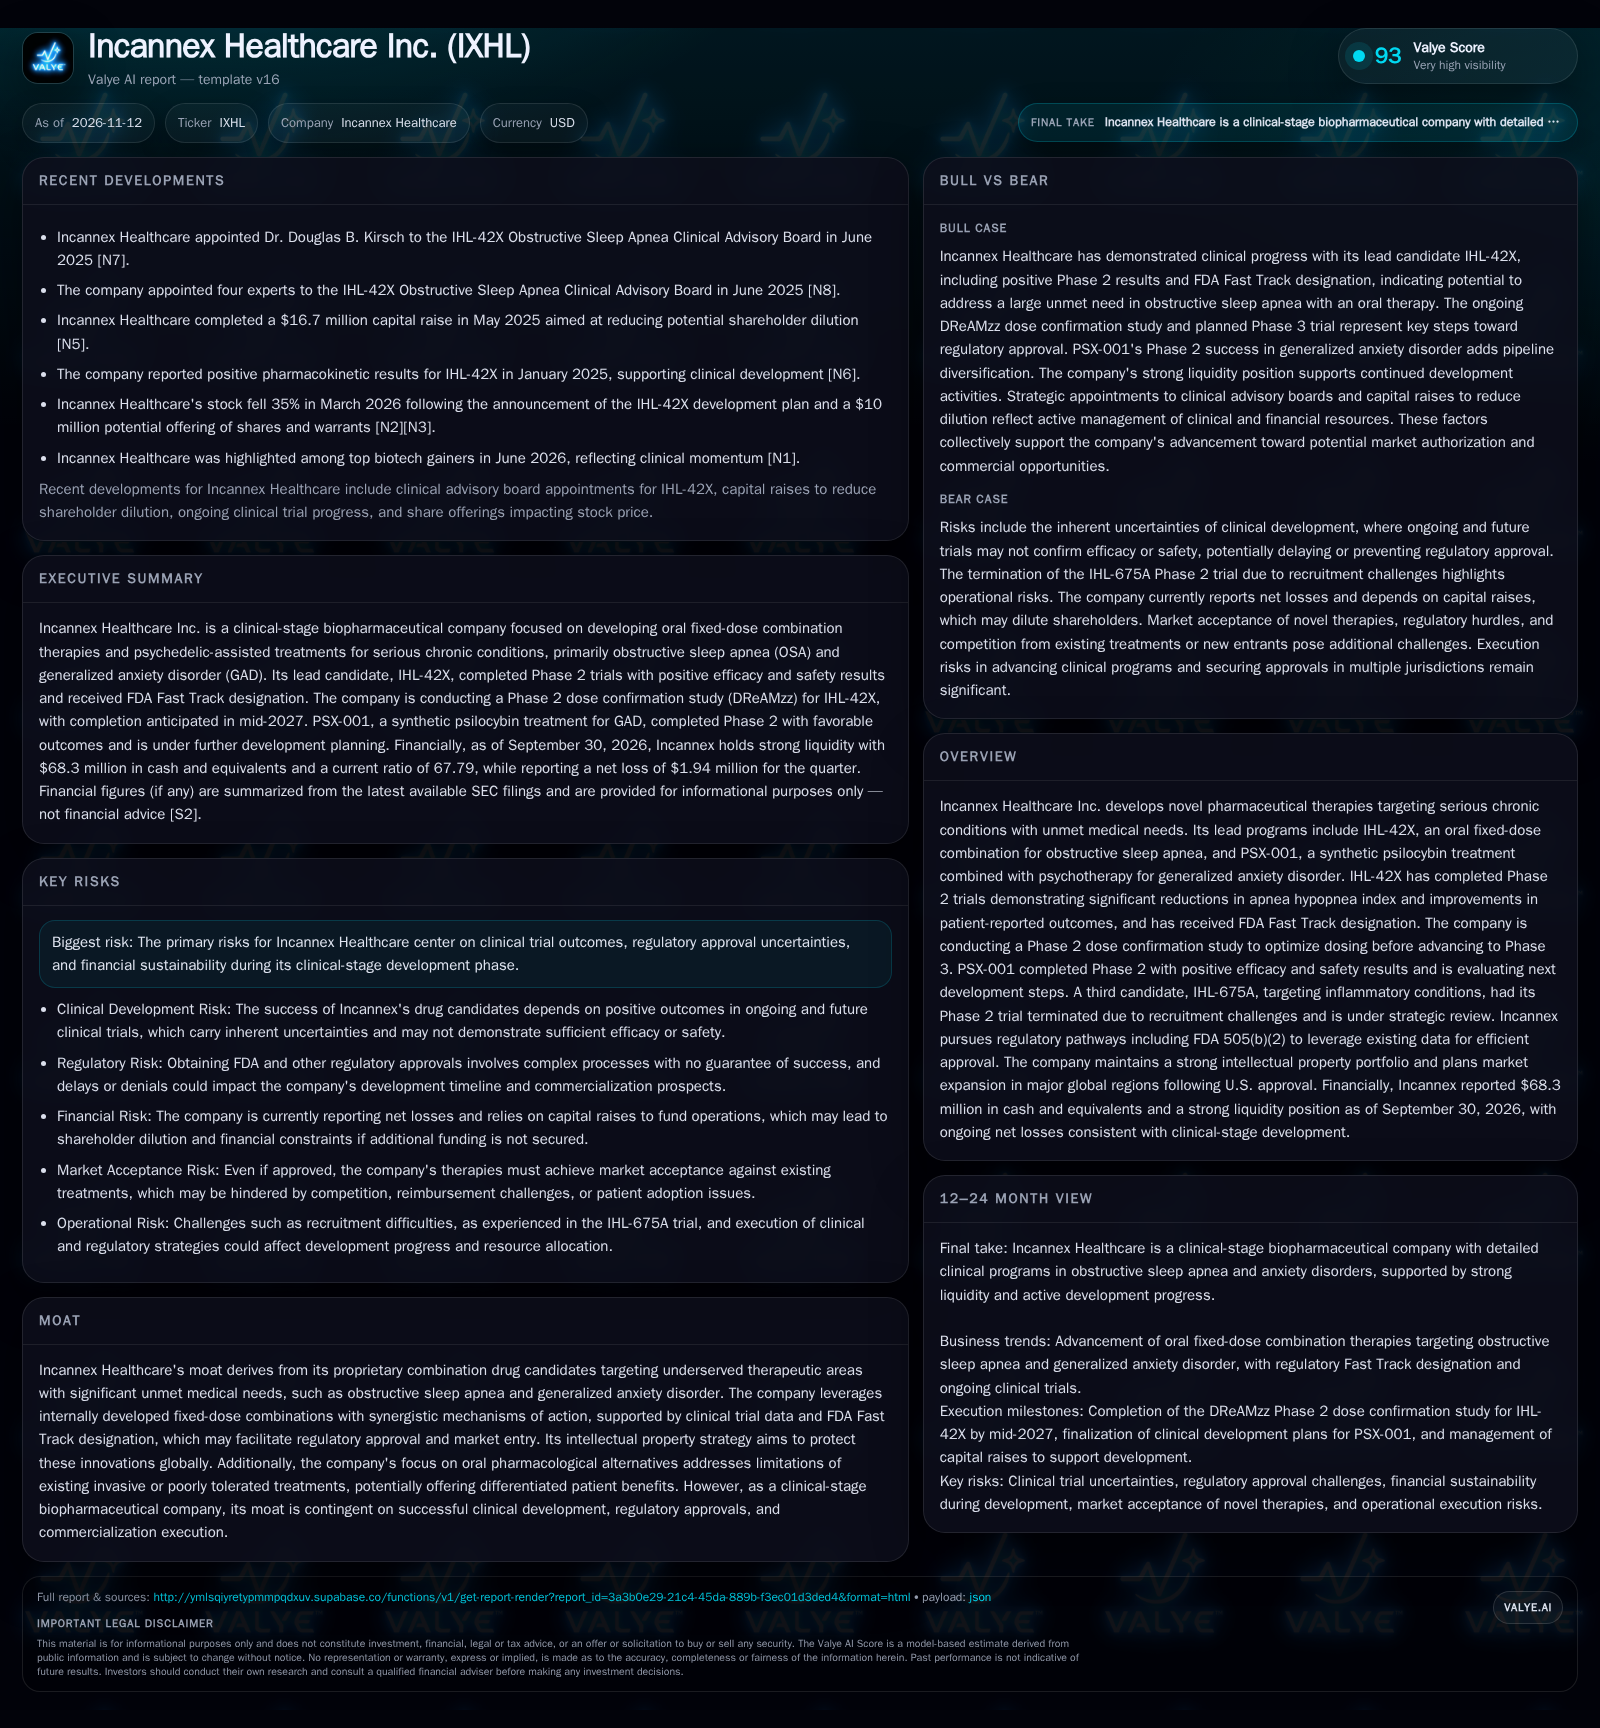
Incannex Healthcare is making clinical headway with its lead oral therapy for obstructive sleep apnea, IHL-42X, now in a crucial Phase 2 dose confirmation trial after positive earlier results and FDA Fast Track designation. Its second major asset, PSX-001 for anxiety, has also shown promise in Phase 2. With $68.3 million in cash and a low current liability load, the company can fund near-term studies, but pipeline attrition risk and the commercial realities of novel CNS therapies remain significant hurdles. The next 18 months hinge on clinical readouts, regulatory clarity, and capital stewardship [S1] [S2].
Incannex Healthcare stands at a pivotal juncture as it seeks to advance two lead assets targeting large but difficult-to-penetrate CNS and inflammatory disease markets.
Clinical Milestones, FDA Acceleration, and Capital Position Define the Near-Term Outlook
Incannex Healthcare's most material recent developments are its progress with IHL-42X for obstructive sleep apnea and PSX-001 for generalized anxiety disorder. IHL-42X completed the Phase 2 portion of the RePOSA Phase 2/3 trial in July 2025, demonstrating statistically significant reductions in apnea hypopnea index and improvements in patient-reported outcomes. The FDA granted Fast Track designation for IHL-42X in December 2025, potentially expediting its regulatory pathway. In May 2026, the DReAMzz Phase 2 dose confirmation trial was initiated, with screening starting in July and completion targeted for mid-2027. PSX-001 completed Phase 2 with significant anxiety reductions and good tolerability, and its next steps are under assessment. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S1] [S2]
Beyond the headline clinical milestones, the dynamics of patient recruitment and retention in the DReAMzz trial will be critical. Given the chronic nature of obstructive sleep apnea and the availability of established device therapies, patient willingness to enroll and remain in a trial for an oral pharmacologic alternative could be influenced by perceived efficacy, side effect profiles, and trial burden. Operational execution in trial sites, geographic diversity, and investigator experience will also materially affect timelines and data quality. Additionally, the regulatory dialogue around endpoints and trial design in this evolving therapeutic area may shape the evidentiary bar and approval likelihood, underscoring the importance of adaptive trial strategies and early FDA engagement.
The Economics of Oral Therapies for Difficult-to-Treat Chronic Conditions
Incannex's business model is predicated on developing proprietary, oral, fixed-dose combination therapies for conditions where current treatments are invasive, poorly tolerated, or insufficient. If IHL-42X secures FDA approval, its economics will depend on pricing relative to the large OSA patient pool unable or unwilling to use positive airway pressure (PAP) devices. U.S. OSA prevalence is high, but real-world uptake depends on payer reimbursement, prescriber comfort, and the magnitude of benefit over existing therapies. Fixed-dose oral drugs typically enjoy favorable gross margins if approved, but commercial-stage costs (marketing, distribution, post-marketing studies) can be substantial. The 505(b)(2) regulatory pathway may allow for faster, less costly approval by leveraging existing data, but success will hinge on demonstrating clear clinical and patient-reported advantages. [S1] [S2]
The commercial economics of oral therapies for chronic conditions like OSA also hinge on patient adherence and real-world effectiveness, which can diverge from clinical trial results. If IHL-42X demonstrates a meaningful improvement in adherence over PAP devices due to convenience or tolerability, this could translate into better health outcomes and stronger payer support. However, the fragmented nature of the OSA patient population, with varying severity and comorbidities, may necessitate tailored marketing and patient education strategies, increasing commercial complexity and costs. Moreover, pricing strategies will need to balance payer willingness with the need to recoup R&D investments, especially if the therapy is positioned as a second-line or adjunct treatment rather than a first-line option.
Navigating a Crowded OSA and CNS Therapeutics Landscape
Incannex faces a challenging competitive environment. For OSA, the standard of care remains PAP devices, but adherence rates are poor, leaving a substantial addressable market for alternatives. Incannex's IHL-42X aims to fill this gap with a non-invasive, oral option. However, any new entrant must overcome entrenched provider and payer habits, as well as competition from other device-based and pharmacological approaches under development. In the anxiety and psychiatric disorder space, PSX-001 is among several psychedelic-based therapies in clinical development, competing with both generic SSRIs and new modalities from well-capitalized biotech and pharma players. Incannex’s potential advantage lies in targeting populations underserved by current options and leveraging fixed-dose combinations for differentiated efficacy or tolerability. Intellectual property breadth and regulatory designations (like Fast Track) offer some defensibility, but ultimate success will depend on demonstrating meaningful, durable clinical benefits and navigating complex reimbursement landscapes.
If Clinical and Regulatory Momentum Translate, a New Standard for OSA Could Emerge
In the bull case, IHL-42X’s ongoing DReAMzz trial confirms optimal dosing and strong efficacy/safety, leading to successful Phase 3 outcomes and FDA approval under Fast Track. Payers recognize the value for OSA patients non-compliant with PAP, enabling favorable reimbursement and rapid uptake. Incannex leverages its regulatory head start to expand into other major markets (EU, UK, Japan, Australia, Canada), and its intellectual property portfolio fends off generic competition. PSX-001 advances into late-stage development, potentially establishing a differentiated position in the emerging psychedelic therapy landscape for GAD. Evidence supporting this scenario would include clear, statistically robust clinical readouts, positive regulatory meetings, early payer engagement, and minimal dilution from future capital raises.
Clinical Progress Continues, But Commercial Validation Remains Several Years Away
The most plausible scenario is that Incannex continues to advance IHL-42X through its dose confirmation and subsequent pivotal trials, with mixed but generally positive data supporting further development. Regulatory feedback is constructive but requires additional studies or data, leading to a slow but steady progression toward potential approval. PSX-001’s next steps are clarified, but timelines extend as the company seeks optimal trial design and partnerships. Commercial traction remains unproven, and payer or prescriber skepticism delays widespread adoption even if approval is eventually secured. Confirmation of this scenario would come from incremental clinical data, ongoing regulatory engagement, and measured capital deployment, while delays in trial enrollment, ambiguous efficacy, or funding constraints would challenge it.
Clinical Setbacks or Regulatory Barriers Expose Financial and Pipeline Vulnerabilities
In the downside case, the DReAMzz dose confirmation trial or subsequent pivotal studies for IHL-42X fail to replicate earlier positive results, or safety concerns arise. Regulatory agencies could require additional, costly studies or deny approval, eroding the perceived value of the pipeline. Market or payer skepticism about novel fixed-dose cannabinoid combinations limits commercial potential, even if approved. PSX-001’s development stalls due to competition, regulatory uncertainty, or insufficient differentiation. In this scenario, Incannex's cash burn accelerates, necessitating dilutive financings or program cuts, as seen with the terminated IHL-675A trial. Evidence supporting this scenario would include negative or equivocal clinical data, regulatory setbacks, unfavorable capital markets, or difficulty enrolling patients in key trials.
Milestones and Evidence That Will Validate or Challenge Incannex’s Long-Term Value Proposition
Enrollment pace and completion of the DReAMzz Phase 2 dose confirmation trial for IHL-42X—any delays or early terminations would signal operational or clinical setbacks.
Topline efficacy and safety data from DReAMzz and subsequent pivotal studies—robust, statistically significant improvements in AHI and patient-reported outcomes would support the investment case.
Regulatory feedback from the FDA and other agencies, especially regarding the sufficiency of the Fast Track pathway and any requirements for additional studies.
Progress on payer engagement and early signals of reimbursement willingness for IHL-42X—if disclosed, coverage decisions or formulary placements would be key.
Clarity on the PSX-001 development plan and any advancement into Phase 3 or partnership announcements.
Cash burn rate and timing/structure of future capital raises, including dilution and access to non-dilutive funding.
Status of intellectual property filings, particularly any new patents or legal challenges related to the fixed-dose combinations.
Updates on pipeline prioritization and resource allocation following the terminated IHL-675A trial—evidence of disciplined portfolio management would help test the thesis.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments