
Locafy’s AI SEO Drive: Momentum, Partnerships, and Profitability Pressures
Locafy Ltd reported 23% revenue growth for fiscal 2026, supported by the launch of new AI-powered SEO products and strategic partnerships in the U.S.
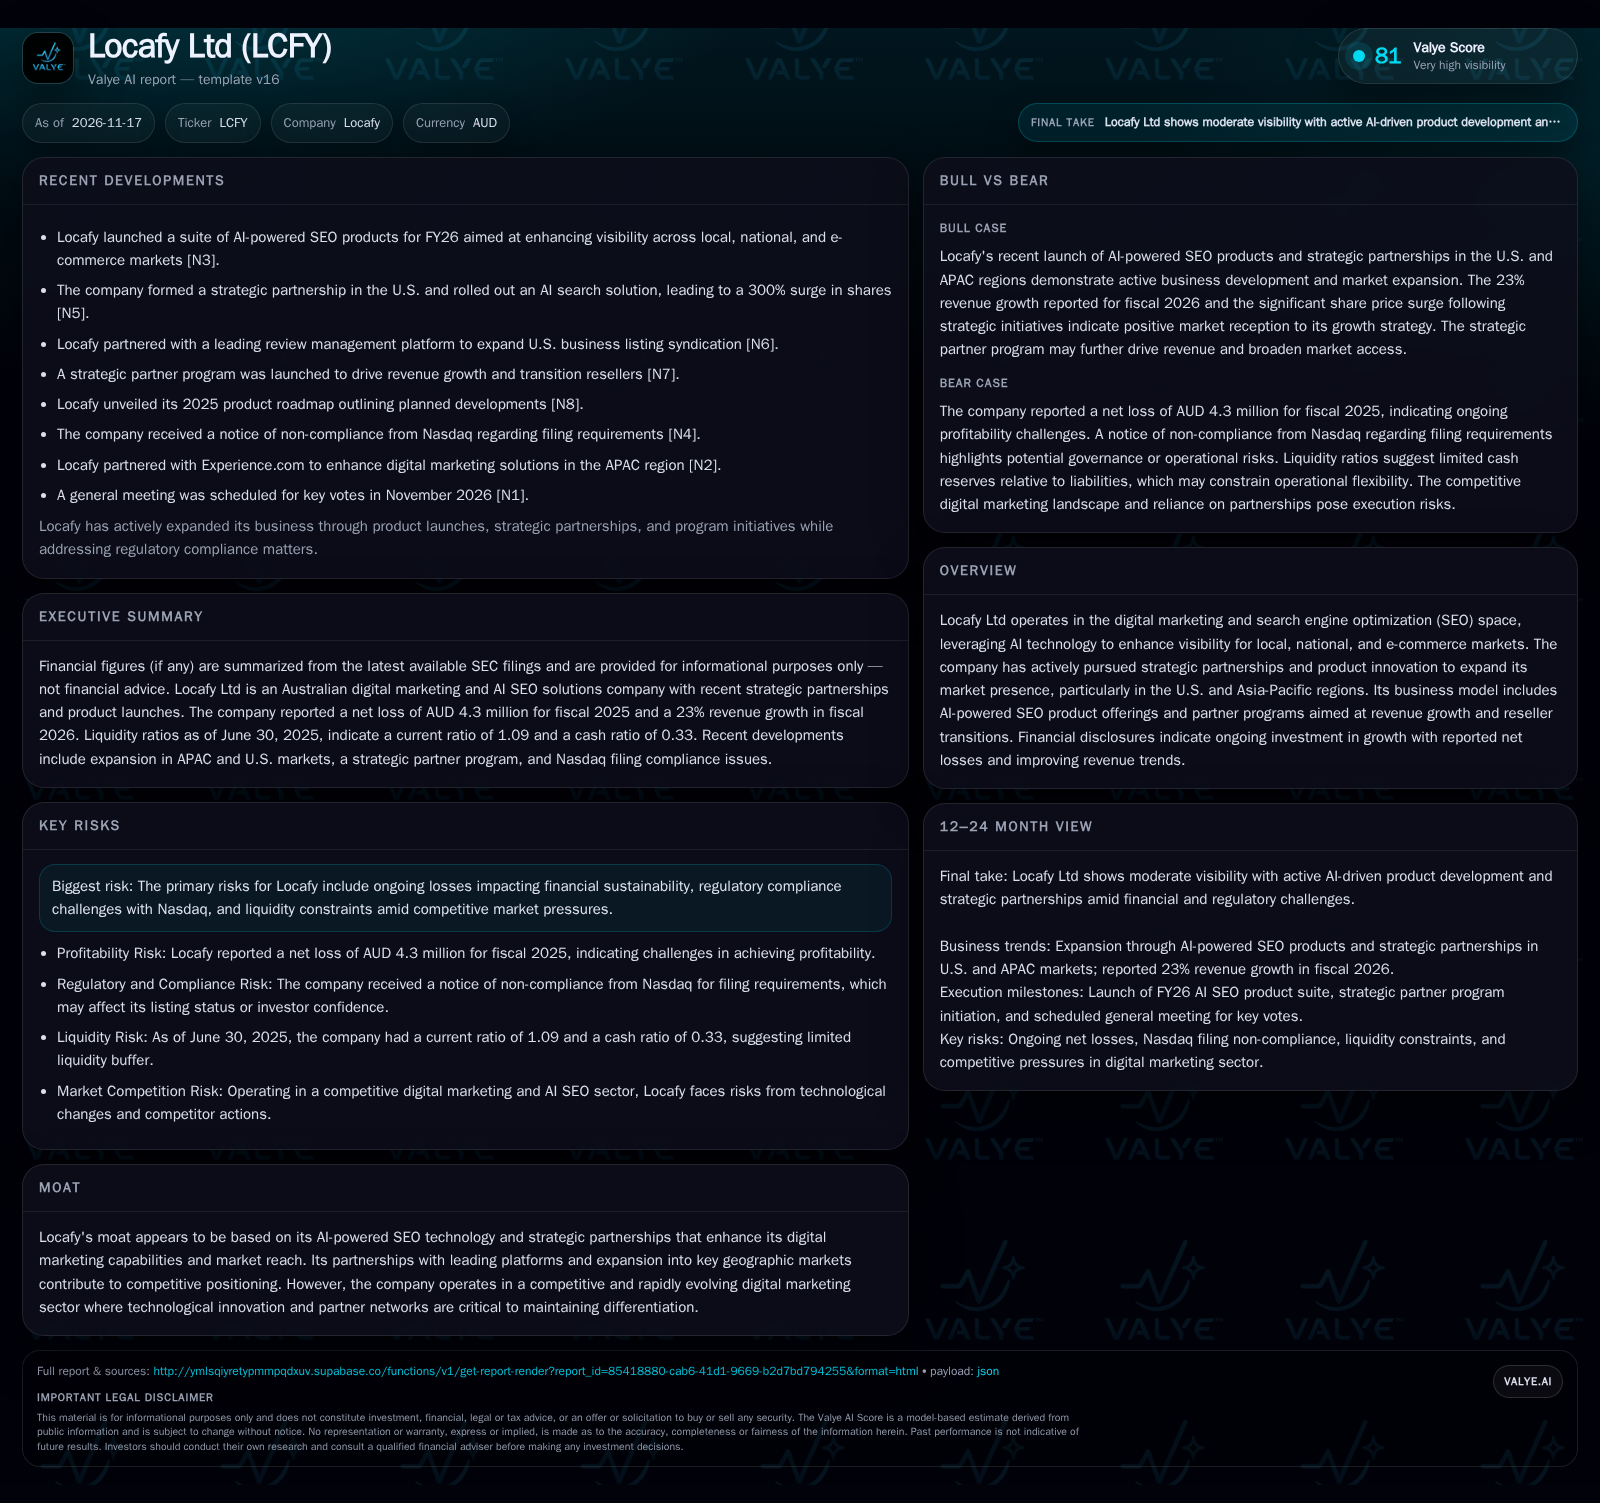
Locafy Ltd reported 23% revenue growth for fiscal 2026, supported by the launch of new AI-powered SEO products and strategic partnerships in the U.S. and APAC. Despite this, the company remains unprofitable, with a net loss of AUD 4.3 million in fiscal 2025, reported cash balance, and a recent Nasdaq non-compliance notice. Locafy’s future hinges on converting innovation and partner momentum into durable, profitable business at scale amid intense competition and operational risks. [S1] [S2] [N3] [N4] [N5] [N6] [N7]
Locafy Ltd is making bold moves in digital marketing and AI-powered SEO, aiming to carve out a niche as a technology-forward partner for businesses seeking visibility in an increasingly crowded online landscape. Its recent AI product launches and expansion into strategic partnerships have produced rapid revenue growth and attracted market attention, but profitability remains elusive. With regulatory compliance issues and reported liquidity position on the balance sheet, Locafy’s next phase will test whether innovation and commercial relationships can be translated into a durable, profitable business model.
Locafy’s Recent Momentum Fueled by Partnerships and Regulatory Demands
Locafy Ltd reported 23% year-over-year revenue growth for fiscal 2026, a notable acceleration attributed to the launch of its AI-powered SEO product suite aimed at local, national, and e-commerce markets. This growth followed the rollout of strategic partnerships, particularly in the U.S. and APAC, including collaborations with review management platforms and digital marketing solutions providers. A high-profile U.S. partnership and AI search solution launch resulted in a 300% surge in Locafy’s share price, signaling enthusiastic market response to its innovation strategy. However, the company ended fiscal 2025 with a net loss of AUD 4.3 million, reflecting ongoing profitability challenges. Liquidity as of June 30, 2025, was modest: cash and cash equivalents stood at AUD 594,671, with a current ratio of 1.09 and a cash ratio of 0.33. In parallel, Locafy received a notice of non-compliance from Nasdaq for filing requirements, raising questions about governance and regulatory risk as it pursues its growth ambitions. [S1] [S2] [N3] [N4] [N5] [N6] [N7]
Breaking Down Locafy’s AI SEO Revenue Streams and Expense Profile
Locafy's revenue model is built around delivering AI-powered SEO solutions and digital marketing products to businesses aiming to enhance online visibility. The company’s growth strategy hinges on two main levers: product innovation—particularly in AI-driven automation for SEO optimization—and the cultivation of strategic distribution partnerships that expand reach and access to new customer segments. While AI automation theoretically supports gross margin improvement by reducing manual labor and increasing scalability, the actual economics depend on the level of technology differentiation, customer willingness to pay, and the structure of partner revenue sharing.
The launch of a strategic partner program suggests a move toward leveraging third-party channels to accelerate adoption and reduce direct customer acquisition costs. However, such programs often entail revenue sharing or discounted pricing, which may compress margins unless offset by higher sales volumes or upselling of premium features. The net loss recorded in fiscal 2025 indicates that operating expenses—including R&D, partnership development, and go-to-market costs—currently outpace gross profit, a common scenario for early-stage SaaS and platform companies scaling aggressively.
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. The ability to reach operating leverage—where incremental revenues translate efficiently into profits—will be crucial to shifting from growth to sustainable profitability.
How Strategic Alliances Shape Locafy’s Position in a Crowded AI SEO Market
Locafy operates in a fiercely competitive digital marketing and SEO landscape, where established SaaS providers, digital agencies, and tech platforms offer a spectrum of search optimization solutions. The company’s moat, to the extent it exists, is rooted in its proprietary AI-powered SEO technology and its network of strategic partnerships—particularly those that enable business listing syndication and integration with review management platforms. Such partnerships can accelerate customer acquisition and expand Locafy’s distribution footprint, especially in markets like the U.S. and APAC.
However, the durability of this advantage is not assured. The digital marketing sector is marked by rapid innovation cycles, low switching costs for customers, and the constant threat of technology substitution, especially as generative AI and large language models become increasingly commoditized. Larger competitors with deeper R&D budgets and established customer bases could replicate or outpace Locafy’s feature set, eroding differentiation. Furthermore, reliance on partners introduces counterparty risk and may dilute direct customer relationships, making Locafy vulnerable to changes in partner strategy or the emergence of new ecosystem gatekeepers.
Potential Impact of an Accelerated AI Flywheel on Locafy’s Growth Trajectory
In a favorable scenario, Locafy’s AI-powered SEO suite is widely adopted by its partners’ customer bases, driving high-volume sales with attractive per-customer economics. The partner program successfully transitions resellers and unlocks new distribution channels, while product innovation keeps Locafy ahead of commoditization and enables premium pricing for differentiated features. As a result, operating leverage improves: incremental revenue growth outpaces growth in operating expenses, bringing the company to break-even and then to sustained profitability.
Confirmation of this scenario would come from continued robust revenue growth (sustained or accelerating beyond the recent 23%), a narrowing net loss or transition to positive operating cash flow, and public disclosures of large-scale partner wins or customer adoption metrics. Additional evidence would include announcements of upselling higher-value product tiers and improvement in gross margin, suggesting that AI automation is translating into real cost efficiencies and pricing power.
Balancing Growth Ambitions with Cost Controls and Execution Realities
The most plausible path ahead is one in which Locafy maintains mid-to-high double-digit revenue growth, fueled by ongoing product launches and incremental partner expansion. However, growth is offset by persistent costs associated with R&D, partnership management, and sales enablement, keeping the company unprofitable in the near term. The liquidity position requires careful cash management, and further capital raises may be needed to bridge to profitability if operating leverage remains elusive.
This scenario would be confirmed by continued revenue growth with net losses gradually narrowing but not yet reaching break-even. Partner announcements and new product launches would continue, but without a step-change in gross margin or cash flow. Falsification would come from a sudden deceleration in revenue growth, material partner defections, or an inability to resolve Nasdaq compliance issues, which could undermine investor confidence and access to capital.
Liquidity Constraints and Compliance Challenges Could Reshape Locafy’s Outlook
A negative scenario unfolds if Locafy’s revenue momentum stalls—possibly due to competitive encroachment, partner churn, or failure to deliver on promised AI capabilities. In this case, high fixed costs and ongoing operating losses would rapidly erode the reported liquidity position buffer, forcing Locafy to seek dilutive financings or cut back on growth investments. Failure to regain Nasdaq compliance could further restrict access to public capital markets, compounding financial pressure and potentially leading to a strategic retreat or restructuring.
Evidence for this scenario would include flat or declining revenues, widening net losses, a deteriorating current ratio, or the announcement of layoffs, product discontinuations, or unsuccessful capital raises. Loss of key partners or negative customer feedback on product efficacy would also support the downside case.
Critical Milestones to Gauge the Sustainability of Locafy’s Expansion Efforts
Quarterly and annual revenue growth rates, especially in the context of new product launches and partner program performance.
Gross margin trends and disclosures on the cost structure of AI-powered SEO products—if disclosed, this would clarify whether automation is driving economic efficiency.
Operating cash flow and net loss progression, indicating whether the business is moving toward break-even or burning cash at an accelerating rate.
Updates on Nasdaq compliance status, as ongoing listing risk could impact investor confidence and capital access.
Announcements of major partner wins, reseller transitions, or integration deals, demonstrating the effectiveness of the partner program.
Customer adoption metrics, retention rates, and reported customer outcomes—data that would substantiate claims of product-market fit and stickiness.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments