
SPACSphere Acquisition Corp.: Mobilewalla Merger Progress and the Mechanics of Value Creation in the SPAC Lifecycle
SPACSphere Acquisition Corp. is advancing toward a high-profile business combination with Mobilewalla, a provider of vertical agentic AI solutions. With its trust capital from a $172.5 million IPO and a defined regulatory timeline, SPACSphere’s outcome now pivots on deal execution, shareholder approval, and the post-merger performance of a data-driven AI target in a competitive tech landscape.
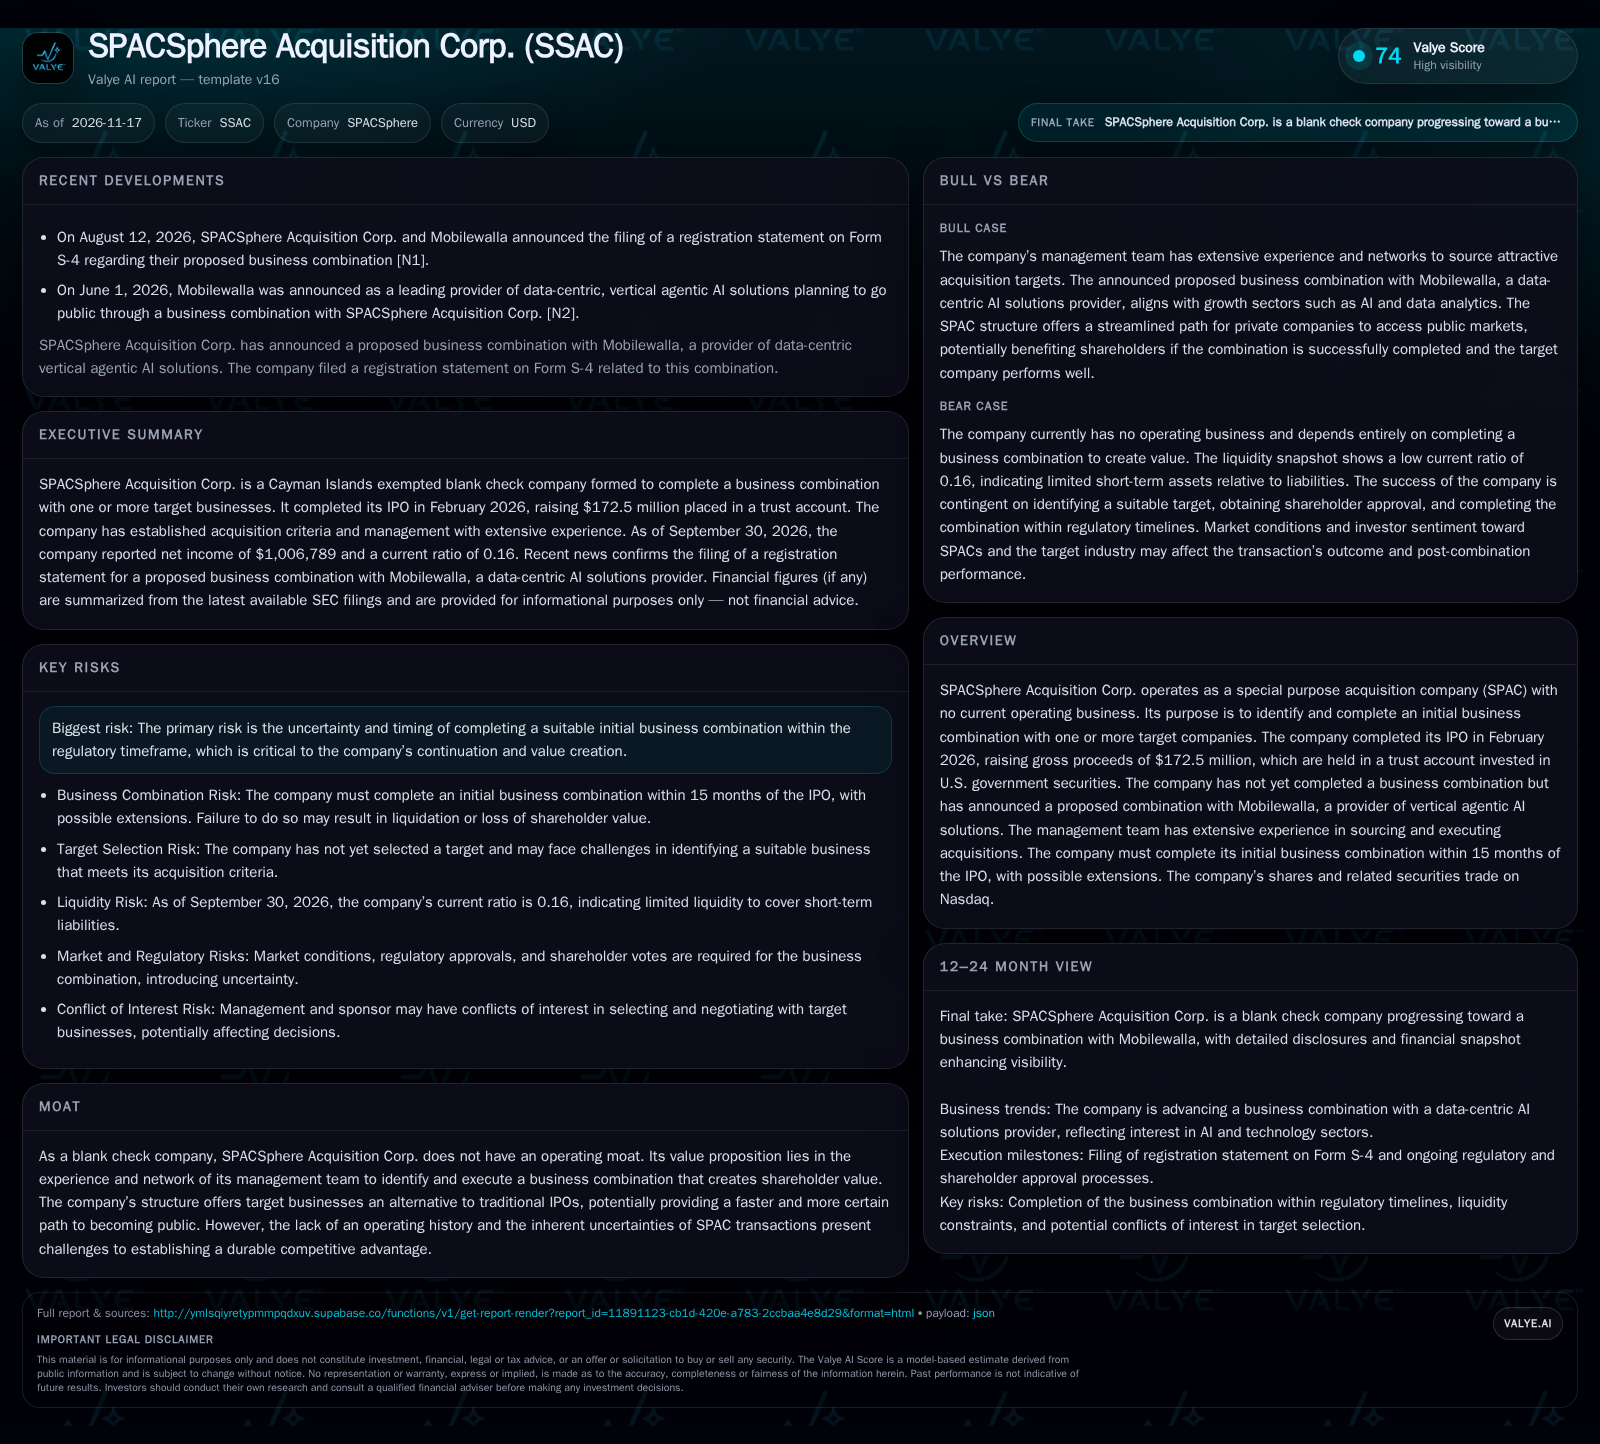
SPACSphere Acquisition Corp., a blank check company with $172.5 million raised, is progressing toward a merger with Mobilewalla, a data-centric AI solutions provider. The pending transaction, subject to regulatory and shareholder approval, will test the ability of the management team to deliver value within a tight timeframe and amid sectoral and market complexity. The success of the business combination—and the subsequent integration—will determine whether SPACSphere can transition from a cash shell to a value-creating public company in the AI sector.
SPACSphere Acquisition Corp. exemplifies the classic SPAC lifecycle: a Cayman Islands entity with no operating business, it raised $172.5 million in early 2026 to pursue a merger or acquisition. Now, with a proposed business combination with Mobilewalla—a data-centric, vertical agentic AI provider—moving through the regulatory pipeline, the company stands at a pivotal juncture. The outcome will hinge on the closing and integration of the Mobilewalla deal, the ability to deliver shareholder value post-merger, and the management team’s execution in an increasingly competitive AI landscape. For investors and stakeholders, the next few quarters will reveal whether SPACSphere’s blank-check structure can successfully transition into a sustainable, growth-oriented public company.
SPACSphere’s Current Status: Deal Progress, Trust Capital, and Regulatory Clock
SPACSphere Acquisition Corp. remains a blank check company with no active operating business, having raised $172.5 million through its February 2026 IPO. This capital is held in a trust account invested in U.S. government securities, isolated from day-to-day operations and reserved for a business combination or return to shareholders if no deal is completed [S2]. The company’s most material recent development is its signed business combination agreement with Mobilewalla, a provider specializing in vertical agentic AI solutions. A registration statement on Form S-4 was filed in August 2026 and has been amended, but has not yet been declared effective by the SEC [N1] [S2].
As of September 30, 2026, SPACSphere’s operating liquidity appears constrained, with current assets of $218,622 against current liabilities of $1,374,184, resulting in a current ratio of 0.16 [S2]. This reflects the typical SPAC structure, where trust assets are segregated, and operational funds are limited. The company must close the Mobilewalla deal within 15 months of IPO—by May 2027—unless it secures an extension, or else face the risk of liquidation [S2].
How Value Could Be Created: SPAC Economics, Dilution, and the Post-Merger Equation
SPACSphere’s economic model is fundamentally transactional: its raison d’être is to identify, negotiate, and consummate a merger with an operating business, using the capital raised in its IPO. The trust fund, minus redemptions and transaction costs, is intended as growth capital for the target (Mobilewalla), but the economics are shaped by several key variables. First, dilution is a central issue: upon closing, public shareholders’ equity will be diluted by sponsor shares, warrants, rights, and any additional shares issued to meet the deal’s valuation or backstop redemptions [S2].
Post-merger, the combined company’s economics will depend on Mobilewalla’s revenue growth, gross margins, and ability to scale AI-driven solutions profitably. AI and data analytics businesses often feature high upfront development costs but can exhibit significant operating leverage if software and data products are successfully scaled. However, customer acquisition costs, R&D intensity, and competitive pricing pressure can compress margins. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity.
Assessing Strategic Edge: Mobilewalla’s Prospects in the Data-Centric AI Arena
SPACSphere’s competitive position is entirely contingent on Mobilewalla’s ability to carve out a durable niche in the AI and data analytics market. This sector is crowded with both established tech giants and nimble startups, all vying for enterprise and vertical-specific AI contracts. Mobilewalla’s positioning as a provider of ‘vertical agentic AI solutions’ suggests a focus on tailored, industry-specific data products, which could offer an edge if the company can demonstrate superior data quality, domain expertise, or integration capabilities [N2].
However, barriers to entry in AI/data analytics are moderate: while proprietary data and models can be a moat, switching costs for customers are often limited unless deep integrations or regulatory compliance are required. The competitive environment is further shaped by pricing pressure, rapid technological evolution, and the need for continuous innovation. SPACSphere’s management team, with experience in deal sourcing and execution, may provide initial strategic direction, but long-term advantage will depend on Mobilewalla’s ability to differentiate and retain customers in a fast-moving market.
What Would Drive Outperformance: Seamless Deal Close and AI Growth Exceeding Expectations
The most favorable scenario for SPACSphere shareholders is a smooth completion of the Mobilewalla transaction, minimal redemptions, and a post-merger period marked by accelerating revenue, high gross margins, and sticky customer relationships for Mobilewalla’s AI solutions. If Mobilewalla can quickly demonstrate strong customer adoption in targeted verticals, deliver compelling case studies, and convert its data assets into scalable, high-margin recurring revenue, the combined entity could command a premium valuation.
Confirmation of this upside would require: (1) regulatory approval and a successful shareholder vote on the merger, (2) low redemption rates preserving most of the trust capital for growth investment, and (3) early evidence that Mobilewalla’s AI offerings gain traction in their chosen verticals—such as new customer wins, renewals, or high-profile partnerships. Falsification would occur if the deal faces regulatory delays, heavy redemptions deplete available cash, or Mobilewalla’s commercial ramp is slower than anticipated.
The Probable Path: Deal Completion with Moderate Redemptions and a Wait-and-See Post-Merger Phase
The most plausible outcome is that the Mobilewalla transaction closes within the regulatory window, but with a material portion of shares redeemed by public holders—reducing the cash delivered to Mobilewalla but still allowing the business to go public. The combined company may trade sideways initially as investors assess Mobilewalla’s ability to execute its growth plans in a competitive environment. Revenue growth may be steady but not explosive, with operating leverage building only if Mobilewalla can control acquisition costs and demonstrate retention.
Evidence against this scenario would be a failed vote, regulatory holdups, or post-close disappointment in Mobilewalla’s operating metrics.
Where Things Could Go Wrong: Deal Failure, High Redemptions, or Post-Merger Disappointment
The adverse scenario centers on one of three failure points: (1) the merger is blocked by regulatory, shareholder, or market forces, leading to SPACSphere’s liquidation and return of trust capital (minus expenses); (2) extremely high redemption rates leave Mobilewalla with insufficient capital to fund its growth, undermining the rationale for going public; or (3) the merger closes, but Mobilewalla fails to achieve commercial traction, leading to weak financial performance and share price decline.
Confirmation would come from: (1) regulatory or shareholder rejection of the transaction, (2) disclosures of trust redemptions leaving minimal net cash, or (3) early post-merger results showing slow revenue growth, high churn, or missed guidance. Any of these outcomes would likely erode value for public holders and could reinforce negative sentiment toward SPACs targeting technology sectors.
Milestones That Will Reveal Whether SPACSphere’s Transition to Public AI Platform Succeeds
Progress of the SEC review and effectiveness of the Form S-4 registration statement for the Mobilewalla merger.
Shareholder vote results and the final redemption rate, which will determine the capital available to the combined entity.
Initial quarterly earnings or business updates from Mobilewalla post-merger, including revenue growth and customer acquisition figures.
Evidence of commercial adoption—such as new contracts, partnerships, or renewals—demonstrating Mobilewalla’s competitive traction.
Updates on management or board composition, especially as the board expands from five to seven members upon deal closing.
Any regulatory, legal, or market developments that could delay, alter, or jeopardize the completion of the business combination.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments