
Sagimet Biosciences: Precision FASN Inhibition, Clinical Milestones, and the Road to MASH and Acne Commercialization
With positive Phase 2b and 3 data for its lead FASN inhibitor denifanstat, a reported cash position, and a precision medicine approach, Sagimet Biosciences is positioned at a pivotal moment. Success now hinges on upcoming pivotal trials, regulatory outcomes, and the ability to carve out a therapeutic niche in MASH and dermatology.
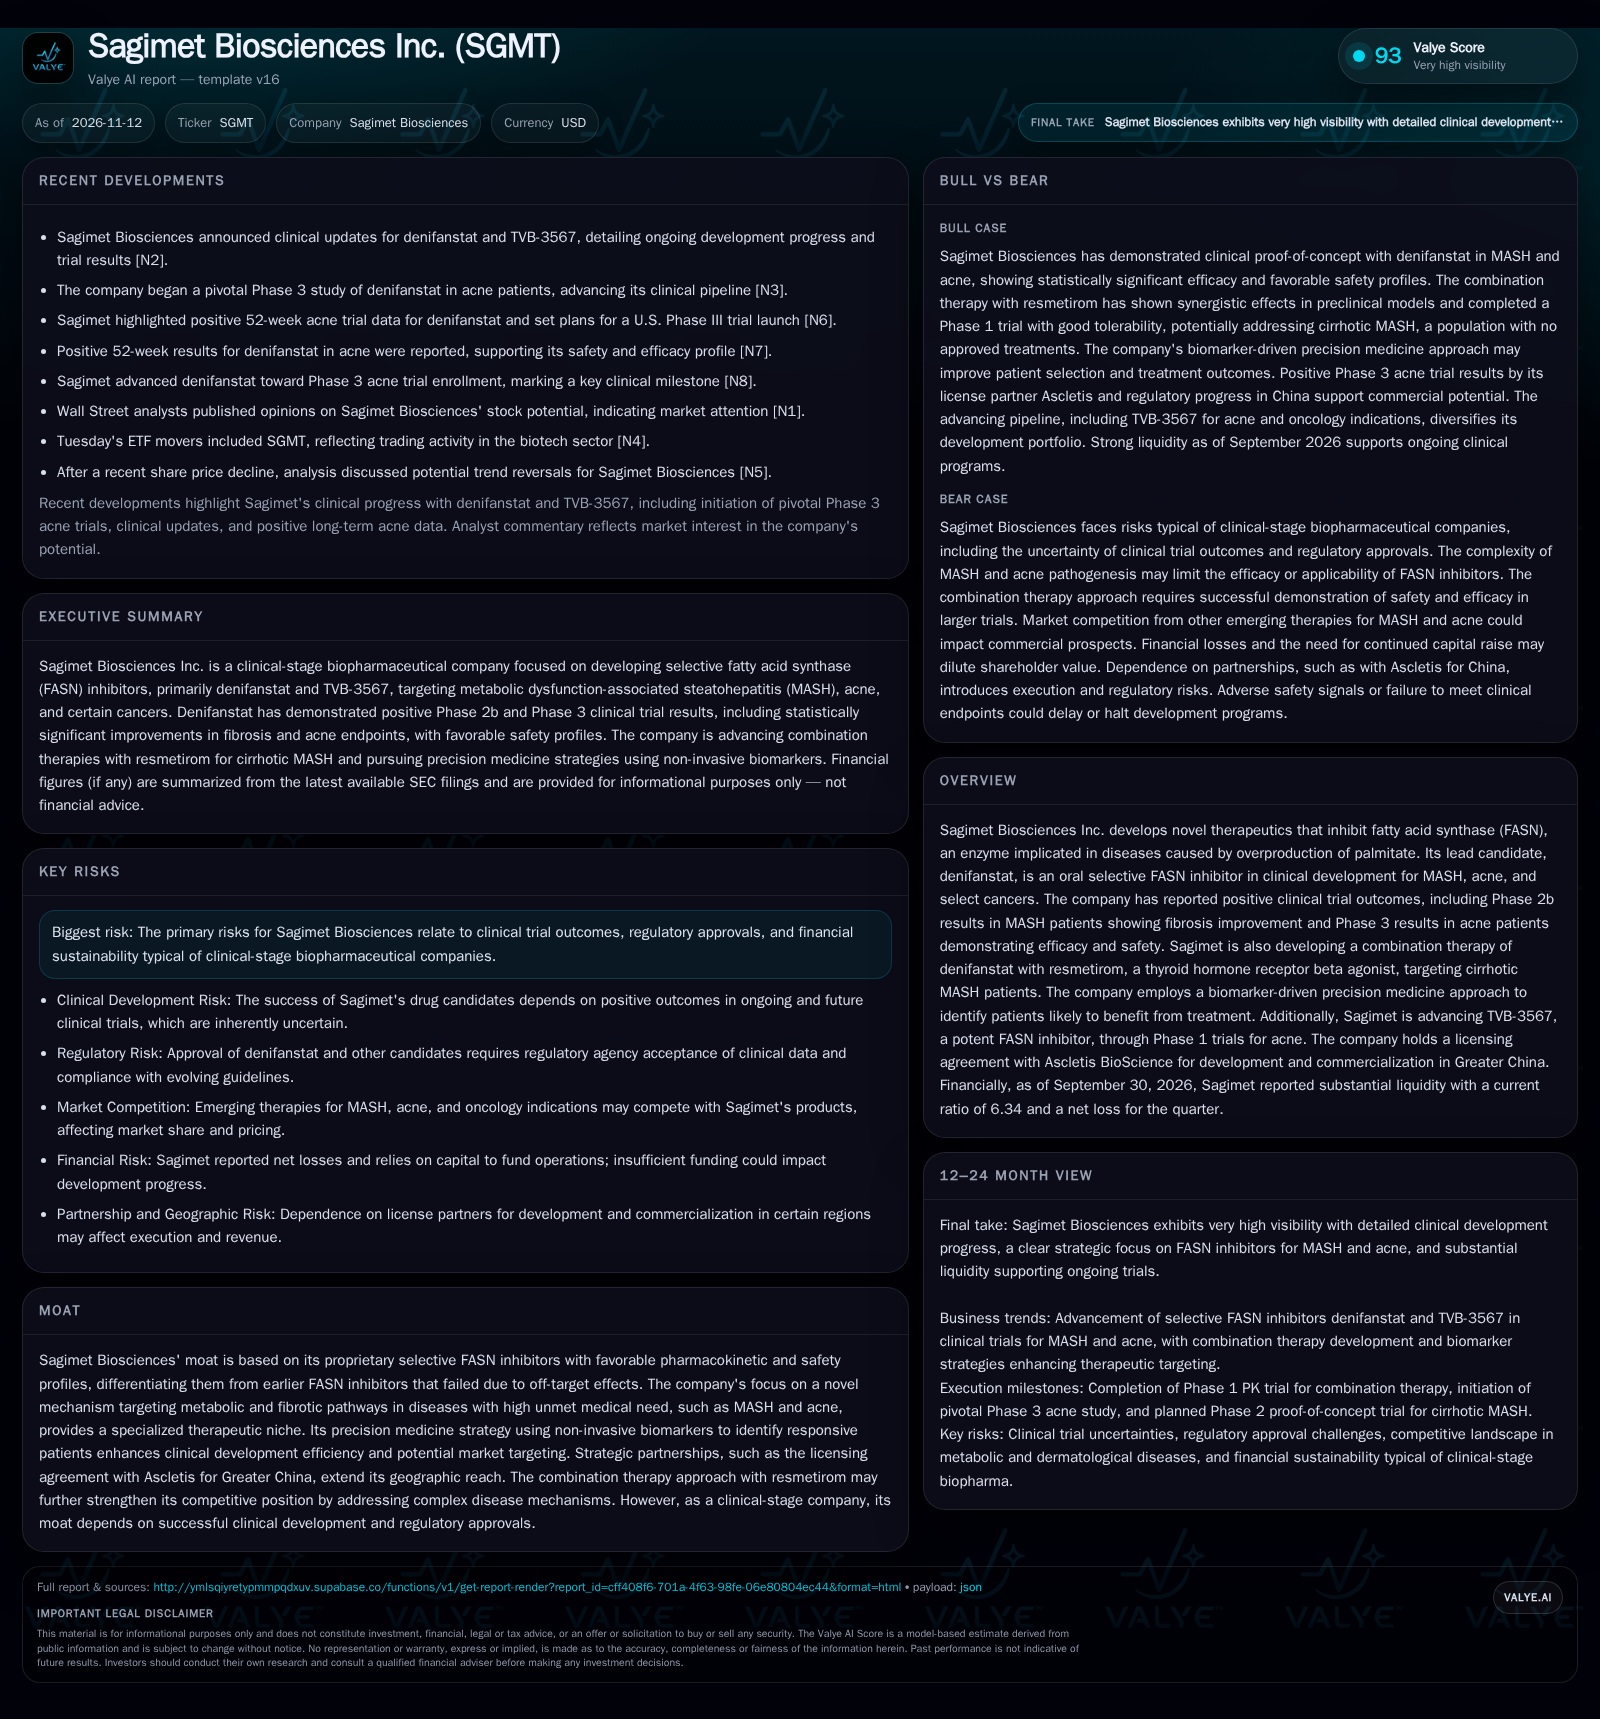
Sagimet Biosciences has advanced its lead candidate denifanstat through key efficacy and safety milestones in MASH and acne. [S2] [N3] [N7]
Sagimet Biosciences stands at a crucial inflection point in late 2026, having delivered robust clinical results for its lead FASN inhibitor denifanstat across both MASH and acne. With a cash-rich balance sheet, a biomarker-driven precision medicine approach, and an expanding pipeline, the company is preparing for pivotal trials that could define its trajectory. However, the path forward is shaped by regulatory hurdles, the need for commercial differentiation, and the inherent uncertainties of clinical-stage biotech. The coming year will test whether Sagimet can translate scientific momentum into durable market opportunity. [S2] [N3] [N7]
Recent Clinical Validation and Financial Position Shape Strategic Options
Sagimet’s lead asset, denifanstat, has demonstrated statistically significant improvements in both fibrosis and cirrhosis progression in a Phase 2b trial for MASH patients with advanced fibrosis (F2/F3), with safety results showing no treatment-related serious adverse events and a tolerable side effect profile. In parallel, denifanstat achieved positive 52-week results in moderate to severe acne, meeting primary and secondary endpoints. The company has also initiated a pivotal Phase 3 acne trial and is planning a Phase 2 proof-of-concept study for a combination therapy in cirrhotic MASH (F4) patients, targeting an area of high unmet need. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2] [N3] [N7]
How FASN Inhibition Could Translate to Revenue: Commercial Models and Leverage
Sagimet’s business model is predicated on developing oral, once-daily FASN inhibitors for high-prevalence diseases like MASH and acne, both of which offer large addressable markets but face intense competition and evolving payer expectations. If denifanstat is approved, commercial success in MASH would likely depend on capturing a share of a market projected to reach billions, but where pricing and access will hinge on demonstrating meaningful fibrosis reversal and safety in head-to-head or real-world settings. In acne, the opportunity is defined by a large patient pool and the need for differentiated efficacy and tolerability; oral therapies that avoid antibiotic resistance or isotretinoin-like side effects could command premium pricing and high adoption if supported by compelling data.
Sagimet’s economics will depend on the mix between direct commercialization (in select geographies/indications) and licensing/royalty arrangements, as exemplified by its China partnership with Ascletis. Upfront payments, milestones, and royalties provide non-dilutive cash flow but limit upside capture. Fixed costs are dominated by R&D and clinical development, with operating leverage emerging only if one or more drugs reach approval and scale. Capital needs remain substantial, as late-stage trials, regulatory filings, and pre-commercial buildout are all resource-intensive. Until approval, ongoing net losses are likely, and future funding rounds may be required unless licensing inflows or partnership payments accelerate.
Therapeutic Differentiation in a Crowded MASH and Acne Landscape
Sagimet’s selective FASN inhibition offers a mechanistic approach distinct from the metabolic, anti-inflammatory, or anti-fibrotic agents pursued by other MASH and acne developers. The company’s pharmacokinetic profile—specifically, limited blood-brain barrier penetration and high selectivity—addresses safety concerns that limited earlier FASN inhibitors. The precision medicine strategy, employing non-invasive biomarkers to identify likely responders, could improve trial efficiency and post-approval adoption, but only if these biomarkers prove robust in larger, real-world populations.
In MASH, Sagimet competes with a broad array of metabolic modulators, GLP-1 analogs, THR-beta agonists (such as Madrigal’s resmetirom), and anti-fibrotic agents at various stages of development. In acne, the landscape is dominated by established topical and oral therapies, including antibiotics, retinoids, and emerging non-antibiotic oral agents. Sagimet’s ability to differentiate will depend on head-to-head safety/efficacy data, real-world tolerability, and payer willingness to reimburse novel mechanisms. The partnership with Ascletis in China provides local regulatory and commercial expertise, but also introduces execution and revenue-sharing risk.
If Biomarker-Driven FASN Inhibition Proves Out: Expansion and Optionality
The most favorable scenario unfolds if Sagimet’s pivotal Phase 3 acne and future MASH trials confirm both the efficacy and safety seen in earlier studies, and if the company’s biomarker strategy enables superior patient selection and outcomes. Approval of denifanstat for acne in the U.S. and China could generate near-term revenue, while success in MASH—especially in the fibrosis F2/F3 or cirrhotic F4 populations—would create a high-value, differentiated product in a field with limited approved options. The combination therapy with resmetirom, if validated, could unlock an even broader range of cirrhotic patients.
This scenario would be confirmed by positive pivotal trial readouts, regulatory approvals in major markets, early commercial uptake (if disclosed), and further licensing or partnership deals. Additional pipeline progress, such as advancing TVB-3567 or successful oncology readouts, would add optionality and potential platform value.
Clinical Progress Continues but Commercialization Remains Two Steps Away
The most plausible outcome is that Sagimet advances through pivotal trials with denifanstat in both acne and MASH, but faces the typical delays, setbacks, or competitive headwinds found in clinical-stage biotech. Regulatory review processes may extend timelines, and real-world efficacy or safety signals could moderate initial enthusiasm. Market access for MASH therapies remains complex, with payers demanding robust fibrosis data and long-term outcomes, while in acne, entrenched generics and price sensitivity may slow adoption even with approval.
This scenario would be reflected in ongoing net losses, periodic capital raises, and a gradual shift from pure R&D to pre-commercial investment. Confirmation would come from continued clinical milestone achievement, but with modest or staged commercial launches and potentially slower-than-hoped revenue ramp.
Trial Setbacks or Competitive Advances Erode Value Proposition
A negative outcome could result if denifanstat fails to replicate its prior efficacy or safety in larger pivotal trials, or if unforeseen adverse events emerge. In the MASH space, rapid progress by competitors—such as new approvals for GLP-1s, THR-beta agonists, or anti-fibrotic agents—could crowd out Sagimet’s market opportunity, especially if payers or clinicians see limited incremental benefit from FASN inhibition. In acne, a lack of clear differentiation or commercial execution challenges could limit uptake, particularly if established therapies remain standard of care.
This scenario would be confirmed by missed clinical endpoints, regulatory setbacks, or discontinuation of programs. Financial pressure would intensify, leading to potential pipeline reprioritization, down-round financings, or a strategic shift toward out-licensing or acquisition.
Milestones That Will Define Sagimet’s Therapeutic and Commercial Trajectory
Enrollment pace, data quality, and interim results from the pivotal Phase 3 acne trial—especially any early efficacy or safety signals.
Regulatory feedback and trial initiation timing for the planned Phase 2 proof-of-concept study of denifanstat plus resmetirom in cirrhotic MASH (F4).
Updates on the U.S. regulatory pathway and commercial launch plans for denifanstat in acne, including payer and clinician engagement (if disclosed).
Progression of the TVB-3567 acne program, with Phase 1 safety/tolerability results and clarity on Phase 2 initiation.
Any new data or partnerships in oncology, which could broaden the platform’s relevance and create additional value streams.
Disclosure of biomarker validation and real-world patient selection accuracy, as this underpins the precision medicine thesis.
Financial disclosures regarding runway, R&D burn, and any non-dilutive funding from milestones or partnerships.
Competitive developments in MASH and acne, particularly new approvals or guideline changes that could shift the standard of care.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments