
Allogene Therapeutics: Off-the-Shelf CAR T Ambitions Confront Clinical, Regulatory, and Funding Pressures
Allogene Therapeutics is advancing allogeneic CAR T therapies for cancer and autoimmune diseases, leveraging in-house manufacturing and gene-editing partnerships.
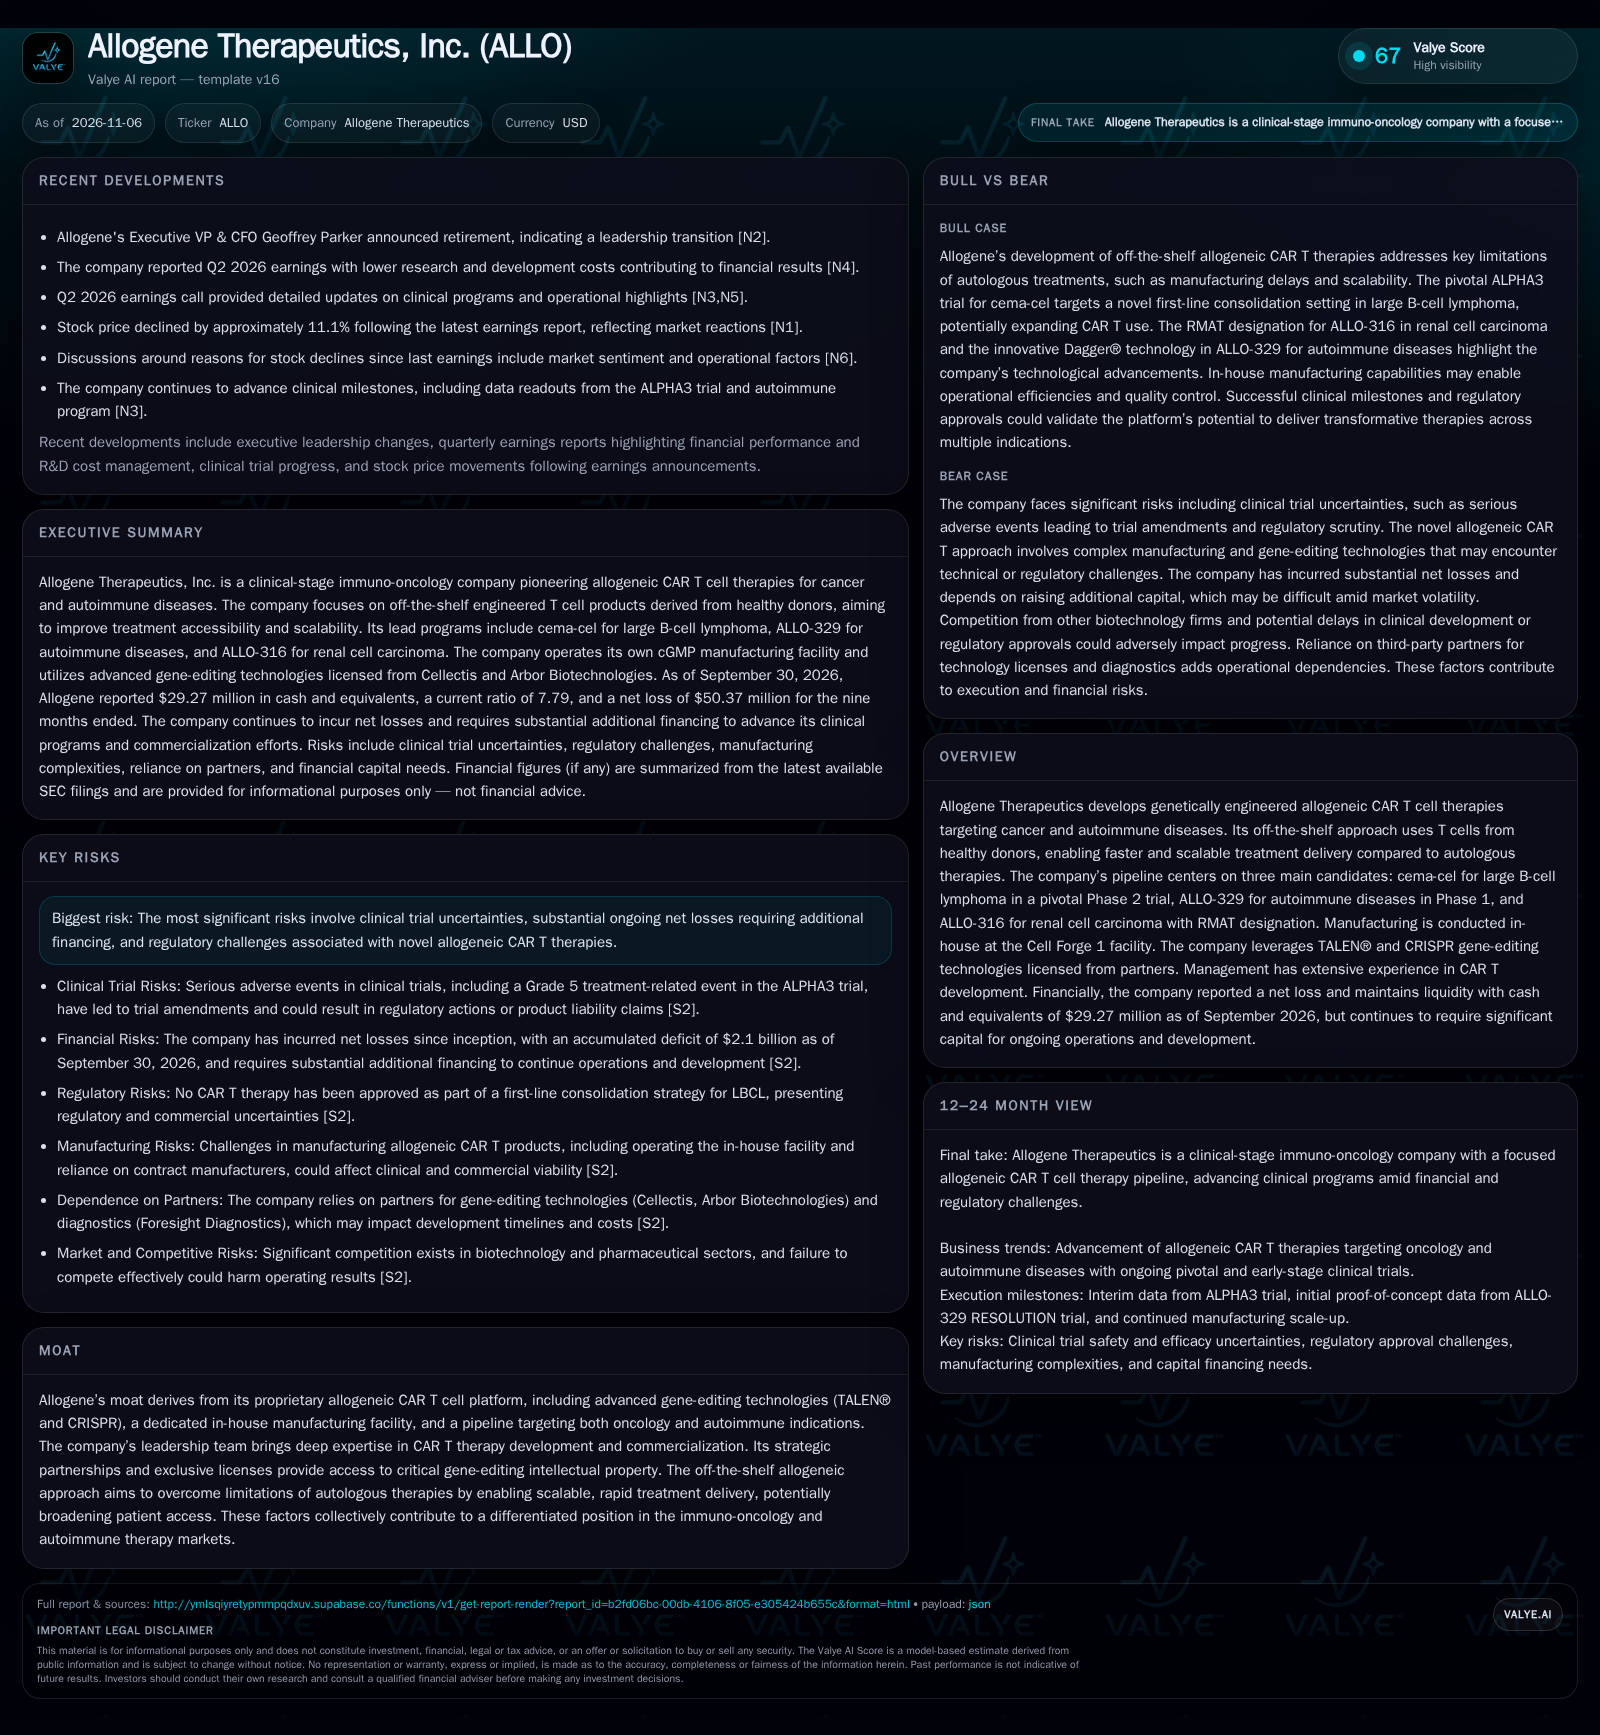
Allogene Therapeutics is developing off-the-shelf CAR T cell therapies with a focus on scalable cancer and autoimmune treatments. While it advances key clinical trials and leverages in-house manufacturing, the company faces a combination of steep net losses, a reported cash balance, and leadership transition. The investment case hinges on clinical data, regulatory progress, and urgent need for new funding. [S2] [N2] [N4]
Allogene Therapeutics is at the forefront of developing allogeneic, or 'off-the-shelf,' CAR T cell therapies—a strategy aiming to overcome the bottlenecks and high costs of autologous cell therapy. Its pipeline spans oncology and autoimmune indications, with cema-cel in a pivotal trial for large B-cell lymphoma and two other programs in earlier phases. [S2] [N2] [N1]
Recent Clinical Milestones and Financial Pressures Shape Allogene’s Outlook
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2] The company’s lead candidate, cema-cel, is in a pivotal Phase 2 trial (ALPHA3) for large B-cell lymphoma, with additional pipeline assets targeting autoimmune diseases (ALLO-329, Phase 1) and renal cell carcinoma (ALLO-316, RMAT designation). [S2] A serious Grade 5 treatment-related event in the ALPHA3 trial led to protocol changes, highlighting the high clinical risk profile. [S2] Leadership continuity is also in flux, with the announced retirement of CFO Geoffrey Parker. [N2] After the Q2 earnings report, shares fell by over 11%, reflecting market skepticism about near-term progress and capital sufficiency. [N1]
Examining the Economic Model of Allogeneic CAR T Therapy
Allogene’s business is predicated on the ability to deliver scalable, off-the-shelf CAR T therapies more rapidly and cost-effectively than autologous approaches. In theory, allogeneic manufacturing can drive down per-dose costs by leveraging economies of scale, centralized production, and standardized donor cells. However, actual economics depend on demonstrating clinical efficacy, safety, and regulatory approval, none of which are assured at this stage.
The company’s in-house Cell Forge 1 facility provides control over manufacturing quality and potential margin expansion if therapies reach commercial scale. Fixed costs are likely high, but variable costs per unit could fall with volume if regulatory and clinical milestones are met. Significant ongoing expenses include R&D, manufacturing scale-up, and licensing fees for gene-editing technologies from Cellectis and Arbor Biotechnologies. [S2]
Pricing power for approved CAR T therapies has historically been high, but payer scrutiny and competition from both autologous and emerging allogeneic players could constrain ultimate ASPs. If Allogene secures approval in a first-line consolidation setting for LBCL, this could expand addressable markets, but would also require substantial investment in commercialization and post-marketing commitments.
Where Allogene’s Platform Stands in the Race for Next-Gen Cell Therapies
Allogene competes in a crowded field of cell therapy innovators, including autologous CAR T incumbents and multiple allogeneic aspirants. Its proprietary platform leverages TALEN® and CRISPR gene-editing, in-house cGMP manufacturing, and a pipeline spanning both oncology and autoimmune diseases. This breadth is a differentiator and could provide resilience if one indication stalls.
However, the company’s moat is not insurmountable. Competing firms are pursuing similar gene-editing and off-the-shelf strategies, and the regulatory pathway for allogeneic CAR Ts remains uncertain. No therapy has yet been approved for a first-line consolidation setting in LBCL, making cema-cel’s pivotal trial a high-risk, high-reward proposition. [S2] Partnerships for enabling technologies and diagnostics, while necessary, introduce reliance and potential cost escalation.
Switching costs for prescribers and payers are likely moderate, as decision-makers prioritize efficacy, safety, and logistics. If Allogene’s therapies can demonstrate superior accessibility and comparable or better outcomes, it could capture share from autologous incumbents. Conversely, any clinical or regulatory setback could quickly erode its competitive standing.
What Could Unlock Value: Clinical Readouts, Regulatory Tailwinds, and Platform Validation
A favorable scenario for Allogene unfolds if pivotal ALPHA3 data show compelling efficacy and manageable safety in large B-cell lymphoma, enabling regulatory approval in a first-line or early-line setting. This would validate the core allogeneic platform, support expansion into additional oncology and autoimmune indications, and attract commercial or strategic partners, potentially easing capital constraints.
The company’s in-house manufacturing could allow rapid scale-up and higher margins if demand materializes. Early proof-of-concept from ALLO-329 in autoimmune diseases could further diversify the opportunity set.
Evidence to confirm this scenario would include positive top-line ALPHA3 results, regulatory feedback indicating an approvable path, early partnering or licensing activity, and credible financing announcements that extend runway into commercialization. Strong uptake in early access or expanded access programs would further support the thesis.
Likely Trajectory: Incremental Progress Amid Financing and Execution Risks
The most plausible path is one of continued incremental clinical progress, interspersed with periods of capital raising and operational adjustment. Allogene may achieve meaningful clinical milestones—such as interim ALPHA3 data or initial signals in ALLO-329—but is likely to face delays, protocol amendments, or regulatory requests for additional data. The company will need to secure additional funding, potentially through dilutive equity issuance, partnerships, or non-dilutive financing, to maintain momentum.
Clinical, regulatory, and commercial headwinds are likely to persist, particularly given the novelty of the allogeneic approach and the competitive intensity of the cell therapy space. The transition in financial leadership adds near-term uncertainty to planning and execution. Confirmation of this scenario would come from continued net losses, frequent fundraising, and a stepwise cadence of trial updates rather than a single transformative event.
Falsification would require a clear break from this pattern—such as rapid trial success, a major strategic partnership, or a surprise regulatory approval.
How the Thesis Fails: Clinical Setbacks and Capital Shortfalls
The adverse scenario materializes if Allogene’s pivotal and early-stage trials fail to demonstrate sufficient safety or efficacy—particularly if further serious adverse events occur or regulators impose holds or demand more data. This would jeopardize not only the lead cema-cel program but also market confidence in the allogeneic CAR T approach more broadly.
With current cash reserves low, the company may be forced into highly dilutive financings or cost-cutting measures that impair R&D and manufacturing capabilities. The risk of losing access to licensed gene-editing technologies or essential personnel could further destabilize the business.
Confirmation of this scenario would include negative or inconclusive clinical data, regulatory delays or holds, inability to raise new capital on viable terms, and visible contraction in pipeline activity or headcount.
What Will Determine Allogene’s Next Act in Cell Therapy Innovation?
Pivotal ALPHA3 trial data readouts for cema-cel, including efficacy, safety, and regulatory feedback.
Updates on ALLO-329’s progress in autoimmune disease indications, especially early clinical signals or trial expansions.
Disclosure of new financing arrangements, including equity, debt, or strategic partnerships that extend operational runway.
Manufacturing milestones at Cell Forge 1, such as capacity utilization, cost per batch, or successful scale-up (if disclosed).
Retention and recruitment of key leadership and technical personnel following CFO retirement and amid ongoing R&D needs.
Any changes in licensing terms or relationships with gene-editing and diagnostic partners, which could impact development timelines or costs.
Trends in R&D and SG&A spend relative to pipeline advancement, to assess capital efficiency and sustainability.
Market and payer feedback on the potential adoption of allogeneic CAR T therapies as trial results become public.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments