
Avant Technologies (Avai Bio): Proprietary AI Ambitions Confront Severe Liquidity and Commercialization Barriers
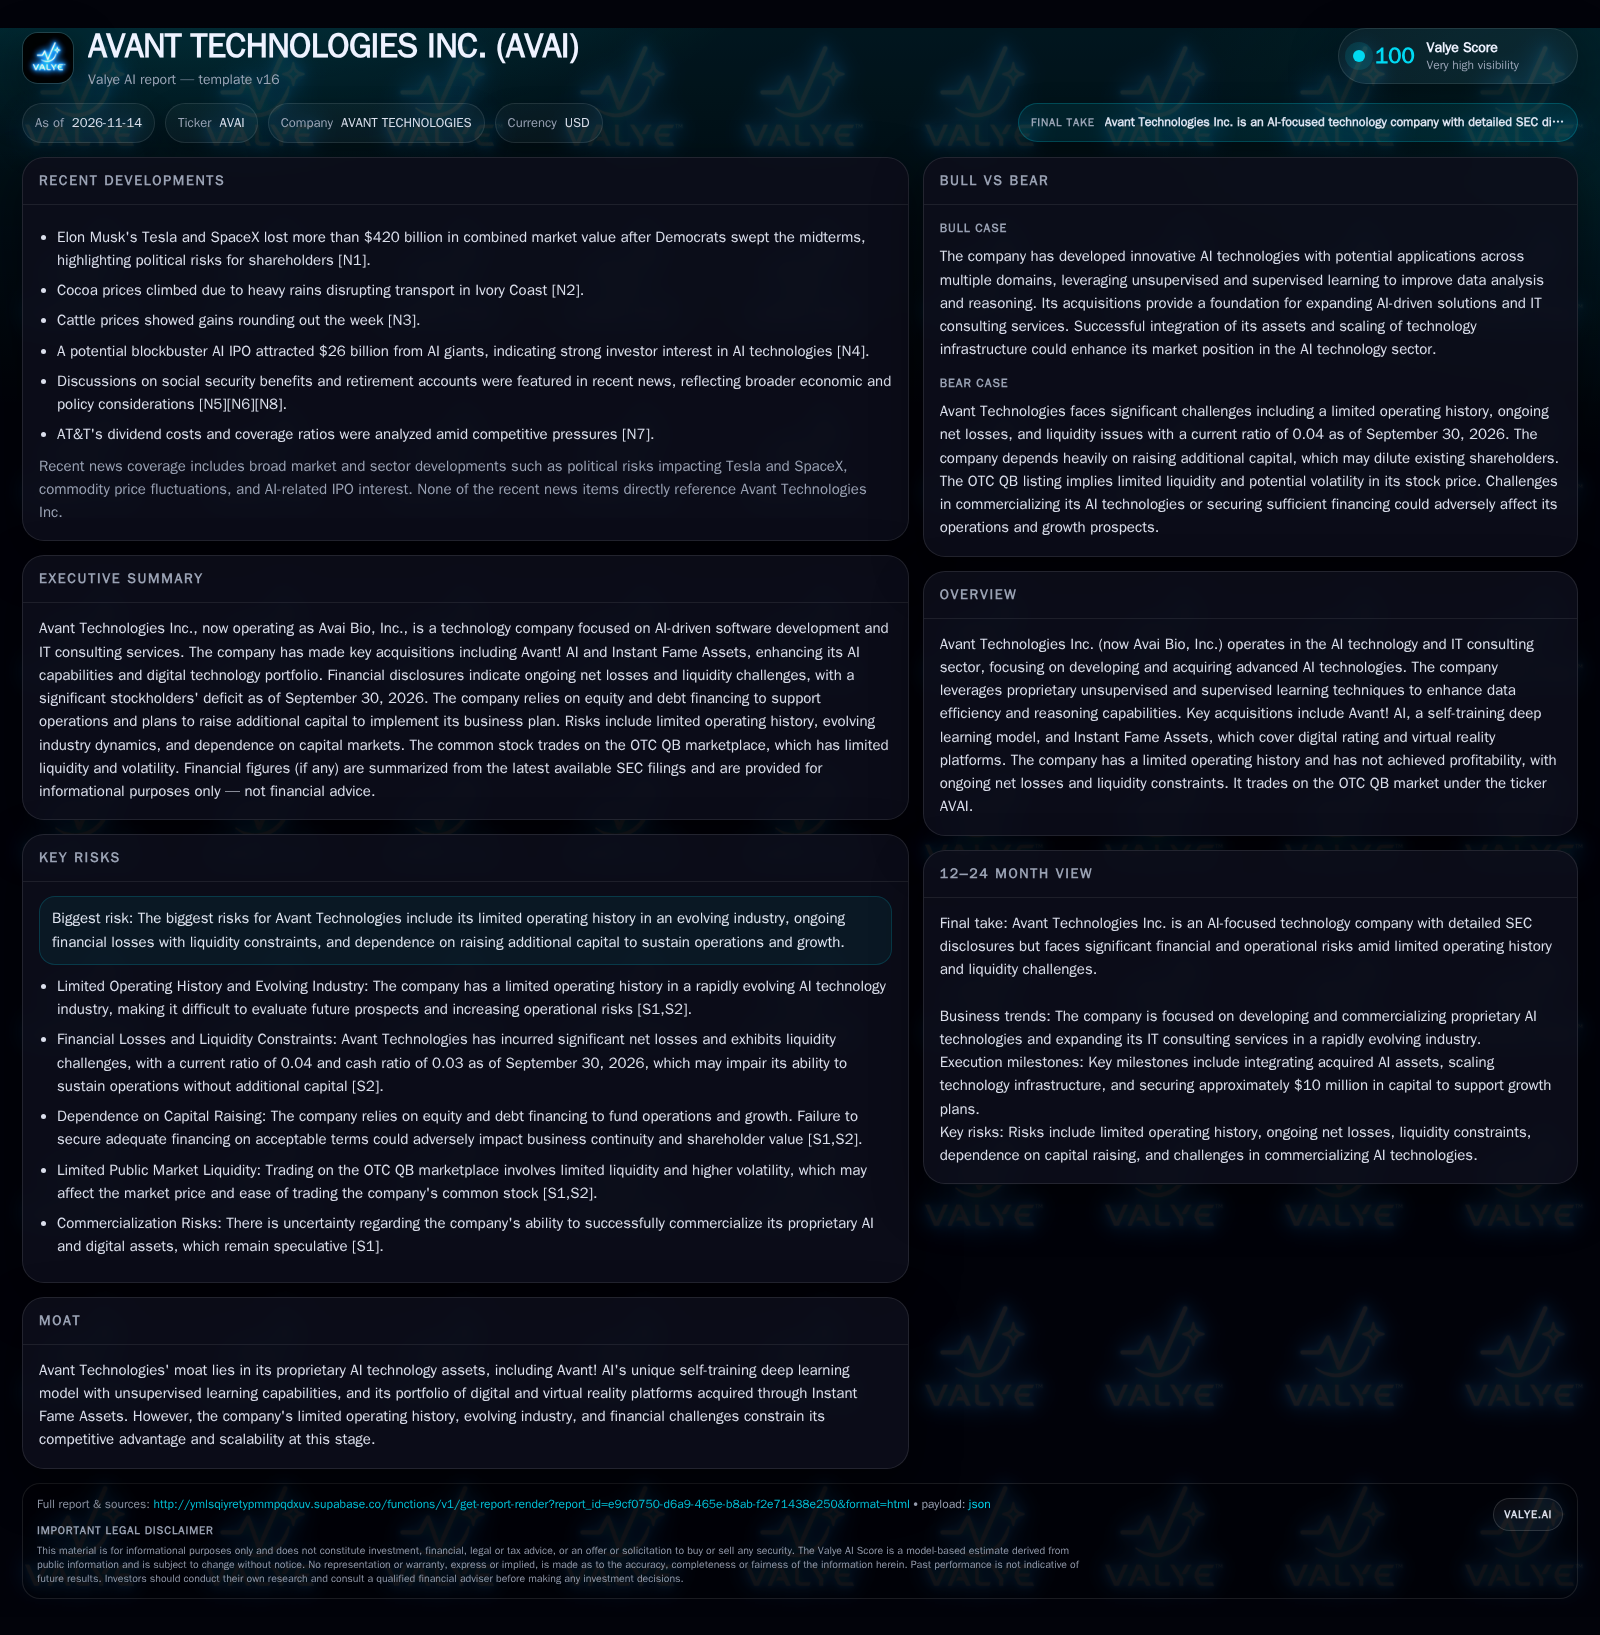
Avant Technologies, now Avai Bio, holds proprietary AI assets and digital platforms with theoretical multi-domain potential, but is constrained by persistent operating losses, a sharply negative balance sheet, and dependence on external capital. The company’s ability to transform R&D into sustainable revenue remains unproven, with existential risks from both financing and commercial execution.
Avant Technologies (Avai Bio) possesses proprietary AI and digital platform assets, aiming to commercialize advanced information technology solutions. Despite these technical foundations, the company continues to report substantial net losses, minimal cash, and a significant stockholders’ deficit. Its business plan hinges on raising ~$10 million in new capital—a prerequisite for both survival and scaling. Success depends on proving product-market fit, executing on technology integration, and overcoming the structural limitations of its OTC QB listing.
Avant Technologies (now Avai Bio) offers a case study in early-stage AI commercialization risk: it controls proprietary unsupervised learning assets and digital technology platforms, yet faces acute financial distress and the daunting challenge of validating product-market fit in a competitive and capital-intensive sector. The next twelve months are likely to be decisive for both viability and value creation.
Liquidity Crisis and Ongoing Losses Define the Immediate Outlook
As of September 30, 2026, Avant Technologies (Avai Bio) reported cash and equivalents of $121,948 against current liabilities of $4,534,882, producing a current ratio of just 0.04 and a cash ratio of 0.03 [S2]. Stockholders’ deficit stood at $3,415,806, with an accumulated deficit of $6,673,300 [S2]. The company posted net losses of $1,749,509 for the fiscal year ended March 31, 2026, and $805,281 for the following six months [S1] [S2]. These numbers indicate ongoing negative cash flow and a balance sheet under severe stress. Management has identified a need to raise approximately $10 million in new capital to implement its business plan, making external financing the central gating factor for continued operations [S1] [S2].
How Monetization Could Work: Asset Leverage, Cost Structure, and Funding Imperatives
Avant Technologies’ business thesis centers on the commercialization of proprietary AI assets, notably Avant! AI, a self-training deep learning model with unsupervised learning features, and digital/virtual reality platforms acquired via Instant Fame [S1]. The company positions itself as a provider of advanced AI-driven IT consulting and software solutions. In theory, monetization could occur through SaaS subscriptions, licensing of AI models, bespoke IT consulting engagements, or platform fees for digital assets. However, no recurring revenue mechanism or contract structure is specified in current disclosures.
The operating cost base is likely dominated by R&D, platform development, and technical staffing, with additional fixed costs for administration and compliance. Given the early stage and negative operating cash flow, variable costs are less material than the fixed overhead required to maintain and advance technology assets. The company’s persistent net losses and reliance on equity/debt financing suggest that operating leverage will remain negative until a commercial breakthrough occurs. The planned $10 million capital raise appears essential to fund both ongoing burn and any expansion required to reach scale [S1] [S2].
A critical factor in Avant Technologies' monetization strategy involves the scalability of its AI and digital platforms. Theoretically, SaaS and licensing models offer high gross margins once fixed development costs are amortized, but achieving this requires reaching a sufficient user base or client portfolio to offset ongoing R&D and support expenses. The absence of disclosed recurring revenue suggests the company is still in a pre-scale phase, where customer acquisition costs may exceed initial revenues. Furthermore, the success of bespoke consulting engagements depends heavily on the firm's ability to demonstrate domain expertise and deliver measurable client outcomes, which can be challenging without established case studies or reference clients.
Funding imperatives also highlight the importance of operational efficiency and capital allocation discipline. Given the capital-intensive nature of AI model training and platform maintenance, the company must carefully prioritize development initiatives that enhance product differentiation and customer value. If the company can leverage partnerships or open-source frameworks to reduce development costs, it may improve its cash burn profile. Conversely, overextension into multiple product lines without clear revenue pathways could exacerbate liquidity challenges. The timing and structure of capital raises—whether equity, debt, or convertible instruments—will influence dilution, cost of capital, and potential financial flexibility, impacting long-term sustainability.
AI Differentiation Meets Intense Competition and Substitution Threats
Avant’s competitive narrative rests on proprietary technology—specifically, its Avant! AI platform with unsupervised learning and self-training capabilities, and digital/VR assets from Instant Fame [S1]. In principle, these could differentiate the company in markets that value advanced data analysis, automation, and virtual experiences. However, the AI sector is structurally defined by rapid innovation cycles, high capital intensity, and intense competition from both well-funded incumbents and nimble startups. Barriers to entry for core AI models have fallen due to open-source alternatives and cloud-based AI services.
Switching costs for enterprise customers are typically low unless integration is deep or the platform becomes mission-critical, which has not been established here. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. Without clear evidence of commercial traction, Avant’s technology assets face the risk of commoditization or being leapfrogged by better-capitalized or more agile rivals.
What a Breakthrough Could Look Like: Commercial Validation and Funding Catalysts
The most favorable scenario envisions Avant Technologies successfully raising the targeted ~$10 million, enabling it to fully integrate its AI and digital assets, accelerate product development, and launch market-ready solutions. If the Avant! AI platform or Instant Fame’s digital/VR technologies find early adopters—particularly in verticals with urgent automation or data analysis needs—this could drive initial revenue and build credibility.
Evidence that would confirm this upside includes: closing of the planned capital raise on non-punitive terms; announcements of multi-customer commercial contracts or pilot deployments; early proof of recurring revenue or SaaS adoption; and signs of positive customer feedback or integration into partner ecosystems. If these milestones are achieved, the company could leverage its expanded capital base to scale more efficiently and potentially attract additional institutional or strategic interest.
Capital Raising Remains an Existential Prerequisite Amid Ongoing Burn
The most plausible path over the next year is that Avant continues to pursue external financing while operating at a significant loss. Given persistent negative cash flow and the magnitude of liabilities relative to assets, securing new capital is non-negotiable for survival. If the company succeeds in raising funds, but only at highly dilutive or expensive terms, its ability to invest in growth will be constrained, and shareholder value will be at risk.
In this scenario, commercial progress is likely incremental: pilot projects, limited consulting engagements, or prototype launches, but no material recurring revenue. Confirmation would come from modest contract announcements, ongoing R&D disclosures, and further equity or convertible debt issuance. Falsification would be a failure to secure funding, leading to restructuring or wind-down.
Failure to Secure Funding or Validate Product-Market Fit Triggers Restructuring Risk
The adverse scenario is straightforward: Avant Technologies is unable to raise the required capital in time or on acceptable terms. [S2] Inability to demonstrate commercial demand for its proprietary AI or digital platforms would compound this risk, potentially forcing asset sales, restructuring, or bankruptcy.
Downside confirmation would include missed or delayed capital raises, acceleration of payables, inability to retain technical talent, or management disclosures about going-concern risks. Any evidence of failed product launches, customer churn, or lack of commercial interest would further validate the bear case.
Milestones That Will Determine Whether Avant Technologies Can Transition from R&D to a Going Concern
Closure and terms of the planned ~$10 million capital raise: whether the company can access sufficient funding and at what cost [S1] [S2].
Announcements of commercial contracts, pilot programs, or SaaS licensing deals: actual evidence of market demand (if disclosed).
Product integration milestones—especially deployment of Avant! AI or Instant Fame technologies in real-world customer settings.
Quarterly cash burn and updated balance sheet metrics, to assess runway and solvency risk (if disclosed).
R&D and technology platform progress: updates on new features, integrations, or usability improvements to support commercialization.
Management commentary on customer acquisition, retention, and feedback: any early signals of product-market fit.
Changes in competitive landscape or technology standards that could affect the relevance of Avant’s proprietary assets.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments