
Cardio Diagnostics: AI-Epigenetics Diagnostics at the Intersection of Innovation, Regulation, and Commercialization
Cardio Diagnostics Holdings, Inc. advances AI-driven epigenetic diagnostic testing for cardiovascular disease, but faces a complex mix of long commercialization cycles, evolving regulatory oversight, and acute financial pressures. Execution on payor coverage, provider adoption, and international expansion will determine if its technology can convert clinical promise into a viable, scaled business.
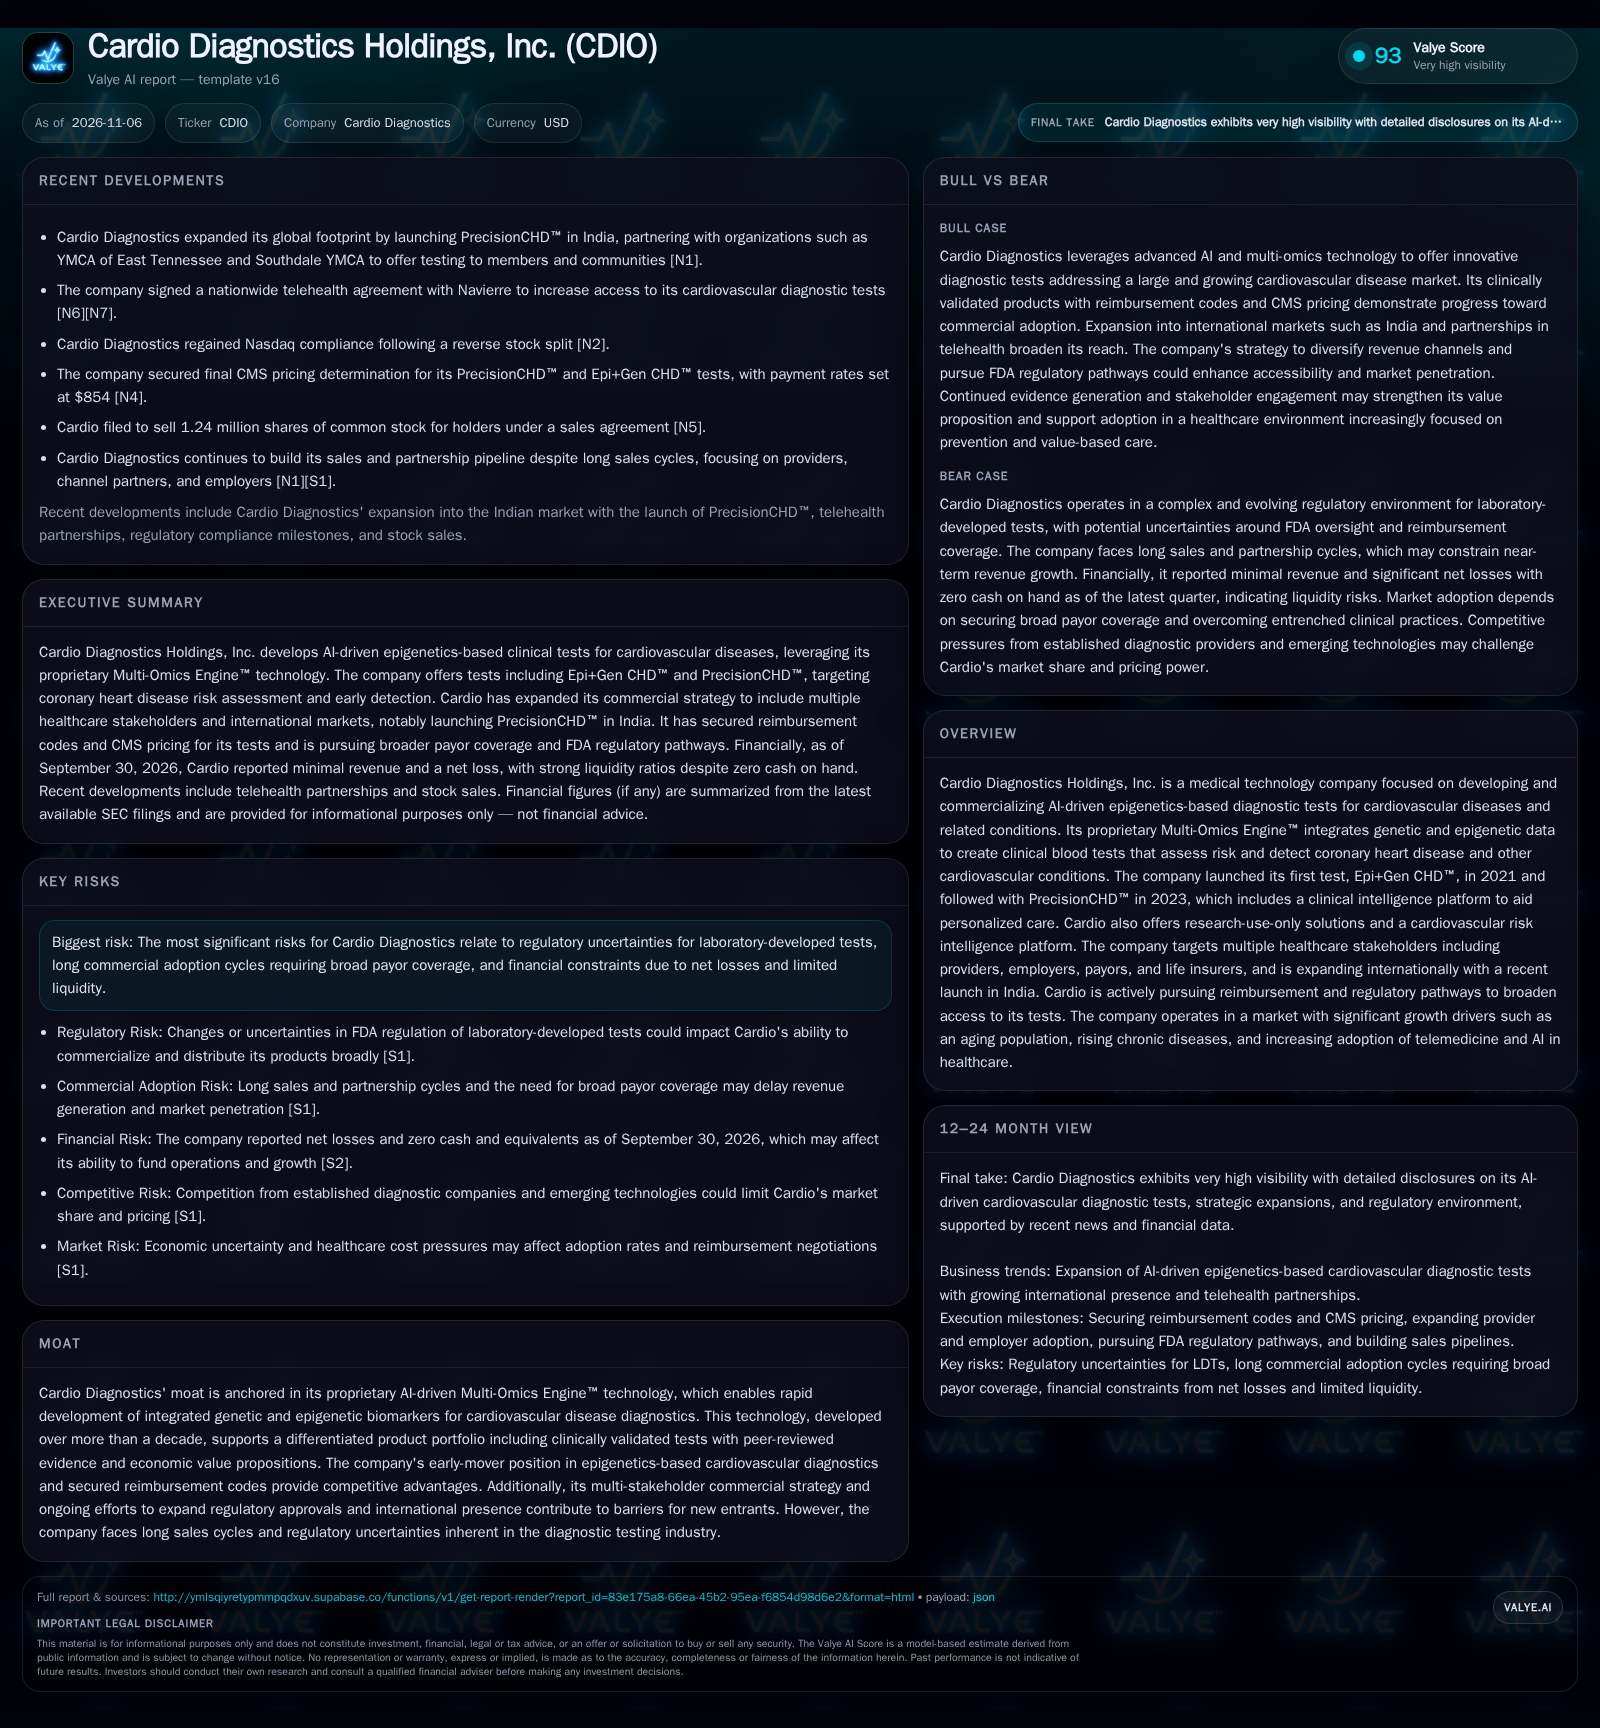
Cardio Diagnostics has launched several AI-driven, epigenetics-based cardiovascular diagnostic products, secured CMS pricing, and expanded internationally, but continues to face minimal revenue, persistent net losses, and a challenging regulatory and reimbursement environment. The company’s ability to build clinical and economic evidence, shorten sales cycles, and secure broader payor coverage will be critical for commercial viability and growth. [S1] [S2]
Cardio Diagnostics Holdings, Inc. stands at a pivotal point as it seeks to commercialize its suite of AI- and epigenetics-based blood tests for cardiovascular disease risk and detection. Despite scientific differentiation and recent wins such as CMS gapfill pricing and expanded international and telehealth partnerships, the company’s financial statements reflect the difficult realities of scaling a novel diagnostic model: revenue remains negligible, losses are substantial, and the road to broad clinical adoption is complicated by long sales cycles and evolving regulatory frameworks. The next phase will critically test whether Cardio’s technology and strategy can overcome these hurdles to establish a sustainable business.
Recent Developments Define Cardio Diagnostics’ Commercial and Financial Landscape
Cardio Diagnostics has made notable progress in product development and market access: it has launched multiple AI-driven cardiovascular diagnostic tests (Epi+Gen CHD™, PrecisionCHD™, HeartRisk™), secured final CMS payment rates of $854 for its two leading tests, and expanded internationally with a PrecisionCHD™ launch in India [S1] [N1] [N4]. The company also inked a nationwide telehealth agreement with Navierre, aiming to broaden access to its tests [N6] [N7]. However, the commercial impact is not yet evident in financials: Q3 2026 revenue was just $3,590, with a net loss of $1.73 million and zero cash on hand as of September 30, 2026, despite a reported current ratio driven by non-cash assets [S2]. Sales and partnership cycles remain long (up to 24 months), and broad payor coverage is still pending [S1]. These facts highlight both the ambition and the acute challenges facing Cardio Diagnostics at this stage.
How Cardio’s Diagnostic Model Could Scale—and Where Economic Friction Lies
Cardio Diagnostics’ business model relies on generating revenue from proprietary laboratory-developed tests (LDTs) that integrate AI-driven genetic and epigenetic analysis. The CMS reimbursement rate of $854 per test sets a reference point for potential economics, but actual realized pricing will depend on the payer mix, negotiated rates, and the proportion of tests reimbursed by Medicare versus commercial insurers [S1] [N4]. Variable costs are likely dominated by reagents, sample processing, and lab labor, with significant fixed costs in R&D, regulatory compliance, and commercial infrastructure. As with other diagnostics companies, operating leverage could be substantial if test volumes scale, given high gross margins typical for lab-based molecular diagnostics once the fixed cost base is covered.
However, commercial friction is pronounced: long sales cycles, the need to educate and convince multiple healthcare stakeholders, and the requirement for ongoing evidence generation all slow adoption. Cardio’s expansion into employer and insurer channels, as well as international markets, may offer higher-volume, lower-cost customer acquisition pathways, but these channels also tend to be price sensitive and require robust clinical and economic validation. The company’s potential to sell synergistic products or expand its platform into adjacent indications could improve revenue per account and lifetime value, but only if initial adoption hurdles are overcome.
Capital needs remain high given persistent net losses, the need to fund sales team expansion, clinical studies, and potential regulatory submissions. The company’s recent at-the-market stock sales and shelf registration for additional equity highlight a reliance on dilutive funding to bridge the gap to scale [S1]. Without a material revenue ramp, this dynamic could persist.
Differentiation and Defensibility in a Crowded Cardiovascular Diagnostics Market
Cardio Diagnostics’ defensibility is rooted in its proprietary AI-driven Multi-Omics Engine™ and its focus on integrated genetic and epigenetic biomarkers—a less crowded niche compared to conventional protein- or gene-only cardiovascular diagnostics [S1]. This provides a technical barrier to entry and supports differentiated clinical claims, particularly for early, actionable CHD risk assessment. Securing CPT PLA codes and CMS pricing is a further advantage, as it enables reimbursement for its tests, a hurdle that many early-stage diagnostics firms fail to clear [N4].
However, the company faces formidable competition from large established diagnostics providers, academic medical centers, and emerging digital health platforms. Many of these players have greater commercial reach, deeper clinical datasets, and established relationships with payors and provider organizations. Cardio’s early-mover position in epigenetics-based CVD testing is meaningful, but fast followers could emerge if the market opportunity is validated. Furthermore, the integration of AI is increasingly common in diagnostics, potentially eroding any perceived technology lead unless Cardio can demonstrate superior clinical utility or workflow integration.
Switching costs for providers are low unless Cardio’s tests become embedded in care pathways or bundled with actionable clinical intelligence that materially improves outcomes or system economics. The company’s efforts to expand into employer and insurer channels, as well as its international push, could build network effects if adoption accelerates. However, these effects remain hypothetical at current adoption levels.
If Clinical and Economic Evidence Unlocks Payor and Provider Adoption
A favorable outcome for Cardio Diagnostics would see robust clinical studies validating the efficacy and utility of its epigenetics-based tests, leading to broad payor coverage and rapid uptake by large provider networks, insurers, and employer groups. The combination of final CMS rates, peer-reviewed evidence, and integration with clinical intelligence platforms could make tests like PrecisionCHD™ a default component of cardiovascular risk assessment, particularly in populations where early detection drives cost savings.
Successful execution would be confirmed by a material acceleration in test volumes (quarter-over-quarter growth in reimbursed tests), the addition of major commercial payors or employer contracts, and a ramp in international revenues from markets such as India. If realized, the high gross margins typical of lab-based diagnostics would drive operating leverage, enabling Cardio to scale with declining losses and eventual profitability.
This scenario would be falsified if, despite evidence generation, payor coverage remains limited, test volumes do not accelerate, or adoption stalls due to workflow or reimbursement friction.
Scaling Remains Slow: Commercial Progress Lags Potential
The most plausible trajectory is continued slow but steady progress: Cardio Diagnostics incrementally expands its provider base and telehealth footprint, secures a handful of commercial payor agreements, and sees modest growth in test volumes—primarily in niche, high-touch settings such as concierge medicine, research collaborations, and targeted international partnerships. Revenue begins to rise but remains well below the level required for break-even, given the scale of fixed costs and ongoing investment in sales, clinical validation, and regulatory compliance.
Evidence for this scenario would include gradual but not exponential increases in quarterly revenue, limited dilution per quarter, and piecemeal announcements of new partnerships or small-scale payor wins. This outcome would be challenged if a major provider, payor, or international partner adopted Cardio’s tests at scale, or if the company failed to demonstrate any revenue growth or continued to rely entirely on equity financing.
Commercial Traction and Liquidity Shortfalls Threaten Sustainability
In a negative scenario, Cardio Diagnostics fails to convert technical differentiation into meaningful commercial adoption. Long sales cycles, lack of broad payor coverage, and entrenched incumbent diagnostic providers combine to leave test volumes stagnant and revenue negligible. The company continues to burn cash, relying on increasingly dilutive equity financings that erode shareholder value and threaten listing status.
Confirmation of this scenario would come from flat or declining test volumes, continued net losses with no path to break-even, difficulties raising additional capital, or adverse regulatory or reimbursement changes that further restrict market access. This outcome could be accelerated if new entrants or established players introduce competing solutions with stronger distribution or bundled offerings.
Milestones That Will Reveal If Cardio Diagnostics Can Achieve Commercial Escape Velocity
Quarterly growth in reimbursed test volumes (PrecisionCHD™, Epi+Gen CHD™) would be the clearest indicator of commercial traction—if disclosed.
Announcements of new commercial payor contracts or inclusion in large provider network formularies would signal progress toward broader market access.
Evidence of international revenue generation, particularly from India or other new markets, would help assess the viability of Cardio’s global expansion.
Updates on clinical and economic evidence publication—peer-reviewed studies or real-world data supporting improved outcomes or cost savings—would support the value proposition.
Cash flow from operations and net cash burn per quarter would provide visibility into how quickly Cardio needs to raise additional capital.
Dilution from at-the-market or shelf equity offerings should be monitored to assess the sustainability of the company’s funding model.
Regulatory developments affecting LDT oversight (e.g., any renewed FDA initiatives) could materially impact commercialization pathways.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments