
CubeSmart in 2026: Real Estate Scale, Debt Management, and the Competitive Dynamics of Self-Storage
CubeSmart continues to grow its self-storage real estate portfolio and surpass operational benchmarks, but faces ongoing challenges tied to geographic concentration, debt maturities, and the evolving economics of storage demand. The interplay between property scale, capital structure, and market competition shapes the company’s risk-reward profile heading into 2027.
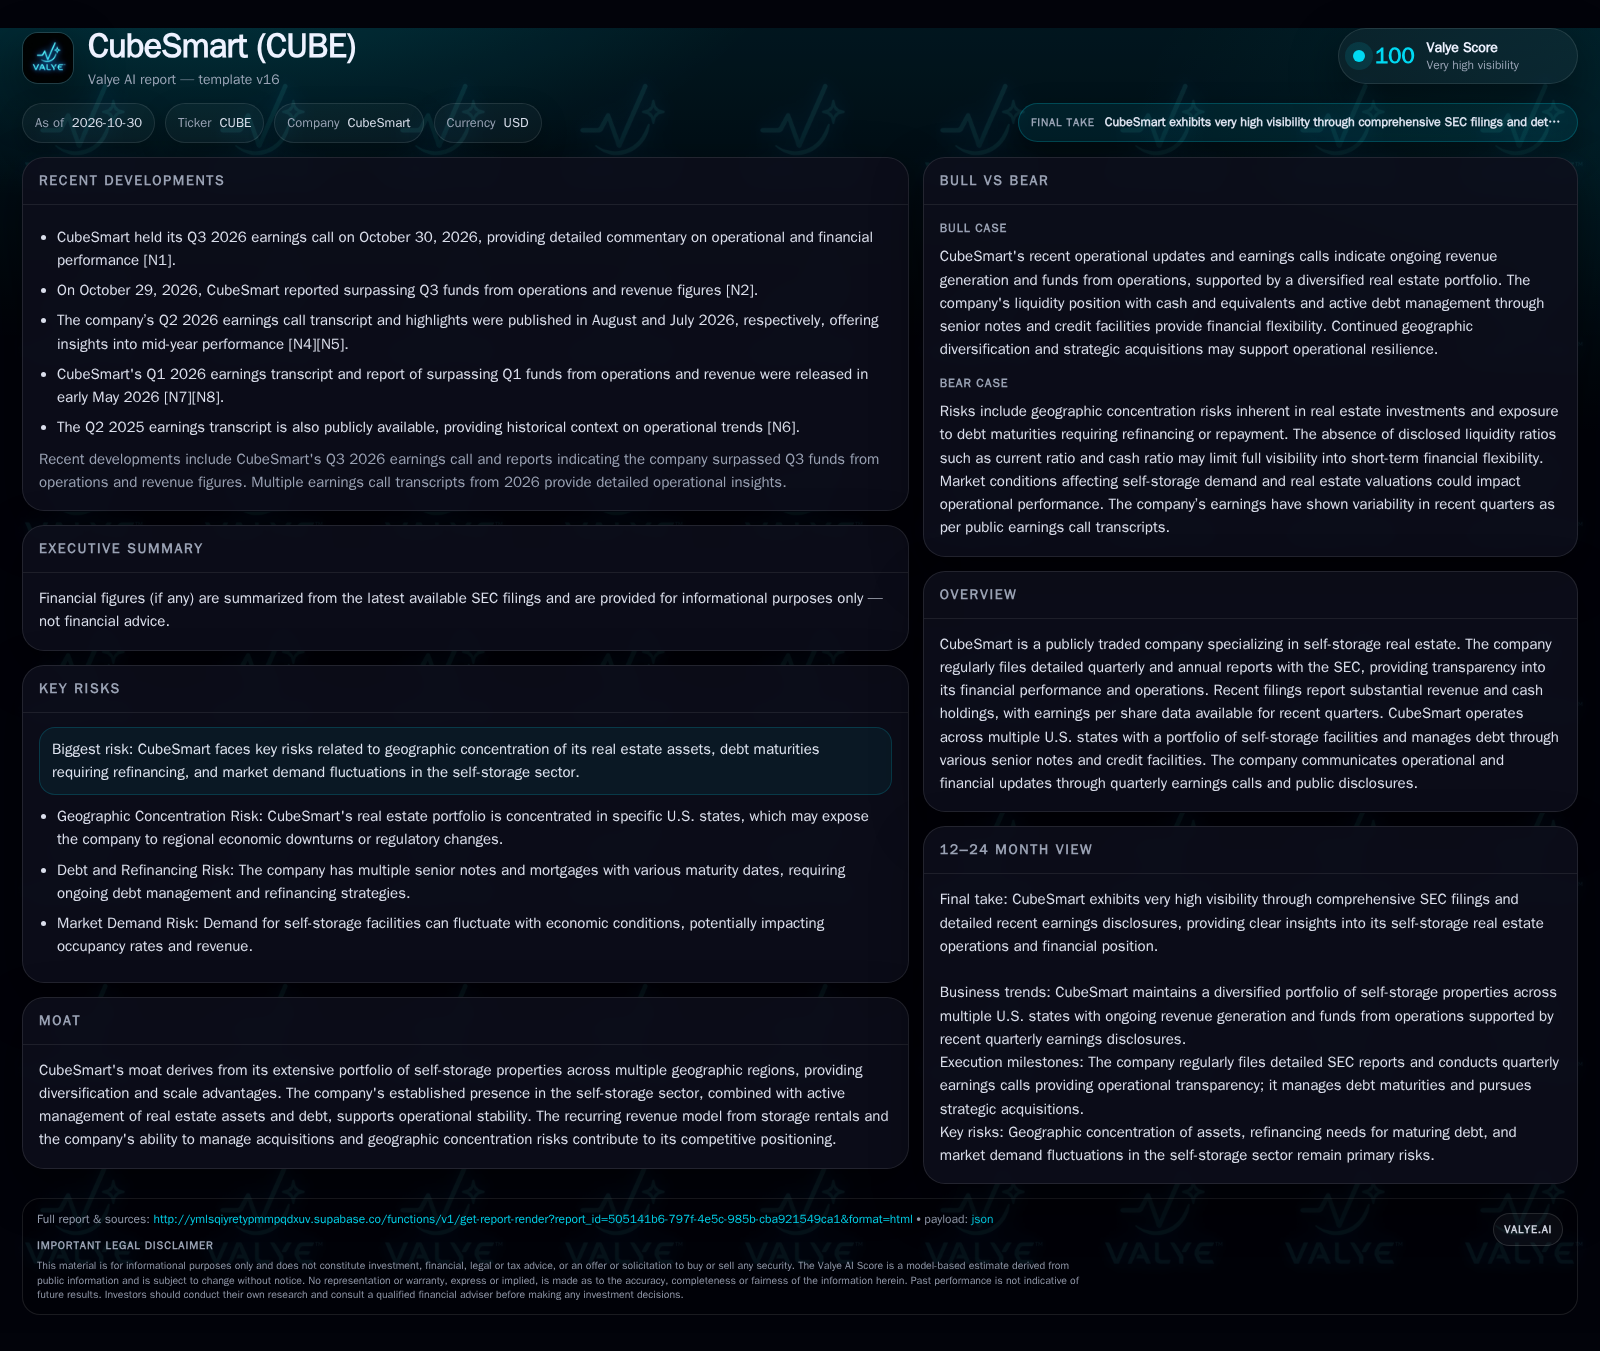
CubeSmart reported Q3 2026 results above funds from operations and revenue expectations, underlining strong operational execution. However, the company’s business model exposes it to geographic concentration and refinancing risks due to a substantial debt schedule and reliance on demand for self-storage. How CubeSmart manages property scale, capital deployment, and occupancy rates will determine its resilience amid a competitive and cyclical sector landscape. [N1] [N2]
CubeSmart’s recent quarterly performance highlights the strengths and vulnerabilities of a scaled self-storage REIT. The company continues to deliver revenue growth and surpass funds from operations targets, leveraging a diversified property base across multiple U.S. states. However, its business is tightly linked to the underlying health of real estate markets, the ebb and flow of storage demand, and the discipline of debt management. As CubeSmart approaches new refinancing cycles and faces sector-wide competitive pressures, its ability to maintain occupancy, pricing power, and capital efficiency will be tested. Investors must weigh the durability of recurring self-storage revenue against the risks of concentrated assets, refinancing obligations, and changing consumer and business storage needs.
Recent Results Signal Operational Momentum but Highlight Structural Exposures
CubeSmart reported revenue of $281.929 million for Q1 2026 and basic and diluted earnings per share of $0.36, reflecting continued scale in the self-storage sector. As of March 31, 2026, the company held $7.258 million in cash and cash equivalents, with a capital structure featuring multiple senior notes and mortgages of varying maturities. Notably, CubeSmart surpassed both funds from operations and revenue expectations in Q3 2026, as reported in late October. These results underscore robust operational execution, but the company’s reliance on debt financing and the geographic concentration of its real estate portfolio present material structural risks that will shape future performance. [S2] [N1] [N2]
How CubeSmart’s Revenue Model Balances Scale, Recurrence, and Leverage
CubeSmart generates the bulk of its revenue from rental income tied to its portfolio of self-storage facilities. The business model is inherently recurring, as customers typically pay monthly for storage units, supporting predictable cash flows. However, the economics are sensitive to occupancy rates, pricing strategies, and property-level operating expenses. Fixed costs—such as property taxes, insurance, and maintenance—are substantial, creating operating leverage when occupancy and rents are rising, but amplifying margin compression during downturns.
The company’s capital structure is debt-intensive, as evidenced by multiple senior notes and mortgages. This allows for property acquisition and expansion but raises exposure to refinancing risk and interest rate volatility. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. Major capital needs include property acquisitions, periodic facility upgrades, and debt servicing. The interplay between revenue growth, expense control, and prudent leverage determines CubeSmart’s ability to generate funds from operations—a critical REIT metric.
The sensitivity of CubeSmart’s revenue model to occupancy and pricing underscores the importance of dynamic asset management and market intelligence. For instance, the ability to adjust rental rates in response to localized demand fluctuations without triggering significant tenant churn is a nuanced capability that can materially affect revenue stability. Additionally, operating expenses may not scale linearly with occupancy; certain maintenance and security costs remain fixed or semi-variable, influencing margin profiles during occupancy shifts. Consequently, the company’s financial performance is contingent on its skill in balancing these variables within each market microenvironment.
Debt leverage amplifies both opportunity and risk in CubeSmart’s model, particularly given the capital-intensive nature of real estate investment trusts. While leverage can enhance returns during periods of revenue growth and stable interest rates, it also heightens vulnerability to refinancing cycles and credit market disruptions. The timing and terms of debt maturities relative to prevailing interest rate environments can significantly impact CubeSmart’s cost of capital and potential financial flexibility. Therefore, a rigorous approach to debt laddering and proactive refinancing strategies is critical to mitigate refinancing risk and preserve investment capacity for property upgrades or acquisitions.
Competitive Dynamics: Scale, Geographic Reach, and the Threat of Commoditization
CubeSmart operates in a fragmented but consolidating self-storage industry, where scale and geographic reach confer advantages in brand recognition, marketing efficiency, and cost structure. Its multi-state presence helps mitigate local market volatility, but significant exposure remains in key states—potentially amplifying the impact of regional economic downturns or adverse regulatory shifts.
The sector faces low switching costs for customers, making occupancy rates sensitive to price competition and local supply-demand imbalances. New entrants or aggressive pricing by established peers can pressure CubeSmart’s margins. Technology-driven aggregators and online brokers are also eroding some traditional advantages by increasing price transparency and making customer acquisition more competitive.
However, the company’s established asset base and ability to manage acquisitions provide a partial moat. Operational excellence—measured by occupancy, rent growth, and expense control—remains essential to sustaining returns in this increasingly commoditized environment.
The competitive landscape’s evolution toward commoditization is partly driven by digital transformation and shifting consumer behaviors. As price transparency increases through online platforms, self-storage providers face pressure to differentiate beyond traditional factors such as location and facility quality. CubeSmart’s ability to leverage technology for customer engagement, streamlined booking processes, and data-driven pricing strategies could be a decisive factor in maintaining occupancy and pricing power. Moreover, operational efficiencies gained through technology integration may offset margin pressures induced by competitive pricing, enhancing overall resilience.
What Could Drive Outperformance? Occupancy Discipline and Capital Deployment
CubeSmart’s upside scenario hinges on its ability to maintain high occupancy rates and steadily increase rental rates across its portfolio, even as new supply enters the market. If the company can efficiently integrate new acquisitions and selectively expand in high-growth regions, it may capture outsized revenue growth and margin expansion. Disciplined capital deployment—prioritizing properties with strong local demand and limited competition—would reinforce this outcome.
Confirmation of this scenario would come from sustained quarterly beats on funds from operations, rising same-store NOI (net operating income), and evidence of successful refinancing at favorable rates. If CubeSmart reports stable or growing occupancy above industry averages and demonstrates the ability to pass on rental increases without significant churn, that would further validate the upside path.
Core Outlook: Steady Returns, Managed Risk, and the Realities of Sector Cyclicality
The most plausible outcome is that CubeSmart delivers moderate revenue growth and stable funds from operations, supported by its established property base and ongoing acquisition pipeline. Operating metrics may fluctuate with local demand cycles and competitive pressures, but the company’s scale should enable it to broadly match sector trends.
Refinancing of debt is achieved without major disruption, but likely at incrementally higher rates given the sector’s exposure to interest rate cycles. Geographic concentration risk remains a watchpoint, but not an immediate destabilizer if regional economies remain resilient. Confirmation would include continued reporting of occupancy rates near historical averages, manageable debt maturities, and incremental growth in rental income per available square foot. Any material divergence in these metrics—such as a sharp drop in occupancy or failure to refinance key maturities—would challenge the base scenario.
Where the Model Breaks: Debt, Demand, and Localized Shocks
The principal downside risks for CubeSmart stem from a combination of adverse local economic events, a sharp decline in self-storage demand, and difficulty refinancing debt at sustainable rates. If major states in its portfolio experience economic contraction, regulatory tightening, or oversupply, CubeSmart could see rapid occupancy declines and downward pricing pressure. The company’s fixed cost base would magnify the impact on margins.
A tightening credit environment or a loss of access to affordable refinancing could force asset sales or constrain growth initiatives. Evidence supporting this scenario would include a marked rise in vacancy rates, deteriorating same-store NOI, unsuccessful or costly debt rollovers, or forced divestitures in key regions. In such a case, CubeSmart’s recurring revenue model may not be sufficient to offset the structural drag from debt service and declining property values.
Factors That Will Shape CubeSmart’s Resilience and Growth Trajectory
Quarterly occupancy rates and year-over-year same-store net operating income trends, especially in the company’s largest states.
Timing, structure, and cost of upcoming debt maturities and refinancing transactions, as disclosed in SEC filings or earnings calls.
Acquisition pace, property integration outcomes, and the geographic distribution of new investments.
Reported rental rate growth versus local market averages, indicating pricing power and competitive positioning.
Changes in customer mix (residential vs. commercial) and average length of stay, which would help test demand resilience.
Any disclosed changes in regulatory or tax policy affecting key markets such as New York, Florida, California, or Texas.
Management commentary on market supply trends, competitive pricing, and technology-driven shifts in customer acquisition or retention.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments