
Hyatt’s Fee-Driven Model: Growth Leverage and Liquidity Frictions Shape the Next Phase
Hyatt Hotels Corp’s Q3 2026 results underscore the power—and potential limits—of an asset-light, fee-based strategy. The company’s ability to translate brand scale into resilient earnings will depend on sustaining fee momentum, managing liquidity, and navigating cyclical demand swings.
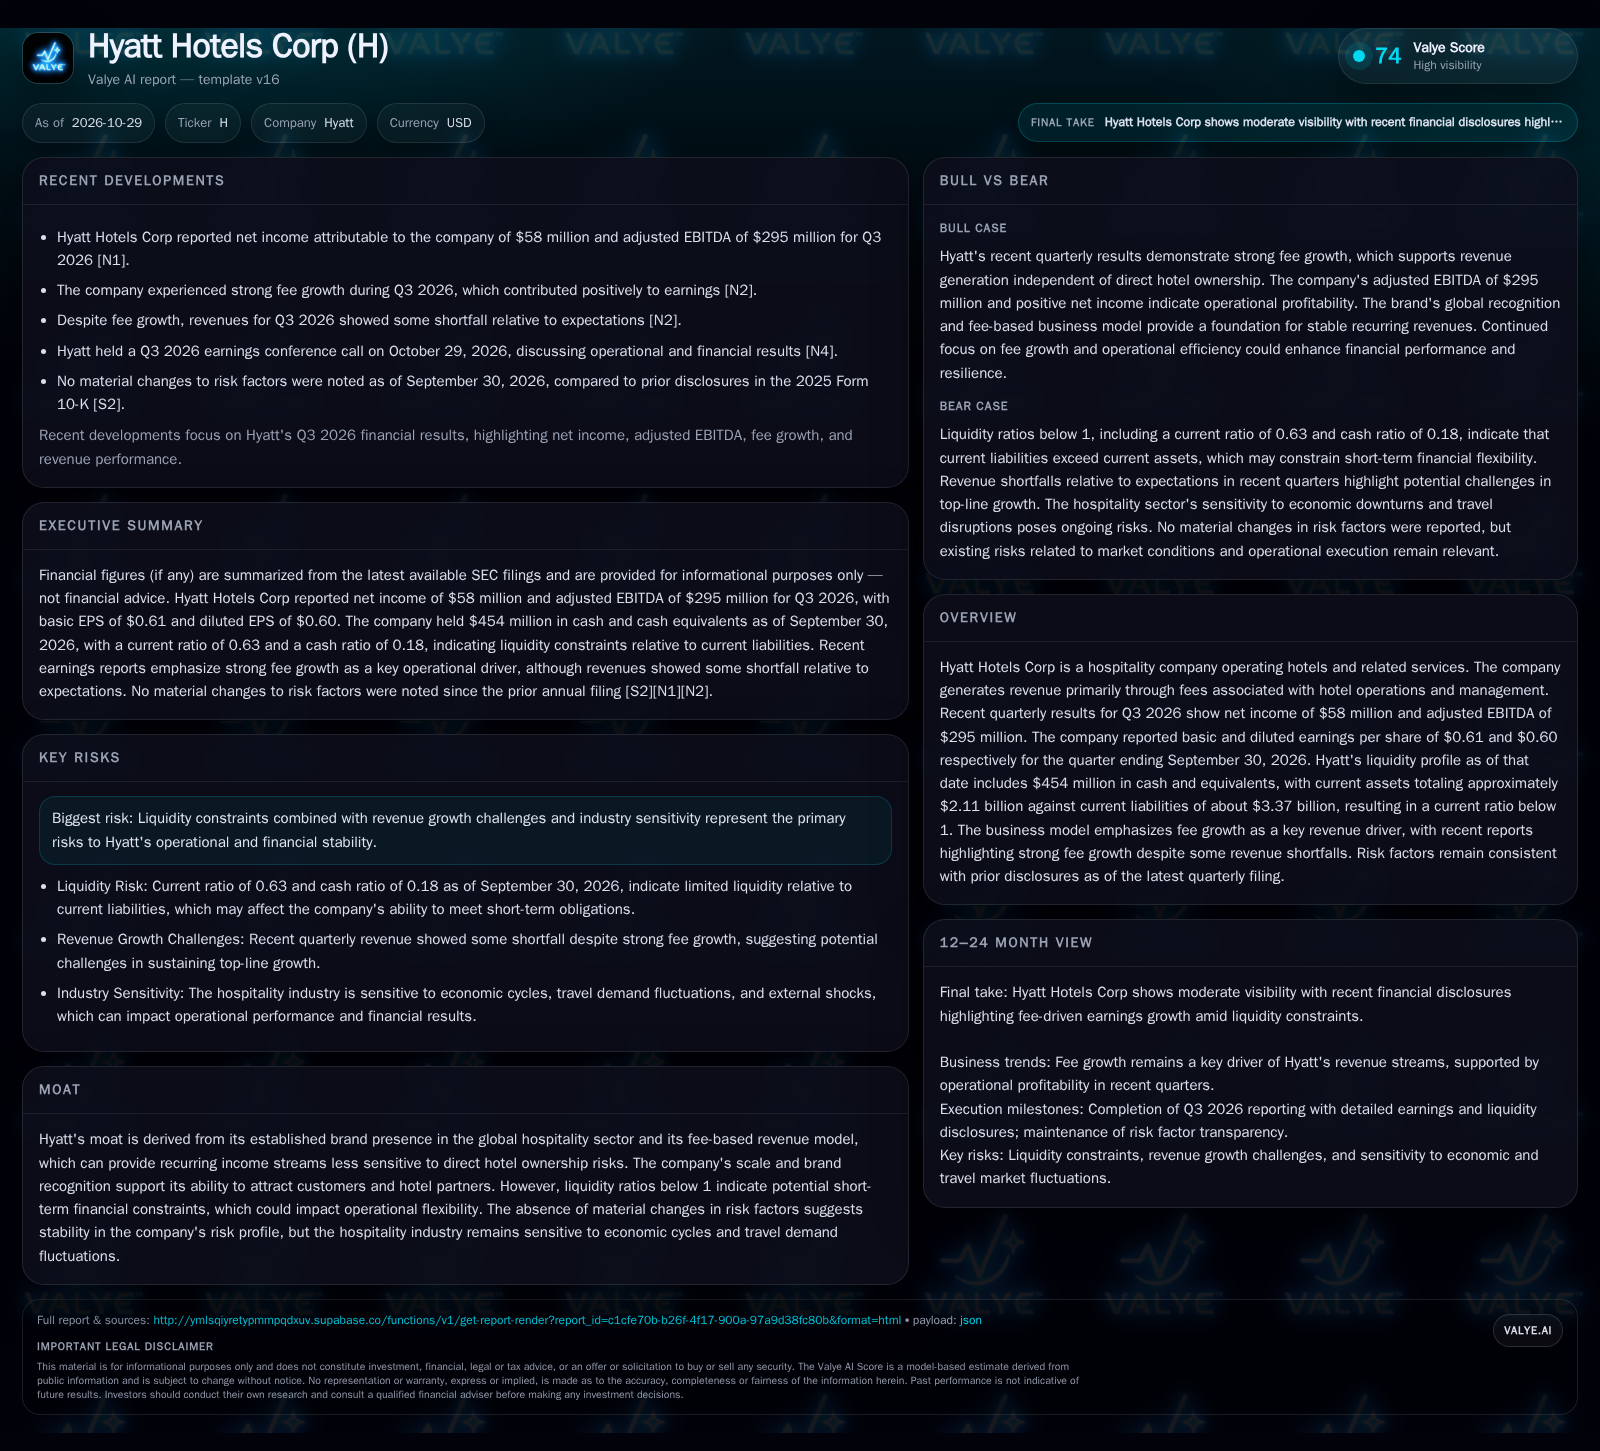
Hyatt’s Q3 2026 performance highlights robust fee income as the engine for earnings, with adjusted EBITDA reaching $295 million and net income at $58 million. The company’s future hinges on driving fee growth, efficiently managing working capital, and weathering macroeconomic shocks in a competitive hospitality landscape. [N1] [N2]
Hyatt Hotels Corp’s Q3 2026 results crystallize both the promise and complexity of the global hospitality sector’s shift toward asset-light, fee-driven models. With net income of $58 million and adjusted EBITDA of $295 million, Hyatt’s earnings were powered by strong fee growth, offsetting some revenue softness. How Hyatt balances these forces could determine whether its fee-based strategy delivers durable shareholder value—or exposes new vulnerabilities. [N1] [N2] [S2]
Fee Growth Drives Profitability, but Liquidity Tightness Raises the Stakes
Hyatt’s third-quarter 2026 results show adjusted EBITDA of $295 million and net income of $58 million, with basic and diluted EPS at $0.61 and $0.60, respectively. The quarter was characterized by robust fee income, which management emphasized as the primary engine of earnings. However, total revenue fell short of expectations, highlighting that fee growth alone has not fully insulated Hyatt from broader revenue pressures. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. No new material risk factors have emerged since the prior annual filing, but the company’s ability to manage working capital and sustain fee momentum is now a central watchpoint. [N1] [N2] [S2]
The interplay between fee growth and liquidity constraints is particularly critical given the hospitality industry's capital cycle and seasonal cash flow patterns. Moreover, the concentration of fee income in certain geographic regions or market segments could introduce volatility if localized disruptions occur, underscoring the importance of diversified fee sources and prudent cash flow forecasting.
How Hyatt’s Asset-Light Model Generates Earnings—and Where Leverage Emerges
Hyatt’s business model has pivoted decisively toward asset-light, fee-based operations, relying on management and franchise fees from a global hotel portfolio rather than direct property ownership. This structure reduces capital intensity, limits exposure to real estate cycles, and can boost margins through recurring high-margin fees. The company’s recent results suggest that fee growth is now the dominant driver of profitability, with adjusted EBITDA outpacing net income due to lower depreciation and direct operating costs relative to asset-heavy peers.
However, this model also creates operating leverage: incremental fee revenue, particularly from new hotel openings or improved RevPAR (revenue per available room), can flow disproportionately to the bottom line. Conversely, a downturn in travel demand or disruption in managed/franchised hotel performance can rapidly erode fee pools, amplifying earnings volatility. The limited asset base constrains collateral for new borrowing or liquidity backstops, making working capital management and access to external capital markets more critical in periods of stress. Hyatt’s below-1.0 current and cash ratios as of Q3 2026 mean the company must maintain disciplined expense control and may need to sequence investment or development commitments carefully if cash conversion lags.
An additional layer of complexity arises from the contractual structures underpinning Hyatt’s fee revenue streams. Management and franchise fees often include fixed components, performance-based incentives, and renewal clauses that can vary in duration and terms. This contractual mix influences the predictability and stability of earnings, with longer-term agreements providing more visibility but potentially limiting pricing flexibility. The balance between securing long-term contracts and maintaining competitive fee rates is delicate, as overly aggressive fee increases could prompt hotel owners to reconsider affiliations. Furthermore, the company's ability to innovate in fee structures—such as incorporating dynamic pricing linked to performance metrics—may enhance revenue capture but also requires sophisticated data analytics and negotiation capabilities.
Brand Scale, Global Reach, and Competitive Pressures in a Crowded Hospitality Landscape
Hyatt’s competitive strength derives from its global brand recognition, loyalty program scale, and ability to attract hotel owners to its management and franchise network. In the asset-light segment, competition is fierce—ranging from major global operators (such as Marriott, Hilton, and IHG) to regional and boutique brands, as well as emerging alternative lodging platforms. Hyatt’s broad geographic footprint and focus on upper-upscale and luxury segments may provide some insulation from pure price competition, but also expose it to cyclical swings in premium travel demand.
Switching costs for hotel owners are moderate: while contracts can be long-term, owners may reflag properties if competing brands offer superior distribution, loyalty economics, or lower fees. Hyatt’s ability to sustain fee rate growth and expand its network depends on continued investment in brand, technology, and guest experience. The question is whether Hyatt can differentiate its platform enough to maintain pricing power and attract incremental hotel partners in a market where alternatives abound and the largest players wield significant negotiating leverage.
Hyatt’s positioning in the luxury and upper-upscale segments also exposes it to distinct demand elasticity characteristics compared to midscale or economy tiers. Premium travelers often exhibit greater sensitivity to macroeconomic cycles, geopolitical events, and discretionary spending trends, which can translate into sharper revenue swings during downturns. This cyclical sensitivity may amplify the volatility of fee income derived from these segments. Conversely, the brand’s emphasis on differentiated guest experiences, exclusivity, and loyalty incentives can foster customer stickiness and mitigate churn, supporting more stable occupancy and rate trends. Hyatt’s strategic challenge lies in balancing the pursuit of growth in these higher-margin segments with the inherent demand cyclicality and competitive intensity they entail.
Unlocking Operating Leverage Through Sustained Fee Expansion and Improved Working Capital
In a favorable scenario, Hyatt successfully accelerates fee growth by expanding its managed and franchised hotel base, driving higher RevPAR through rate discipline and loyalty program engagement, and leveraging digital investments to enhance guest and owner value. As incremental fee revenue carries high margins, this could translate into outsized EBITDA and net income gains, even if absolute revenue growth is modest.
Evidence confirming this scenario would include: sequential and year-over-year growth in fee revenue outpacing systemwide RevPAR gains; rising adjusted EBITDA margins; improvements in the current and cash ratios; and announcements of new management/franchise contracts or major loyalty partnerships. Falsification would be signaled by stagnating fee growth, persistent liquidity pressure, or loss of management/franchise share to competitors.
Balancing Fee Momentum with Tight Liquidity in a Choppy Demand Environment
The most plausible trajectory is that Hyatt maintains steady, if modest, fee growth as travel demand normalizes but remains susceptible to regional and segment volatility. Adjusted EBITDA tracks fee income, but revenue headwinds—whether from competitive pricing, geographic weakness, or macroeconomic uncertainty—limit upside.Liquidity ratios remain below 1.0, requiring close management of short-term obligations and reported liquidity metrics that do not by themselves establish potential financial flexibility.
Confirmation would come from quarterly reports showing stable fee growth, flat or slightly improving margin trends, and no material changes to risk factors or liquidity disclosures. Falsification would be evident if fee growth stalls, adjusted EBITDA margins compress, or working capital stress becomes acute, forcing asset sales or costly refinancing.
Liquidity Constraints Collide with Revenue Shortfalls: A Stress Scenario for the Asset-Light Model
In an adverse scenario, a combination of macroeconomic slowdown, travel demand shocks, or competitive loss triggers a sharp deceleration in fee growth or outright declines in managed/franchised hotel performance. As fee revenue is highly sensitive to occupancy and rate trends, adjusted EBITDA and net income could deteriorate rapidly. With current liabilities already exceeding current assets, Hyatt could face mounting pressure to meet short-term obligations, potentially requiring asset sales, expensive short-term borrowing, or dilutionary equity issuance.
Confirmation of this scenario would include declining fee and RevPAR metrics, negative working capital trends, rising short-term debt, or credit rating downgrades. Falsification would require evidence of resilient fee growth and working capital improvement even in a soft demand environment.
Milestones That Will Clarify the Resilience of Hyatt’s Fee Model and Balance Sheet
Quarter-over-quarter and year-over-year growth in fee revenue, especially relative to systemwide RevPAR and competitor benchmarks.
Adjusted EBITDA margin trends, as an indicator of incremental operating leverage from fee growth.
New management or franchise agreements announced, particularly in growth markets or with marquee hotel owners.
Working capital changes, including receivables collection cycles and payables management—if disclosed.
Retention and expansion rates within Hyatt’s managed/franchised hotel portfolio, which would indicate competitive stickiness.
Announcements of debt refinancing, credit facility changes, or asset dispositions, which could reshape the liquidity profile.
Travel demand indicators and macroeconomic signals in Hyatt’s core geographies, as these will directly impact fee pools and owner confidence.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments