
SLR Investment Corp.: Dividend Stability, Earnings Volatility, and the Limits of Visibility
SLR Investment Corp. reports positive net income and maintains dividend payments, but faces earnings volatility, limited financial disclosure, and market sentiment headwinds. The company's business model, capital requirements, and competitive positioning remain only partially visible, raising questions about the durability of returns and future growth scenarios.
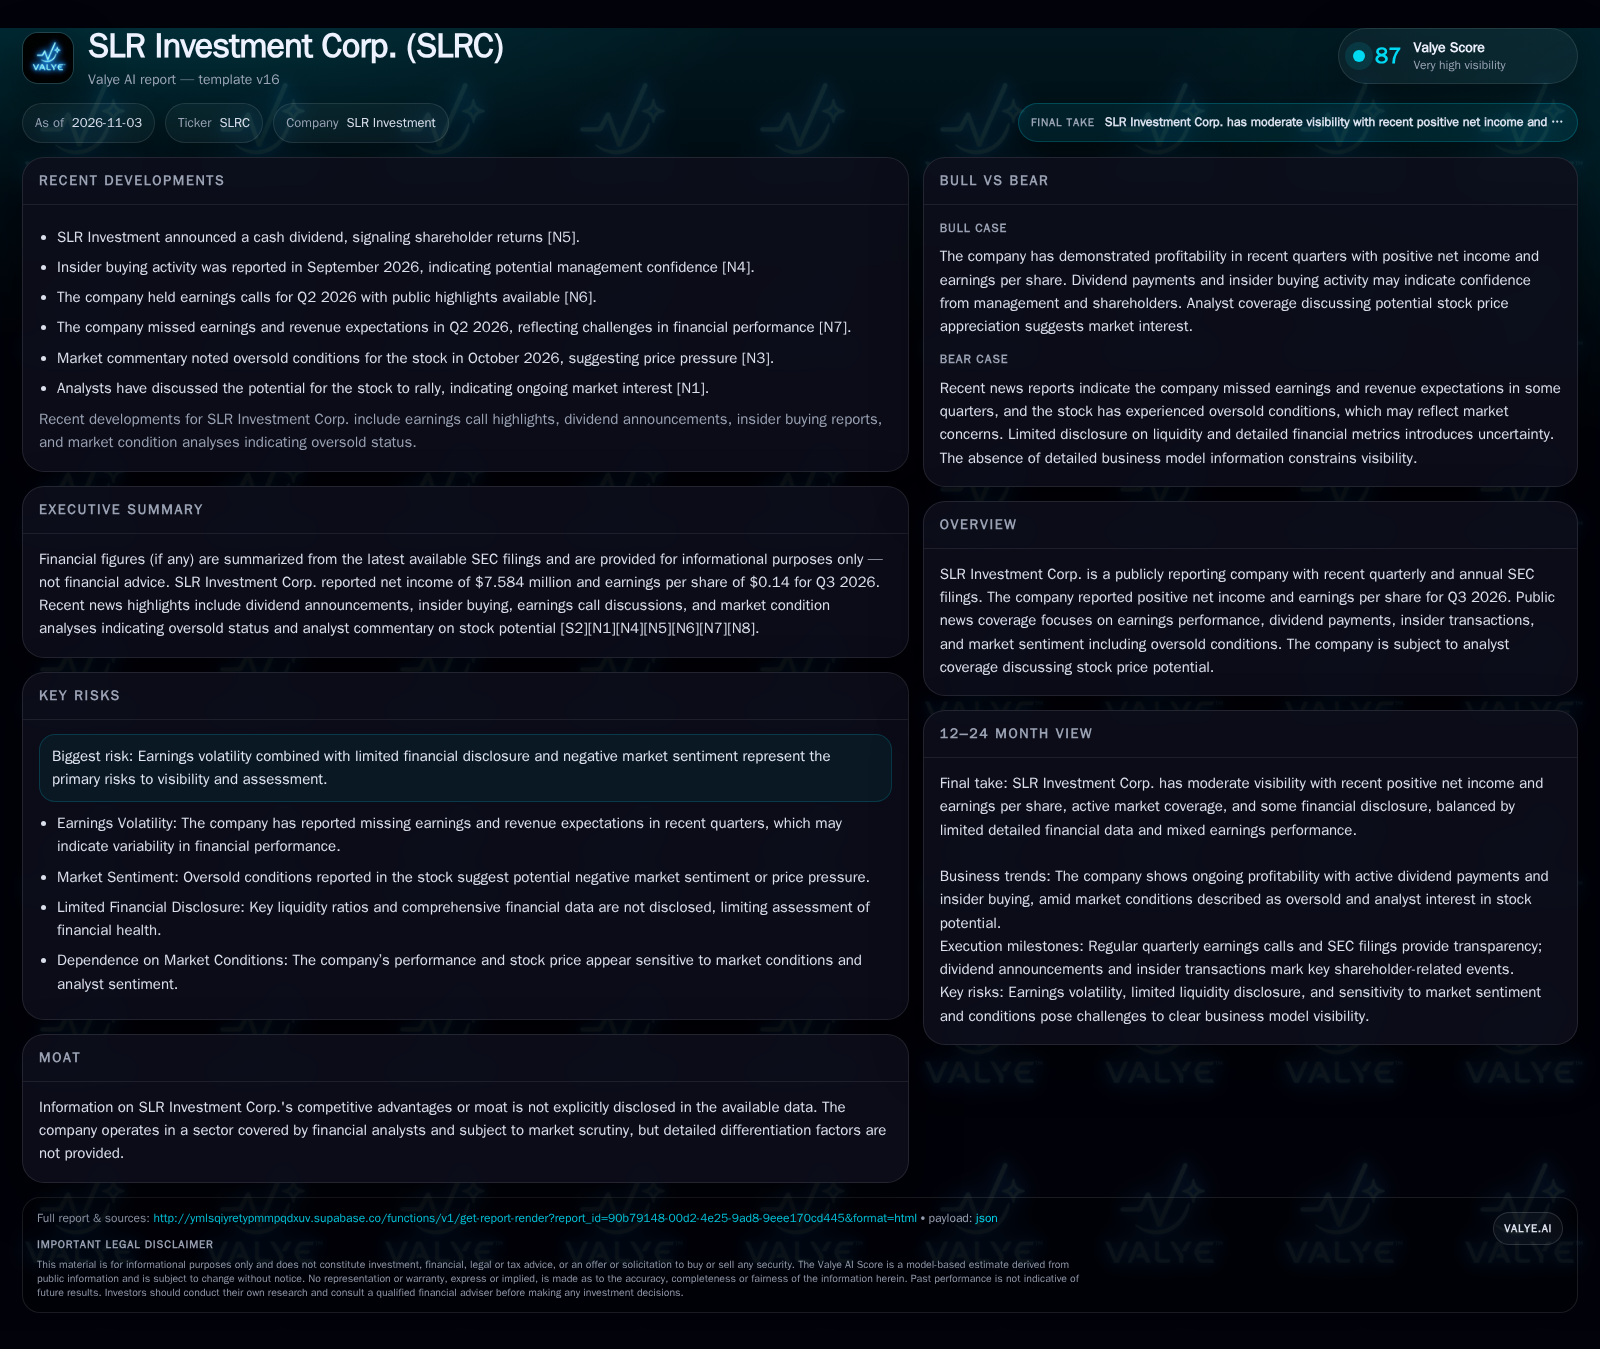
SLR Investment Corp. recently posted net income of $7.584 million with $0.14 EPS for Q3 2026 and announced a cash dividend, amid analyst coverage and insider buying activity. However, the company missed earnings and revenue expectations in Q2 2026 and faces market conditions described as oversold, with limited disclosure on liquidity and detailed business model mechanics. The interplay between short-term profitability, dividend continuity, and underlying risk factors will shape the forward thesis. [S2] [N1] [N3] [N4] [N5] [N7]
SLR Investment Corp. stands at a crossroads of apparent near-term profitability and persistent uncertainty. The cited source reports dividend-related activity; that disclosure alone does not establish dividend-policy continuity, management confidence, or a material constraint on capital flexibility. Market sentiment has been pressured, with analysts divided on the path forward and insider buying offering only a partial signal. Assessing SLR Investment’s future hinges on understanding not just headline results, but the economic levers, risk exposures, and competitive forces beneath the surface. [S2] [N1] [N3] [N4] [N5] [N7]
Recent Profitability and Dividend Actions Amid Mixed Market Signals
SLR Investment Corp. reported net income of $7.584 million and basic and diluted earnings per share of $0.14 for the quarter ended September 30, 2026 [S2]. This positive result follows a period where the company missed earnings and revenue expectations in Q2 2026, highlighting ongoing financial volatility [N7]. The cited source reports dividend-related activity; that disclosure alone does not establish dividend-policy continuity, management confidence, or a material constraint on capital flexibility. [N5] [N4] Market commentary in October 2026 described the stock as oversold, suggesting recent price pressure and investor caution [N3]. Collectively, these facts paint a picture of a company maintaining profitability and dividend payments but operating under a cloud of volatility and market skepticism.
Unpacking the Economics: How SLR Investment Corp. Could Create Value
SLR Investment Corp., by virtue of its name and reporting cadence, likely operates as a business development company (BDC) or similar specialty finance entity, but the available disclosures do not detail its specific business model. In general, BDCs generate income by investing in, lending to, or otherwise financing small and mid-sized businesses, earning spreads between funding costs and investment yields. Revenue streams typically include interest income, fees, and sometimes equity participation. Operating leverage can be significant if portfolio yields rise faster than funding costs, but can also cut the other way in adverse conditions.
Dividend payments are a hallmark of BDCs, often required to distribute the majority of taxable income to maintain favorable tax status. The sustainability of dividends depends on recurring net investment income, credit performance, and prudent leverage. Without detailed disclosures, it is unclear whether SLR Investment’s recent dividend is fully covered by core earnings or draws on capital gains or balance sheet reserves. The company’s missed earnings and revenue in Q2 2026 suggest that income generation can be inconsistent, potentially due to credit losses, non-accruals, or variable fee income [N7].
In sum, SLR Investment’s economics hinge on the stability and risk-adjusted yield of its investment portfolio, cost of funds, and the discipline of its capital allocation—factors not directly observable from the current reports.
Competitive Landscape: Navigating Yield Compression and Credit Risk
SLR Investment Corp. competes in a crowded specialty finance sector, where BDCs, private credit funds, and even traditional banks vie for deal flow and attractive yields. The primary competitive forces include access to low-cost capital, underwriting discipline, origination relationships, and risk management capabilities. In periods of abundant liquidity, yield compression can erode spreads as competition for borrowers intensifies. Conversely, in stressed environments, credit losses can surge, testing underwriting quality and capital buffers.
Switching costs for borrowers are generally low, as companies can shop for better rates or terms. However, for SLR Investment, the ability to differentiate may depend on sector specialization, speed of execution, or offering value-added services. Without specific disclosure of portfolio composition, customer concentration, or sector focus, it is difficult to assess whether SLR Investment has any durable competitive advantages or is more exposed to commoditized, price-driven competition.
Peer performance and market sentiment can also create relative pressure. Analyst coverage and market commentary suggest SLRC is being scrutinized for both its yield and risk profile [N1] [N3]. If sector peers exhibit stronger credit performance or more resilient dividend coverage, SLR Investment could face outflows or valuation discounts.
What Would Drive a Re-rating? Credit Stability and Improved Disclosure
A favorable scenario for SLR Investment Corp. would involve sustained or growing net investment income, supported by stable portfolio credit quality and disciplined capital allocation. Insider buying, as seen in September 2026, might be interpreted as a leading indicator if followed by improved earnings and robust dividend coverage [N4].
A critical lever would be enhanced financial disclosure, particularly around liquidity, leverage, and portfolio performance. If SLR Investment begins reporting detailed credit metrics, non-accrual rates, and coverage ratios, investors would have greater visibility into risk and the sustainability of returns. Confirmation of this upside scenario would include consecutive quarters of positive net income above dividend requirements, narrowing gap between reported and expected earnings, and stabilization or appreciation in the share price.
Falsification would come from renewed earnings misses, unexpected dividend cuts, or disclosure of material credit losses.
Balancing Yield and Risk: The Most Likely Trajectory
Absent a structural shift, the most plausible path for SLR Investment Corp. is continued modest profitability with intermittent earnings volatility. Dividend payments are likely to persist, but with the risk that coverage may intermittently fall short if credit costs or funding pressures rise. The company may maintain market interest due to its income profile, but valuation could remain subdued as long as detailed balance sheet and risk disclosures are lacking.
Analyst coverage and insider buying may provide intermittent support, but without a step-change in transparency or operating performance, the company’s shares may trade in line with sector averages or modest discounts reflecting uncertainty [N1] [N4].
Evidence against this scenario would be either a clear upward inflection in reported earnings/dividends or, conversely, a sharp deterioration in credit quality or dividend cuts.
Dividend at Risk: The Consequences of Credit Deterioration and Funding Pressure
The adverse scenario for SLR Investment Corp. is driven by persistent or worsening credit quality in its investment portfolio, leading to rising non-accruals, write-downs, and net investment income falling below dividend requirements. If funding costs rise—due to higher rates or tighter capital markets—net spreads could compress further.
A lack of detailed liquidity and leverage disclosure compounds the risk, as investors may assume the worst in the absence of transparency. Negative analyst commentary and repeated oversold market conditions could exacerbate outflows and valuation pressure [N1] [N3].
This scenario would be confirmed by additional quarters of earnings misses, a dividend reduction, or sudden disclosures of credit events. It would be partially falsified if the company demonstrates stable credit performance and maintains dividend coverage despite broader sector headwinds.
Testing the Durability of SLR Investment Corp.’s Return Profile
Quarterly net investment income and whether it consistently exceeds dividend distributions (if disclosed) would help assess dividend sustainability.
Trends in non-accruals, credit losses, or portfolio impairments—should future filings provide these details—would be crucial for gauging risk.
Earnings call commentary or new SEC filings detailing portfolio composition, sector exposures, or concentration risk would help validate the business model.
Market sentiment indicators, such as shifts from oversold to neutral or positive territory, may reflect changing investor perceptions [N3] [N8].
Evidence of further insider buying or, conversely, insider selling could provide incremental insight into management’s view of risk and opportunity [N4].
Sector peer results and analyst commentary may help contextualize SLR Investment’s performance relative to competitors and broader credit markets [N1].
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments