
Goldman Sachs Physical Gold ETF: Low-Fee Bullion Exposure in an Intensifying ETF Price War
AAAU’s cost advantage and direct physical gold backing attract price-sensitive investors, but scale-driven liquidity, competitive fee compression, and gold price volatility remain central to its long-term relevance.
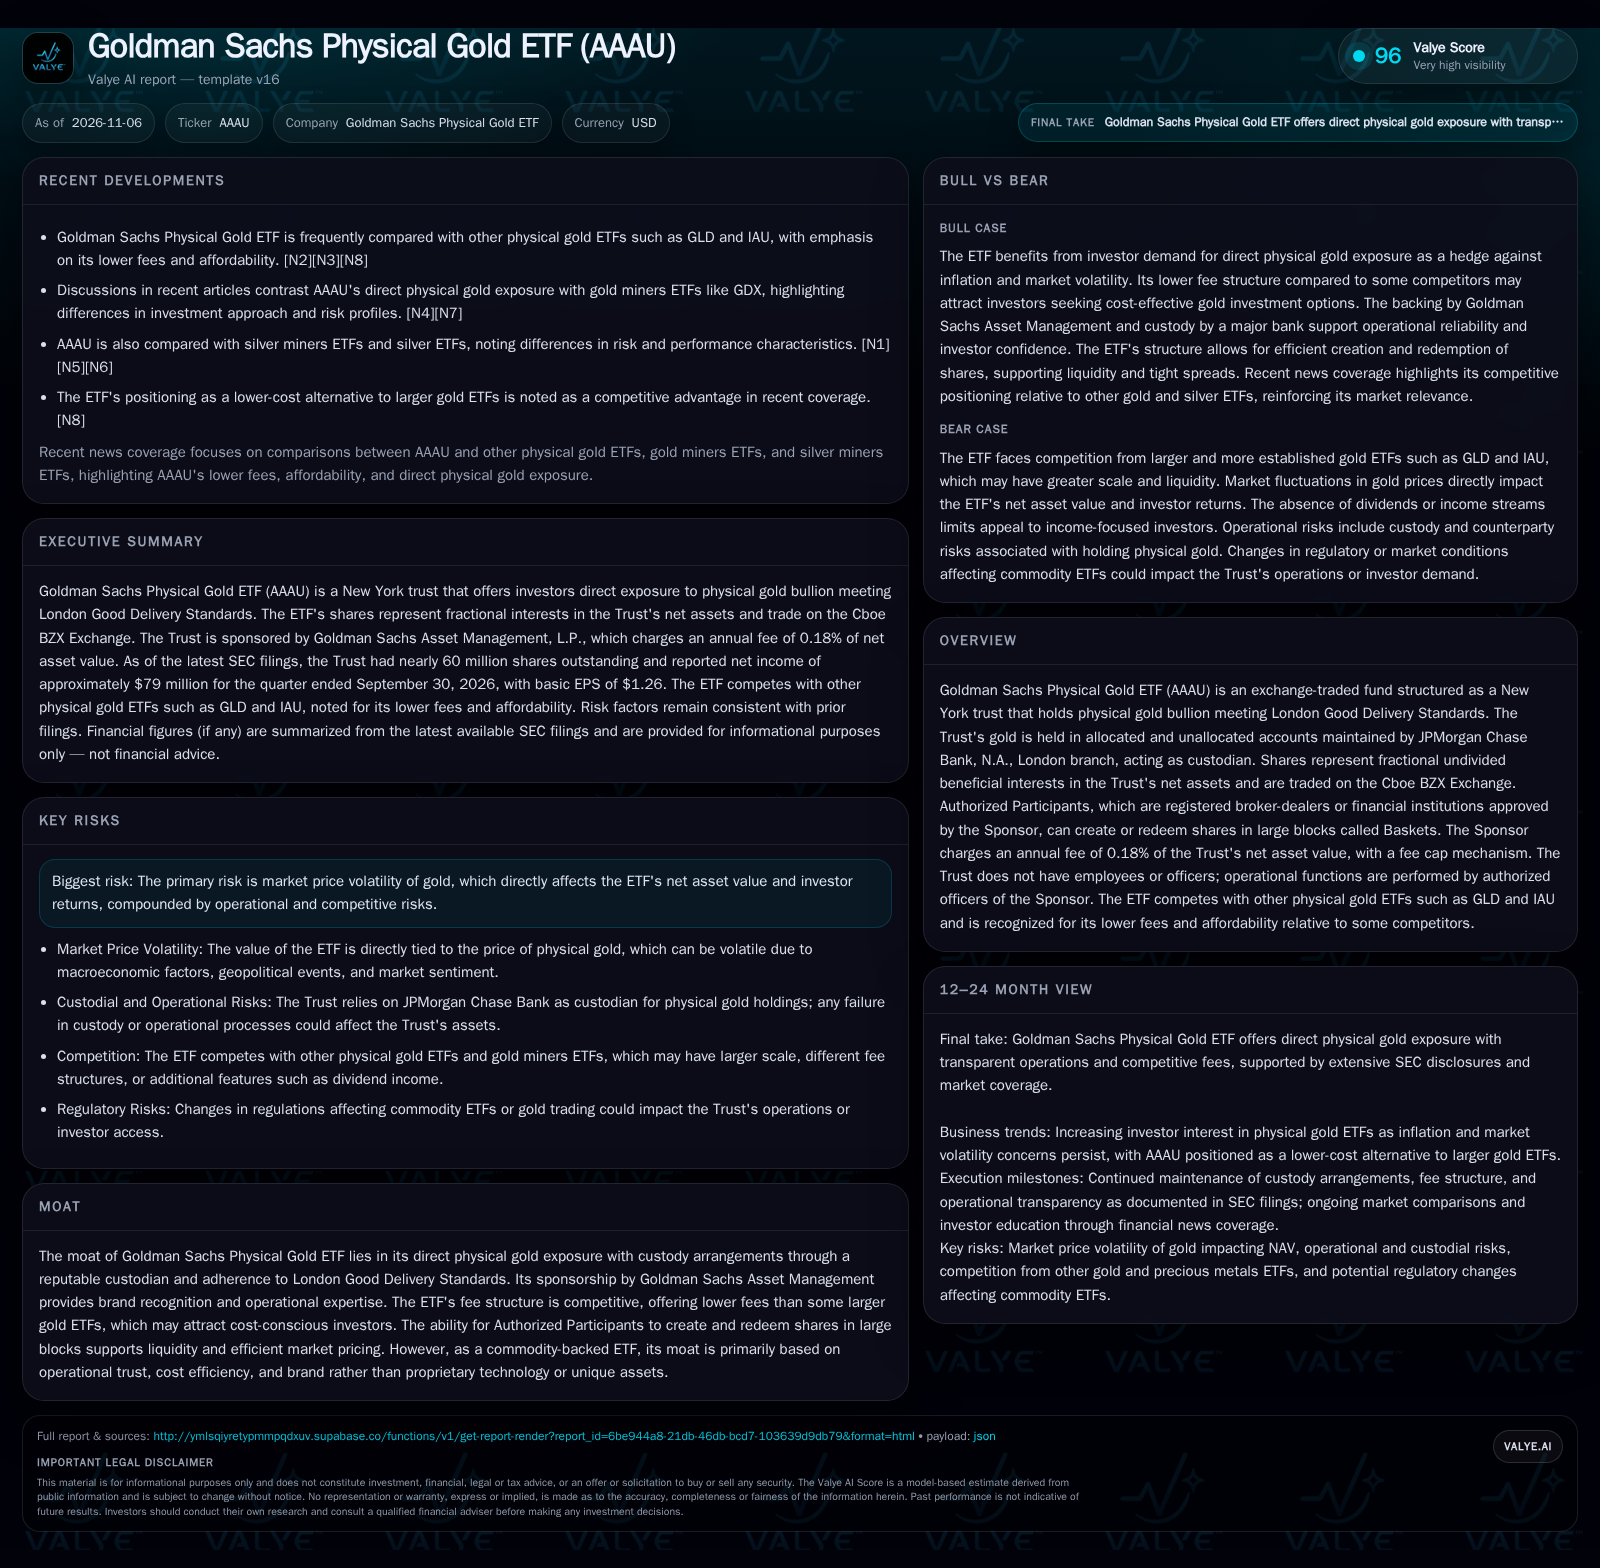
Goldman Sachs Physical Gold ETF (AAAU) reported 59.8 million shares outstanding at year-end 2025 and $79.2 million in quarterly net income as of September 2026. The ETF is structured as a New York trust, holds physical gold in custody at JPMorgan, and charges a 0.18% annual fee—lower than some larger rivals. Fee competitiveness and operational transparency are key differentiators, but competition from established gold ETFs, gold miners ETFs, and market volatility affect its growth trajectory. Risk factors and fee structures remain stable, while the ETF’s ability to sustain share creation/redemption and attract inflows will determine its place in the evolving gold investment landscape. [S1] [S2] [N2] [N3] [N8]
Goldman Sachs Physical Gold ETF (AAAU) occupies a distinctive niche in the gold investment landscape. By offering direct exposure to physical gold at a lower fee than many established competitors, AAAU appeals to cost-sensitive investors seeking to hedge against inflation and market turmoil. Its structure as a trust with physical bullion custody, combined with transparent operations and the backing of Goldman Sachs Asset Management, underpins its credibility. However, the ETF’s long-term value proposition will be shaped by its ability to scale amid fierce competition, persistently low fees, and the unpredictable dynamics of the gold market.
Recent Performance and Positioning: What Sets AAAU Apart Now
As of December 31, 2025, Goldman Sachs Physical Gold ETF (AAAU) had 59,804,722 shares outstanding, and for the quarter ended September 30, 2026, it reported net income of $79,175,540, translating to basic earnings per share of $1.26. During that quarter, the Trust redeemed 12 Baskets (300,000 shares) at an average price of $40.71 per share. The ETF’s assets are held in physical gold bullion meeting London Good Delivery Standards, with JPMorgan as custodian. Notably, AAAU’s annual sponsor fee is 0.18% of net asset value—lower than many competing gold ETFs. This cost positioning, combined with the operational transparency and brand support from Goldman Sachs Asset Management, is frequently cited in recent news as a differentiator, appealing to investors seeking direct bullion exposure without high expense drag. [S1] [S2] [N2] [N3] [N8]
How Fee Compression and Asset Scale Shape Profitability
AAAU’s revenue model is straightforward: it collects a 0.18% annual fee on net asset value, accrued daily and paid monthly. This structure means that the fund’s economics are directly tied to both the price of gold and its total assets under management. Operating costs are streamlined, as the Trust has no employees or officers; all functions are provided by the Sponsor, whose economies of scale and operational leverage are critical in a low-fee environment. The main expenses are custody (JPMorgan), audit, insurance, and regulatory compliance—mostly fixed or semi-fixed per ounce or per dollar of gold held.
As a commodity ETF, AAAU’s margins are thin by design, with profitability driven by asset scale rather than high fees. The capital intensity is low, as the Trust only purchases gold to match inflows and redeems gold on outflows; no leverage or active management is involved. This model limits downside operating risk but also means that fixed costs must be spread over a large asset base to achieve meaningful profitability. The presence of a fee cap mechanism further constrains the Sponsor’s upside if assets surge. If AAAU can capture significant inflows, operating leverage would improve, but in a price war environment, any further fee reduction could squeeze margins and test the sustainability of this model.
Competing for Inflows: Can Fee Advantages Outweigh Liquidity and Brand Gaps?
AAAU’s primary rivals are the SPDR Gold Shares (GLD) and iShares Gold Trust (IAU), both of which dominate the gold ETF landscape in assets, liquidity, and brand recognition. AAAU’s 0.18% fee is below GLD’s and competitive with IAU’s, positioning it as a cost-effective alternative. Recent news coverage underscores AAAU’s appeal to price-sensitive investors and those seeking direct bullion exposure versus the operating risks and equity beta of gold miners ETFs such as GDX. [N2] [N3] [N4] [N8]
However, scale and trading liquidity matter for institutional allocators and active traders; GLD and IAU typically offer tighter bid-ask spreads and deeper secondary market liquidity. AAAU’s ability to grow assets may be constrained if it cannot match this depth, especially during periods of market stress when liquidity premiums matter most. Additionally, while brand trust is supported by Goldman Sachs’ sponsorship, long-term investors may prefer established incumbents with track records going back decades. Substitution risk is high, as all physical gold ETFs offer nearly identical economic exposure, making fee differentials, sponsor reputation, and liquidity the primary battlegrounds.
If Gold Inflows Accelerate and Fee Sensitivity Rises, AAAU Could Gain Market Share
The most favorable scenario for AAAU is one in which investor demand for physical gold surges—driven by inflation concerns, geopolitical instability, or a renewed focus on real assets—and cost sensitivity becomes paramount. In this environment, AAAU’s lower sponsor fee would attract incremental inflows from both retail and institutional investors seeking to minimize expense drag. As assets under management grow, the ETF could achieve greater operating leverage, further enhancing its profitability and narrowing the bid-ask spread as secondary market liquidity deepens.
Confirmation would come from sustained net inflows, rising share issuance, and a reduction in AAAU’s trading spread relative to GLD/IAU. Additional evidence would include increased mentions in institutional asset allocation reports and more broker-dealers joining as Authorized Participants, expanding market access. Falsification would occur if, despite a strong gold market, AAAU’s asset base stagnates or its secondary market liquidity fails to improve, suggesting that fee compression alone is insufficient to drive scale.
Steady-State: Fee Competition Persists, but Scale Remains Modest
The most plausible path is that AAAU continues to serve as a lower-cost option within a crowded gold ETF market, attracting incremental inflows from price-conscious investors but not unseating the scale leadership of GLD or IAU. Its assets fluctuate with gold prices and episodic investor risk appetite, while the 0.18% fee remains competitive but not uniquely disruptive. Share creation and redemption continue to function smoothly, with operational stability and transparent disclosures underpinning investor trust.
Evidence confirming this scenario would include stable or gradually rising assets under management, persistent but modest net inflows, and ongoing media coverage comparing AAAU’s fees to those of its peers. Falsification would occur if AAAU either rapidly gains market share (indicating a shift to the upside scenario) or suffers persistent outflows or operational issues (tilting toward the downside).
Liquidity and Fee Compression Risks: When Lower Cost Fails to Compensate for Scale
A negative trajectory could materialize if large gold ETFs aggressively cut fees, eroding AAAU’s cost advantage and reinforcing their dominance through superior liquidity and scale. In such a scenario, AAAU could face persistent outflows as investors consolidate assets in the largest, most liquid vehicles, especially during periods of elevated volatility when execution risk becomes paramount. If AAAU’s asset base falls below a critical threshold, operating leverage would deteriorate, and the fund might struggle to cover fixed costs or maintain tight spreads.
Downside confirmation would be visible in consistent net outflows, widening bid-ask spreads, and declining share creation/redemption activity. News coverage highlighting fee cuts by GLD or IAU, or concerns about AAAU’s trading liquidity, would further support this scenario. Falsification would require evidence of fee discipline among incumbents or AAAU’s ability to retain and grow assets despite intense price competition.
Milestones and Metrics That Will Shape AAAU’s Competitive Trajectory
Net asset inflows or outflows over rolling quarters—sustained inflows would indicate traction with investors, while persistent outflows would suggest fee advantage is not translating into market share.
Bid-ask spread and average daily trading volume—if disclosed—relative to GLD and IAU; narrowing spreads and rising liquidity would signal improving competitiveness.
Fee changes by major gold ETF competitors; any reduction by GLD or IAU could compress AAAU’s relative advantage.
Authorized Participants roster expansion or contraction—a broader AP base would support creation/redemption efficiency and secondary market liquidity.
Coverage in institutional asset allocation reports or model portfolios—greater inclusion would validate acceptance among sophisticated investors.
Gold price volatility and its impact on share creation/redemption activity—would help test the resilience of AAAU’s operational model under stress.
Operational or custody incidents, if any, involving the Trust or its service providers—as these would directly affect investor confidence and trust in the ETF’s structure.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments