
American Battery Technology: Integrated Recycling and Extraction Ambitions Confront the Realities of Scale and Capital
American Battery Technology Company is positioning itself at the nexus of domestic battery metals supply, leveraging proprietary recycling technology and primary resource exploration to address U.S. supply chain vulnerabilities. The company's operational progress and export milestones highlight potential, but persistent losses, execution risk, and reliance on external funding underscore the challenges of scaling a capital- and technology-intensive business.
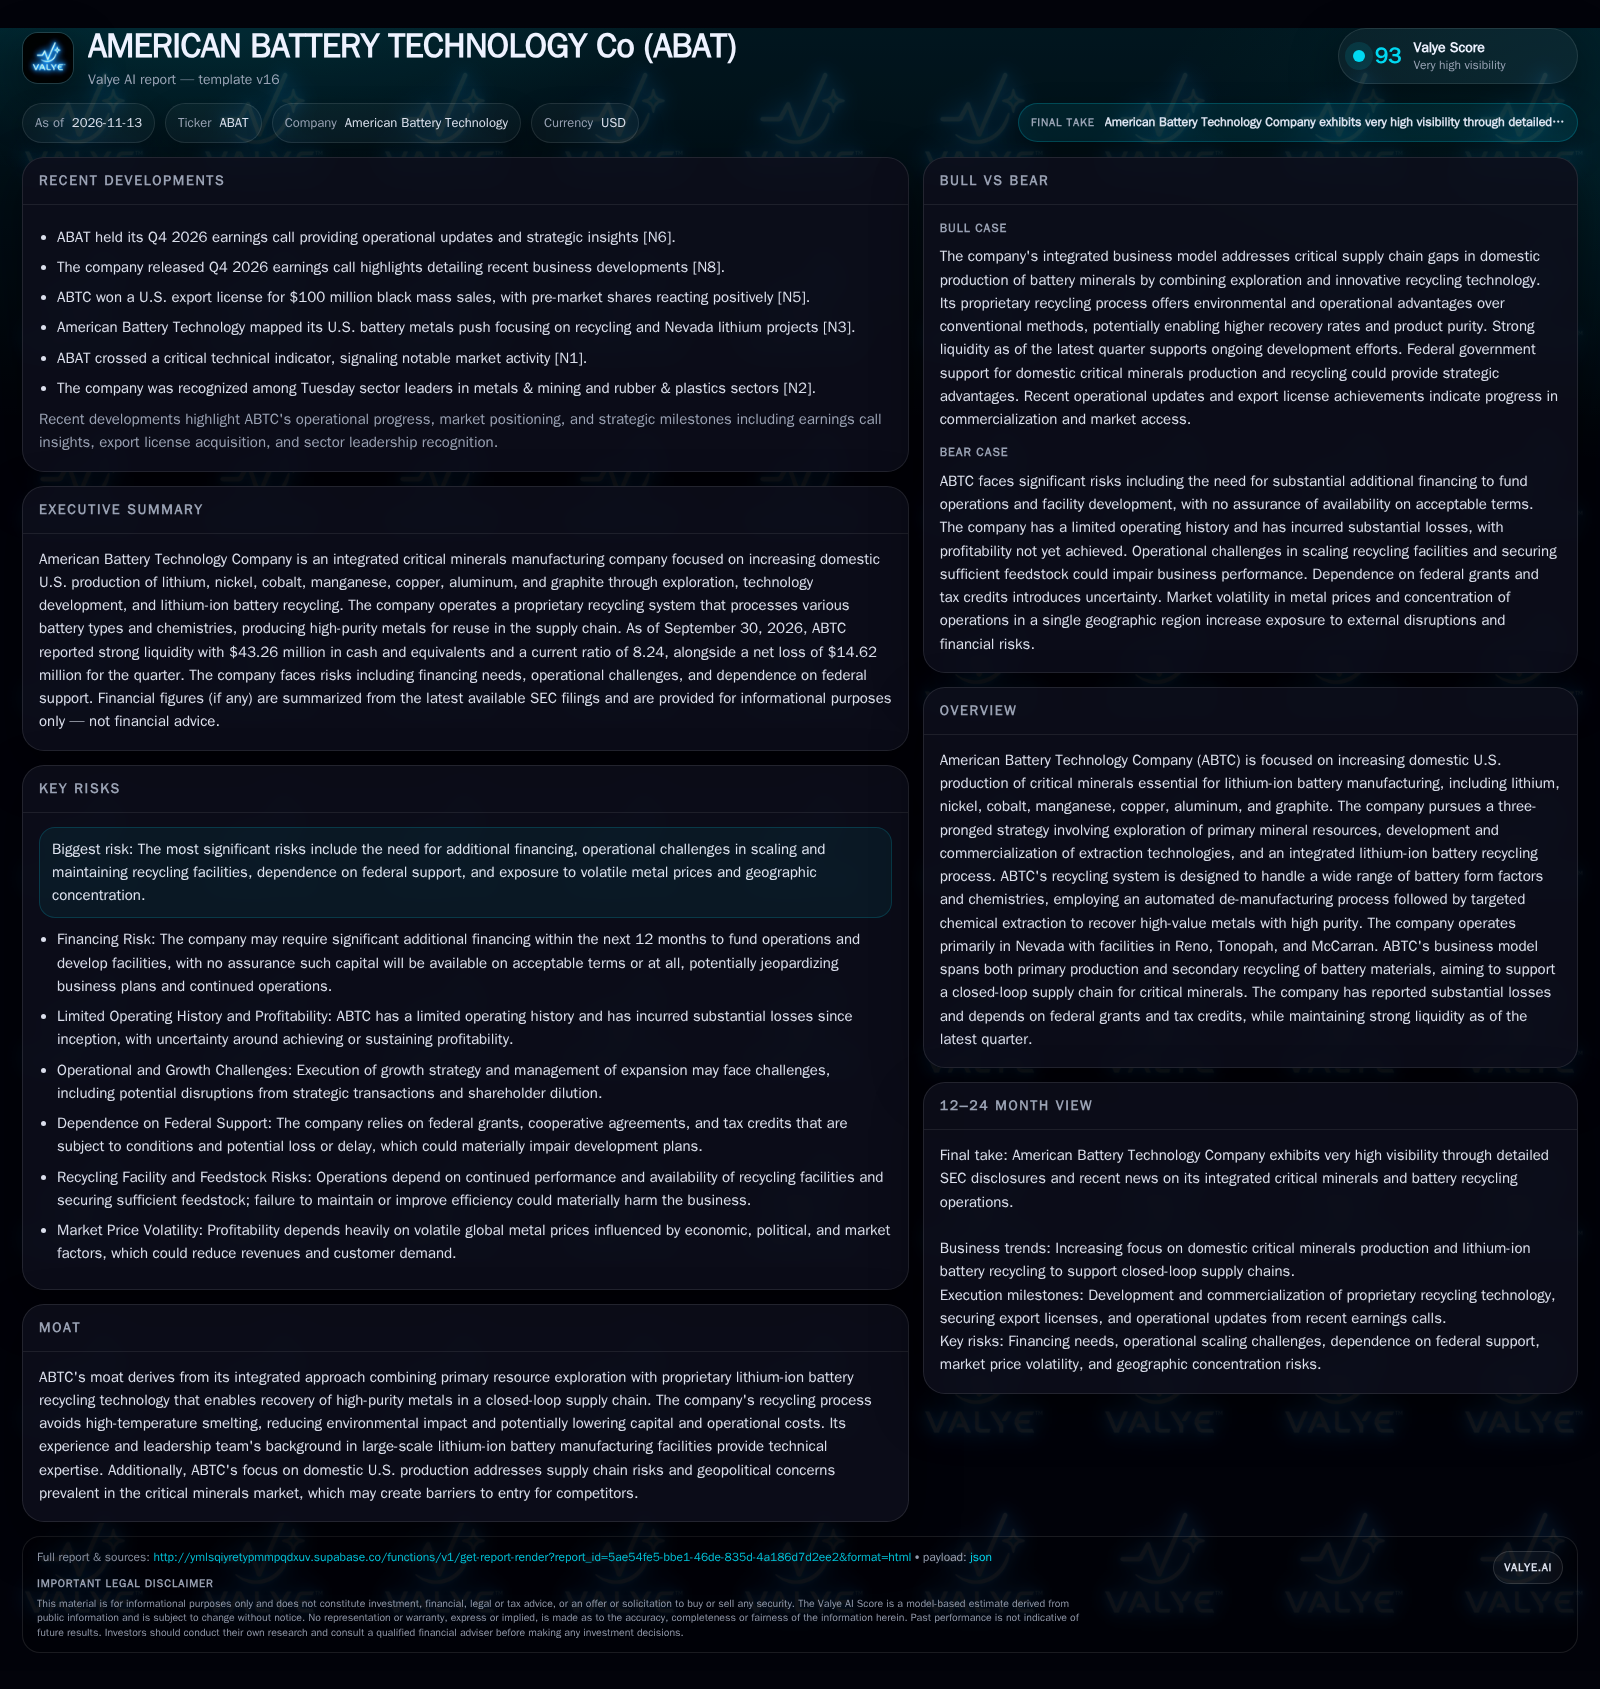
American Battery Technology Company (ABTC) is advancing a vertically integrated strategy that combines lithium-ion battery recycling with primary resource development in Nevada. Recent operational updates show technical and commercial progress, including a $100 million export license for black mass sales, but the company continues to post significant losses and faces material risks around financing, operational scaling, and market volatility. The near-term outlook hinges on ABTC's ability to demonstrate reliable facility throughput, secure feedstock, and convert technical milestones into recurring, profitable revenue streams. [S1] [S2] [N3]
American Battery Technology Company is taking a bold approach to solving one of the most pressing challenges in the U.S. energy transition: secure, sustainable supply of battery-grade metals. By marrying proprietary lithium-ion battery recycling with primary mineral extraction, ABTC aims to create a closed-loop, domestic supply chain for critical materials like lithium, nickel, and cobalt. Recent technical and commercial milestones underscore the company's progress, including a sizable export license for recycled black mass. Yet, persistent operating losses and heavy reliance on external funding spotlight the steep economic and operational hurdles still ahead.
Recent Milestones and Financial Position: Progress Meets Persistent Losses
American Battery Technology Company is executing a strategy that combines primary resource development with a proprietary, environmentally conscious lithium-ion battery recycling process. The company's Nevada-based operations are designed to address supply chain gaps for critical battery minerals in the U.S. [S1].
As of September 30, 2026, ABTC reported $43.26 million in cash and equivalents, with current assets of $51.19 million and current liabilities of $6.21 million. This results in a reported current ratio of 8.24 and a cash ratio of 6.97 [S2].
Despite these liquidity metrics, the company posted a net loss of $14.62 million for the quarter, continuing a pattern of substantial operating losses [S2].
Operationally, ABTC has secured a U.S. export license for $100 million in black mass sales, marking a significant step toward commercializing its recycling output and demonstrating market traction for its recovered materials [N3].
How ABTC’s Integrated Model Could Capture Value—And Where Margin Pressure Lurks
ABTC’s business model aims for vertical integration across the battery materials value chain: from mining and extraction of primary resources to recycling spent lithium-ion batteries. The company’s proprietary recycling process is designed to handle a wide variety of battery chemistries and form factors, using automated de-manufacturing and targeted chemical extraction. This approach seeks to recover high-purity metals while minimizing environmental impact by avoiding high-temperature smelting [S1].
Economically, the model could benefit from dual revenue streams: sales of recycled metals (secondary production) and sales or tolling of extracted primary minerals. The export license for black mass suggests early commercial validation on the recycling side [N3]. However, the economics of battery recycling and mineral extraction are both capital-intensive and operationally complex, with significant fixed costs for facility construction, technology development, and regulatory compliance.
Variable costs are driven by feedstock acquisition (for recycling), labor, reagents, and utility inputs. The recycling process’s environmental efficiency could confer a cost advantage over traditional smelting, but large-scale profitability depends on reliable facility throughput, stable feedstock supply, and favorable metal pricing. Operating leverage is plausible if ABTC can ramp volumes, but the need for ongoing R&D and regulatory costs could keep margins under pressure, especially in the near-to-intermediate term.
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2]
Can Proprietary Recycling and Domestic Focus Build a Defensible Edge?
The U.S. battery metals supply chain remains heavily dependent on overseas sources, particularly for lithium, nickel, and cobalt. ABTC’s integrated approach—combining domestic resource development with advanced recycling—directly targets this vulnerability. The company’s proprietary recycling technology, which avoids high-temperature operations and claims high-purity output, could offer both environmental and operational differentiation within the competitive set [S1].
Potential competitors include established mining companies, traditional metal recyclers, and emerging battery recycling startups—some of which may have deeper capital reserves, larger feedstock contracts, or more mature commercial relationships. The ability to process a wide range of battery chemistries is a potential advantage, but it remains to be seen whether ABTC’s process can consistently deliver on cost, scale, and purity requirements at commercial volumes.
Switching frictions for customers may be moderate: battery manufacturers and end-users are primarily concerned with cost, reliability, and purity of supplied materials. If ABTC’s recycled metals can be qualified for direct reuse in battery manufacturing, this could create sticky customer relationships and could support premium pricing. However, the threat of technology substitution—such as direct-to-cathode recycling or alternative battery chemistries—remains a long-term competitive consideration.
The company’s geographic concentration in Nevada offers proximity to U.S. battery manufacturing growth, but also exposes ABTC to localized operational risks.
If Facility Scale-Up and Market Acceptance Accelerate, Closed-Loop Economics Could Materialize
In the most favorable scenario, ABTC successfully ramps its Nevada recycling facility to high utilization, consistently producing battery-grade metals at scale. The $100 million export license for black mass sales could signal the beginning of recurring, meaningful revenue streams if repeat orders and long-term offtake agreements materialize [N3].
If the company’s proprietary process continues to demonstrate lower environmental impact and high recovery rates, ABTC could secure premium customer relationships with automakers, battery manufacturers, and electronics recyclers seeking reliable, sustainable domestic supply.
A virtuous cycle could emerge: reliable recycling throughput attracts feedstock contracts, which in turn drive volume and cost efficiencies, supporting higher margins and funding further expansion. If federal support remains robust and ABTC leverages its technology for licensing or joint ventures, the company could achieve positive operating leverage and approach profitability.
Evidence for this scenario would include: multi-year supply agreements, rising facility throughput, narrowing operating losses, validation of recycled product quality by major battery manufacturers, and additional export or domestic sales milestones.
Execution Complexity and Market Forces Likely to Prolong the Path to Profit
The most plausible near-term trajectory is one of gradual operational improvement and incremental commercial progress, but with continued financial losses and episodic funding needs. ABTC’s recycling facility may achieve steady but suboptimal throughput, constrained by feedstock availability, technical hiccups, or regulatory bottlenecks.
Revenues from black mass or recycled metals may be lumpy, dependent on spot market pricing and the pace of customer qualification.
Market acceptance of ABTC’s recycled metals may proceed cautiously, with battery manufacturers requiring extensive validation and qualification periods before committing to significant offtake. Competition from larger or more established players could pressure pricing and limit margin expansion.
Evidence confirming this scenario would include: continued operating losses, modest revenue growth, periodic equity or grant financings, and incremental rather than transformative customer wins. Falsification would require a step-change in facility throughput, recurring multi-year contracts, or a sharp turn to profitability.
Adverse Outcomes if Scale, Funding, or Feedstock Falter
In a less favorable scenario, ABTC fails to achieve reliable commercial-scale throughput at its recycling facility, either due to technical setbacks, supply interruptions, or regulatory non-compliance. If feedstock supply proves inconsistent or recycling economics deteriorate due to falling metal prices, the company may struggle to generate sustainable revenue.
Persistent operating losses would erode the current liquidity cushion, especially if external funding becomes more expensive or unavailable. Delays or failures in federal grant renewals, or a shift in policy priorities, could further strain the balance sheet.
Operational setbacks—such as accidents, environmental incidents, or equipment failures—could trigger regulatory penalties, reputational damage, and customer attrition. In this scenario, ABTC could face shareholder dilution, asset sales, or even restructuring if capital needs outpace funding access.
Confirmation of the downside case would be signaled by missed throughput or revenue milestones, withdrawal of federal support, escalating losses, or visible feedstock supply disruptions. Falsification would require evidence of consistent, profitable operations and resilient funding access even under adverse market conditions.
Milestones and Metrics to Gauge ABTC’s Transition from Promise to Profit
Quarterly facility throughput (tons of batteries processed and metals recovered); a useful metric would be consistent ramp-up toward nameplate capacity, if disclosed.
Recurring revenue growth and composition—especially the proportion tied to multi-year contracts versus spot or one-off sales.
Gross margin and operating cash flow trends as indicators of improving process economics and cost discipline.
Feedstock supply agreements: length, volume, and counterparty quality, if disclosed, to assess security of inputs.
Product qualification milestones with major battery or automotive OEMs, as evidence of market acceptance and potential for sticky customer relationships.
Updates on federal grant renewals, new tax credits, or policy support, given the company’s reliance on government incentives.
Capital expenditure commitments and funding sources for facility expansion or technology scale-up.
Any operational incidents, regulatory actions, or safety disclosures that could affect facility continuity, cost structure, or reputation.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments