
ADM Endeavors: Facility Expansion, Government Contract Growth, and the Challenge of Scaling Profitably
The company’s vertical integration and focus on in-house branding are strategic levers, yet execution and working capital risks loom large as it seeks to capture market share amid industry disruption.
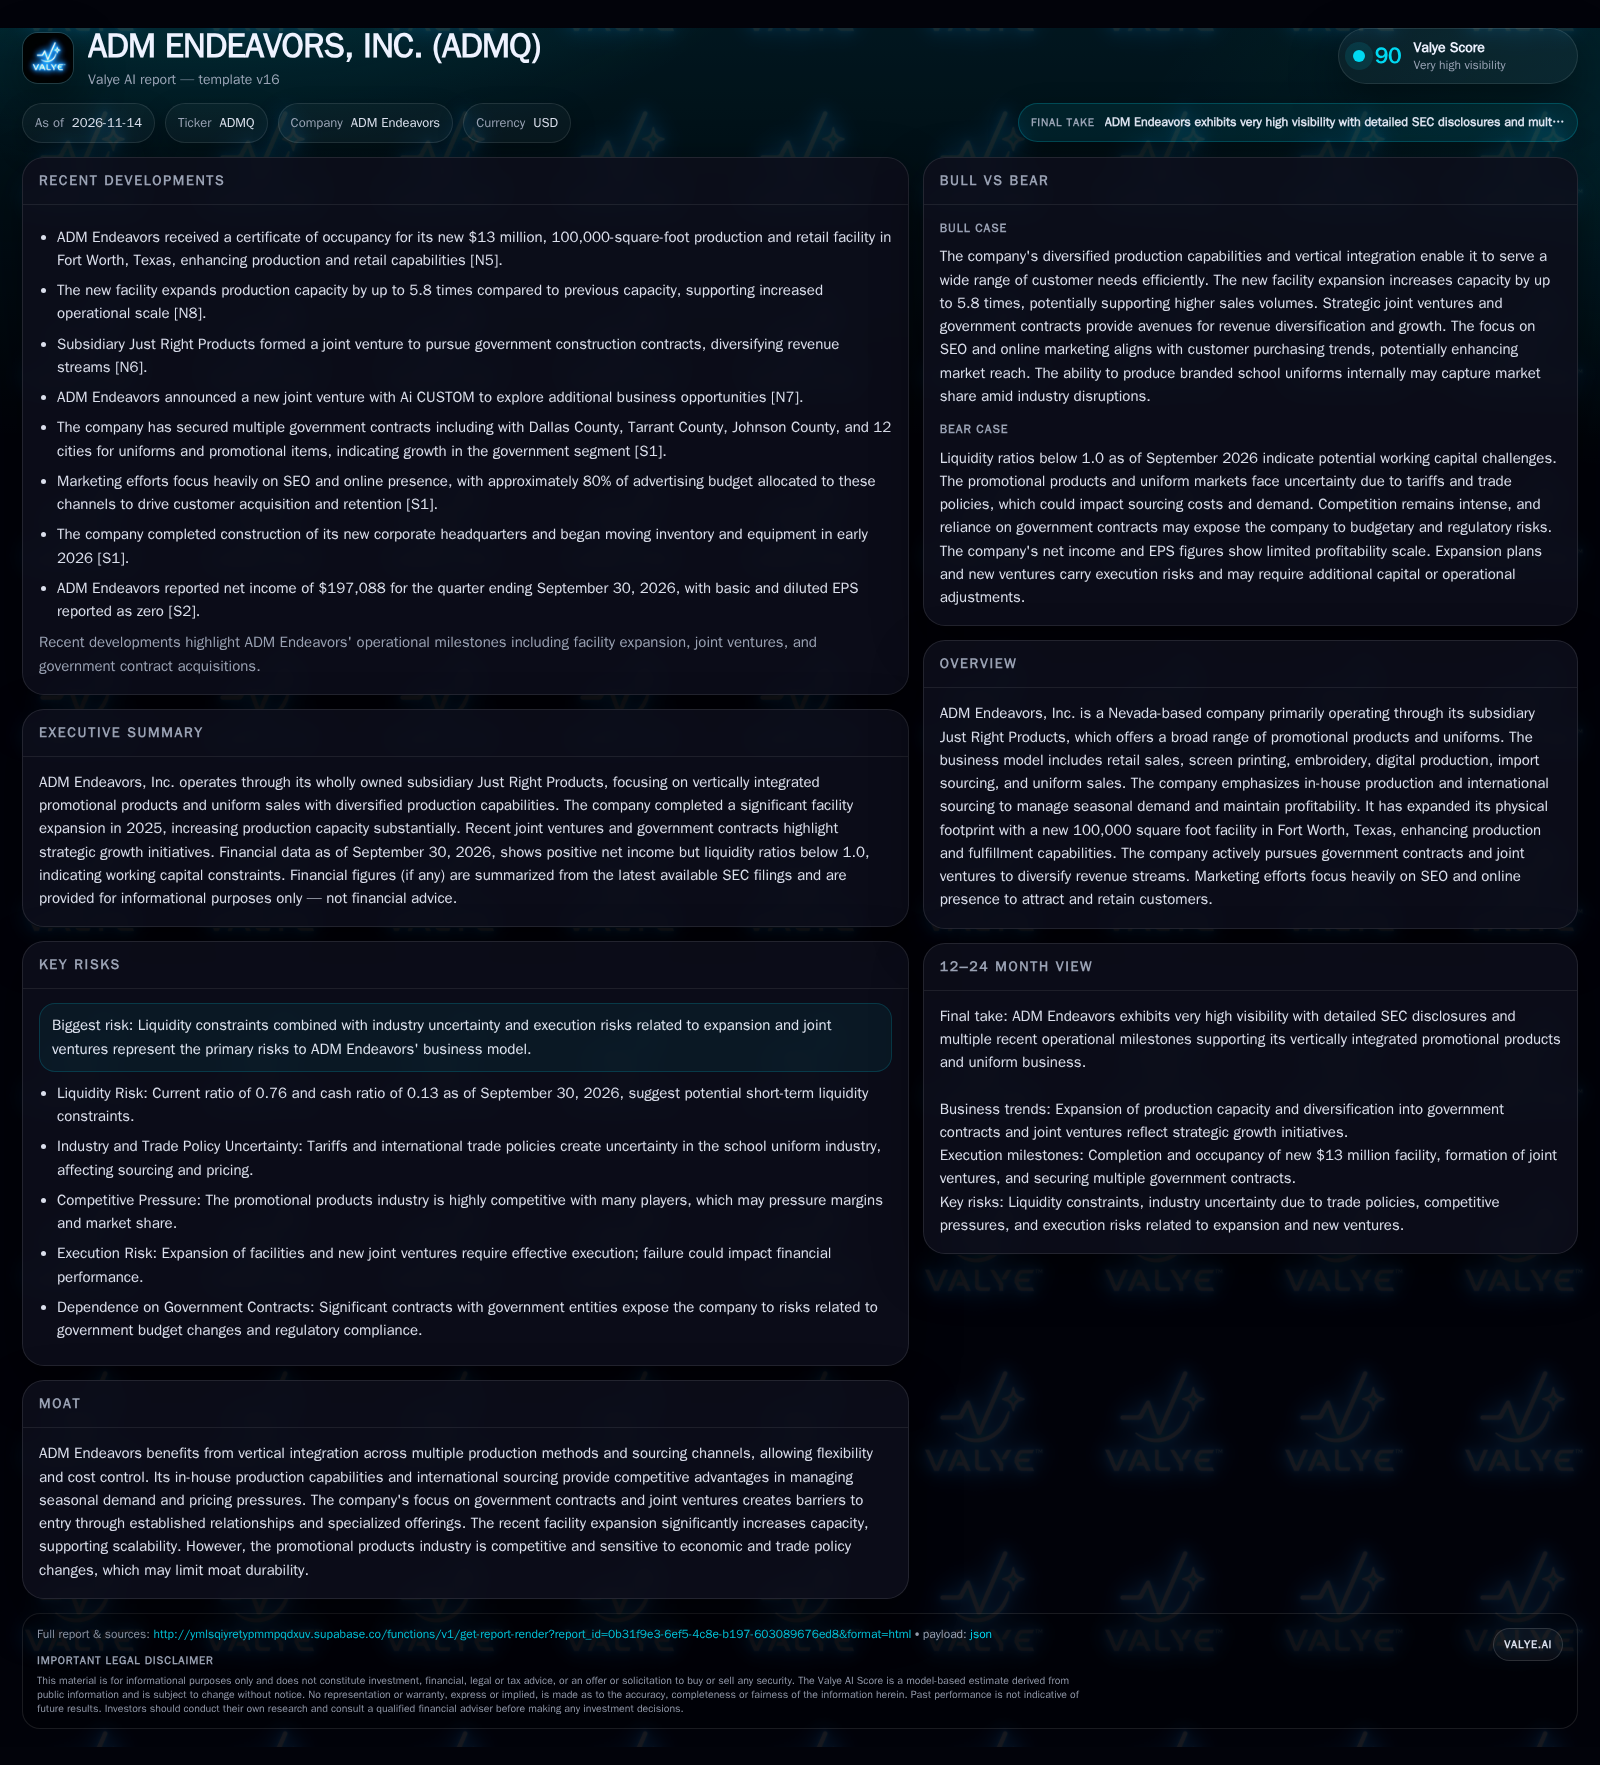
ADM Endeavors, through its subsidiary Just Right Products, has completed a major facility expansion and grown its government contract base. The company’s vertically integrated model and digital marketing focus could drive volume and margin gains, but below-par liquidity ratios and industry uncertainty raise questions about the sustainability of its growth trajectory. Execution on new capacity and ventures, as well as effective working capital management, will be critical to realizing upside.
ADM Endeavors has transformed its operational footprint with a $13 million investment in a new corporate headquarters and expanded production facility, amplifying its ability to serve a growing roster of government and institutional customers. With a vertically integrated model spanning design, production, and international sourcing, the company is positioned to capitalize on market disruptions—particularly in the school uniform sector. The next phase will test whether expanded capacity and strategic contracts can translate into durable, profitable growth.
Recent Milestones: Capacity Expansion and Government Contract Wins
ADM Endeavors has completed a $13 million, 100,000-square-foot headquarters and production facility in Fort Worth, Texas, which expands production capacity by up to 5.8 times and introduces a fulfillment center to enhance inventory and service levels [N5] [S1]. This physical expansion is paired with operational milestones, including the securing of multiple government contracts with counties and municipalities for uniforms and promotional items [S1]. The company reported net income of $197,088 for the quarter ending September 30, 2026, but with a current ratio of 0.76 and cash ratio of 0.13, liquidity remains a point of concern [S2]. The formation of new joint ventures—most notably with Ai CUSTOM—signals an appetite for diversification and growth beyond core product lines [N7].
How the Model Scales: Vertical Integration, Production Leverage, and Margin Dynamics
ADM Endeavors’ economics are defined by its vertically integrated approach: retail sales, screen printing, embroidery, digital production, and international sourcing are all housed within its Just Right Products subsidiary. This model allows the company to control costs, shorten lead times, and customize products for diverse clients, including government, schools, and businesses. The new facility dramatically increases production headroom, with screen printing, embroidery, and digital departments operating well below full capacity, suggesting the company can grow revenue without immediate incremental capital outlay for core equipment [S1].
However, scaling production does not guarantee margin expansion if fixed costs rise faster than absorption, or if pricing power is limited by competitive pressures. The company’s heavy investment in SEO and digital marketing (80% of advertising spend) may lower customer acquisition costs if online channels convert efficiently, but the return on this spend will depend on order volume, retention, and average contract size—metrics not yet disclosed. The economics of government contracts can be attractive due to volume, but may carry lower margins and slow payment cycles, placing additional stress on working capital. The company’s current liquidity ratios suggest that funding growth and managing inventory for seasonally driven segments (like school uniforms) could require external financing or more efficient working capital management.
Defensible Niches and Industry Counterforces in Promotional Products
ADM Endeavors’ competitive position is anchored in its ability to offer end-to-end solutions—design, production, fulfillment—under one roof, which can be compelling for institutional buyers seeking reliability and customization. The internalization of screen printing, embroidery, and digital production gives the company flexibility to respond to shifting demand and supply chain disruptions. International sourcing diversification, particularly the shift from China to Pakistan and the exploration of India, may help mitigate tariff and geopolitical risk [S1].
At the same time, the promotional products and uniform markets are highly fragmented and price-sensitive, with many small and regional players as well as national distributors. Barriers to entry are moderate; while vertical integration creates operational complexity, it does not ensure customer lock-in or pricing power. ADM Endeavors’ focus on government contracts provides some insulation from pure price competition, but also introduces exposure to budget cycles and regulatory changes. The planned move into signs and banners through acquisition could broaden the addressable market, but success will depend on integration and the ability to leverage existing customer relationships.
Capacity Utilization and Government Wins Drive Margin Expansion
If ADM Endeavors can ramp utilization of its expanded facility by capturing additional government, school, and business contracts, fixed costs will be absorbed over a larger revenue base, potentially driving operating leverage and margin expansion. The company’s ability to manufacture branded uniforms internally could allow it to capitalize on competitors exiting the market due to trade policy disruptions, especially if it can secure exclusive or long-term supply agreements with institutions.
A favorable scenario would see the company’s digital marketing spend translating into measurable growth in online orders and recurring institutional relationships, reducing reliance on traditional sales channels. If the planned acquisition of a sign shop is executed smoothly, it could unlock cross-selling opportunities and further diversify revenue streams. Confirmation of this upside would come from sequential increases in production volumes, improved gross and operating margins, and evidence of repeat or multi-year government contract renewals. A reduction in days sales outstanding and inventory turnover improvements would also signal better working capital management.
Operational Growth Meets Working Capital Tightrope
The most plausible path for ADM Endeavors is one of steady revenue growth as new capacity is gradually utilized and the company leverages its expanded government and institutional customer base. While vertical integration and in-house branding provide some margin defense, persistent working capital constraints—reflected in a sub-1.0 current ratio—may force the company to prioritize high-turn, low-inventory product lines or seek short-term financing to bridge seasonal and contract-driven cash flow gaps.
In this scenario, profitability remains modest as gains from higher volumes are offset by the costs of ramping up operations, digital marketing, and new venture integration. The company’s ability to retain government contracts and execute on new joint ventures—without overextending its resources—will determine if incremental growth can be sustained. Confirmation would include stable or improving liquidity ratios, continued contract wins, and incremental increases in net income. Evidence to the contrary would include rising payables, inventory build-up, or an increasing need for external funding.
Liquidity Constraints and Execution Risk Derail Expansion
The main threat to ADM Endeavors is that its aggressive facility expansion and contract-driven growth outpace its ability to manage working capital and execute operationally. If government and institutional orders fail to materialize at the volume needed to cover increased fixed costs, or if payment cycles lengthen, the company could face cash shortfalls, forcing asset sales, operational cutbacks, or dilutive financing.
Adverse developments could also stem from execution missteps—such as delays in integrating new ventures, cost overruns, or customer attrition due to service or fulfillment challenges. Heightened competition or further trade disruptions could compress margins or strand inventory. Downside confirmation would include deteriorating liquidity ratios, negative operating cash flow, missed contract milestones, or the need for emergency capital raises.
What Will Determine Whether ADM Endeavors Converts Capacity into Profitable Growth?
Production utilization rates across screen printing, embroidery, and digital departments—if disclosed—will reveal whether new capacity is translating into higher volumes.
Sequential changes in gross and operating margins as the new facility ramps up will test the thesis of operating leverage.
Trends in the current ratio and cash ratio over the next several quarters will indicate whether liquidity is stabilizing or deteriorating.
The pace and size of new government and institutional contract awards, as well as renewal rates for existing contracts, would help confirm demand durability.
Inventory turnover and days sales outstanding—if disclosed—would clarify working capital efficiency.
Progress on the planned acquisition of a sign shop, including integration costs and revenue contribution, will be a key milestone.
Evidence of successful cross-selling between product lines and ventures, as measured by average order size or multi-category contracts, would support the growth thesis.
Any commentary or disclosure on external financing needs or covenant compliance would signal the degree of potential financial flexibility or stress.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments