
Aptevo Therapeutics: Clinical Progress, Capital Constraints, and the Stakes of Surviving to Pivotal Data
Aptevo Therapeutics advances its immunotherapy pipeline with notable clinical signals in AML, but acute capital needs and going concern warnings overshadow progress. The company's ability to translate scientific momentum into commercial value hinges on near-term trial milestones, external financing, and the durability of partnership economics.
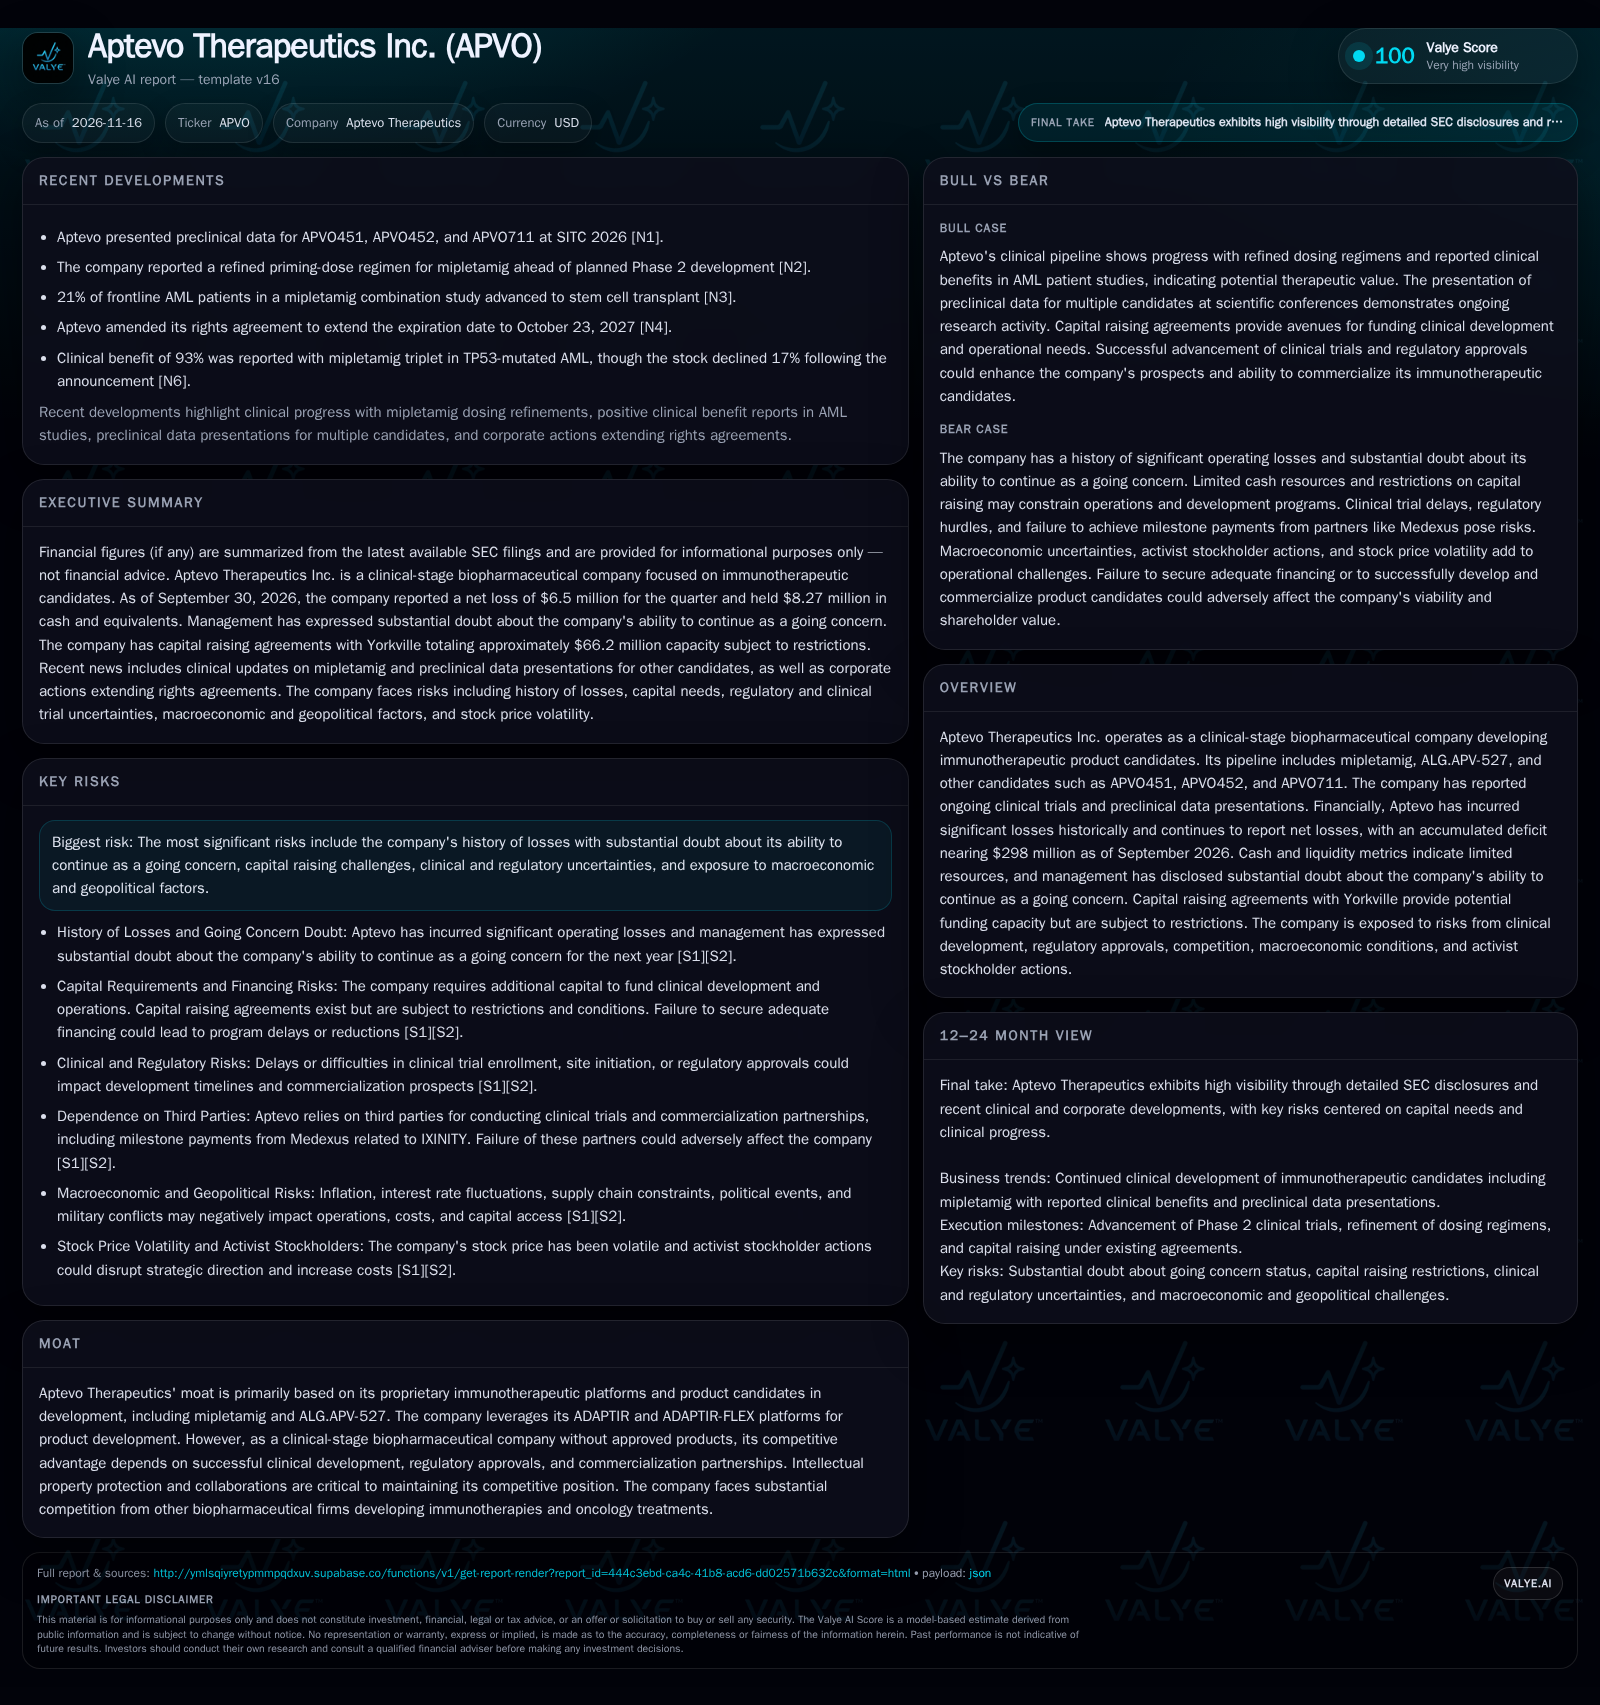
Aptevo Therapeutics reported a net loss of $6.5 million in Q3 2026 and faces substantial doubt about its ability to continue as a going concern, with $8.27 million in cash and $66.2 million in potential but restricted equity financing. Recent clinical data for mipletamig in AML and preclinical progress with other candidates highlight scientific momentum, but operational continuity depends on securing funding and advancing to pivotal trial stages. Key risks include capital constraints, regulatory and clinical hurdles, and dependence on milestone payments from out-licensed assets. [S2] [N1] [N2] [N3] [N6]
Aptevo Therapeutics stands at a precarious intersection of scientific advancement and existential financial risk. With a pipeline led by mipletamig showing encouraging clinical signals in acute myeloid leukemia and continued preclinical progress, the company’s scientific case is strengthening. However, a depleted cash reserve, explicit going concern warnings, and dependence on restricted equity financing cast immediate doubt on Aptevo’s ability to survive long enough to realize the value of its R&D. The critical question is whether the company can secure sufficient operating runway to reach the inflection points needed for value creation—or if near-term capital constraints and external dependencies will force retrenchment or unfavorable deals. [S2] [N1] [N2] [N3] [N6]
Clinical Milestones and Capital Shortfall Define the Present Reality
Aptevo’s Q3 2026 results underscore both scientific and financial inflection points. The company reported a net loss of $6.5 million for the quarter, with an accumulated deficit of $297.6 million as of September 30, 2026. Its cash and equivalents stood at $8.27 million, supporting a current ratio of 1.5 and a cash ratio of 2.7, but management has disclosed substantial doubt about Aptevo’s ability to continue as a going concern for the next year. [S2]
On the operational front, mipletamig—a lead immunotherapeutic candidate—has shown a 93% clinical benefit rate in TP53-mutated AML and enabled 21% of frontline AML patients in a combination study to proceed to stem cell transplant, signaling clinical progress. The company also presented new preclinical data for APVO451, APVO452, and APVO711 at SITC 2026, reflecting ongoing pipeline activity. [N1] [N3] [N6]
Aptevo’s only near-term external funding lever is a Standby Equity Purchase Agreement with Yorkville, potentially providing up to $66.2 million, but this capital is subject to restrictions and not guaranteed. The company’s financial future is thus tightly coupled to both capital market conditions and the pace of clinical advancement. [S2]
How Aptevo’s R&D Model Confronts Fixed Costs and Capital Scarcity
As a clinical-stage biopharmaceutical company, Aptevo’s economics are dominated by high fixed R&D and G&A costs, with little to no recurring revenue from approved products. The pipeline model is inherently capital-intensive: each clinical asset requires years of investment before any commercial return is possible, and most projects fail before reaching the market.
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. While the Standby Equity Purchase Agreement offers headline access to $66.2 million in equity capital, the structure is typically dilutive and may be gated by share price, trading volume, and contractual restrictions. This means Aptevo cannot rely on these funds as a flexible, immediate backstop, and must time its access carefully to avoid excessive dilution or market disruption. [S2]
Any future income from milestone payments tied to the out-licensed IXINITY product is contingent on Medexus’ commercial execution, which Aptevo no longer controls. Without near-term product revenue, Aptevo’s only path to self-funding is a high-value out-licensing deal, acquisition, or a major clinical inflection that enables non-dilutive financing. The economics are thus highly levered to clinical trial outcomes, capital market sentiment, and the willingness of partners to fund risky, late-stage development.
Navigating a Crowded Immunotherapy Landscape
Aptevo’s competitive position rests on its proprietary ADAPTIR and ADAPTIR-FLEX immunotherapeutic platforms, which underpin its pipeline candidates such as mipletamig and APV-527. The oncology immunotherapy space, however, is intensely competitive, with major pharmaceutical and biotech firms pursuing similar targets and modalities.
The company’s moat is largely predicated on intellectual property and the clinical differentiation of its candidates. The reported 93% clinical benefit rate in TP53-mutated AML for mipletamig is notable, but the market for AML therapies includes established players and numerous other clinical-stage competitors. To sustain an edge, Aptevo must demonstrate not just efficacy but also safety, differentiation, and a clear regulatory path—factors that influence both eventual pricing power and partnership interest.
Reliance on third parties for clinical execution and out-licensed asset milestones introduces further vulnerability. If competitors achieve earlier or more robust clinical readouts, or if larger players accelerate partnering or acquisitions in the space, Aptevo’s window for achieving a competitive commercial position could close rapidly.
Clinical Inflection Drives Financing and Strategic Options
The most favorable scenario for Aptevo is that continued positive clinical data for mipletamig—particularly in high-need subpopulations like TP53-mutated AML—stimulates significant interest from larger biopharma partners or acquirers. If the planned Phase 2 development confirms efficacy and safety, Aptevo could secure a non-dilutive licensing deal or outright acquisition, providing capital to advance the rest of its pipeline and potentially realize shareholder value.
Confirmation of this scenario would be clear evidence of robust patient enrollment and retention in Phase 2 trials, positive interim data, and news of partnership negotiations or term sheets. A successful drawdown on the Yorkville equity facility at favorable terms, without excessive dilution, would also signal improved capital market confidence.
Falsification would occur if clinical results fail to replicate earlier signals, if the company struggles to enroll or retain patients, or if the equity facility proves inaccessible due to share price or volume constraints.
Survival Mode: Incremental Progress Amid Unrelenting Capital Pressure
The most likely trajectory for Aptevo is a series of incremental clinical and operational advances, punctuated by repeated capital raises under the restricted Yorkville facility. The company may be able to push mipletamig into Phase 2 and generate additional preclinical data for other assets, but will likely need to make trade-offs—such as program delays or staff reductions—to conserve cash.
This outcome would be confirmed by consistent, albeit slow, clinical progress; ongoing but modest capital infusions; and continued going concern disclosures. Progress would be measured by the ability to keep trials open and reach interim data readouts without major operational setbacks.
If Aptevo is unable to maintain patient enrollment, faces regulatory setbacks, or is forced to halt programs due to lack of funds, this base scenario could quickly deteriorate into a downside outcome.
Funding Cliff or Clinical Failure Triggers Strategic Retrenchment
A more adverse scenario materializes if Aptevo is unable to access sufficient capital from the Yorkville facility or other sources, or if its clinical programs encounter setbacks that erode external confidence. In this case, the company could be forced to halt or significantly delay clinical trials, lay off staff, or seek strategic alternatives from a position of weakness—including asset sales or a distressed merger.
Evidence of this trajectory would include failure to raise meaningful capital, missed clinical milestones, program discontinuations, or explicit SEC filings detailing workforce reductions or asset divestitures. A delisting from Nasdaq due to sustained low share price or market cap would further constrain options and could precipitate a liquidity crisis.
Falsification of this scenario would require a material improvement in the company’s cash position, successful execution of clinical milestones, or news of a transformative partnership or acquisition.
Markers That Will Shape Aptevo’s Survival and Value Creation Prospects
Updates on patient enrollment, retention, and interim efficacy data for mipletamig’s planned Phase 2 trial—if disclosed—will be vital for assessing clinical momentum.
Actual proceeds raised from the Yorkville Standby Equity Purchase Agreement and the terms (pricing, dilution) under which capital is accessed.
Evidence of new partnership negotiations, licensing deals, or acquisition interest, particularly tied to mipletamig or APV-527.
Material changes in operational spending, including layoffs, trial delays, or program prioritization decisions, as signs of cash conservation or distress.
Updates on milestone payments from Medexus for IXINITY, which could provide non-dilutive funding but are outside Aptevo’s direct control.
Any SEC or Nasdaq notifications regarding listing compliance, which could signal heightened risk of delisting and further constrain financing options.
Presentation of additional preclinical or clinical data for APVO451, APVO452, and APVO711, which could broaden the pipeline’s perceived value.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments