
Biofrontera Inc.: Dermatology Growth Ambitions Collide with Financial Constraints and Regulatory Hurdles
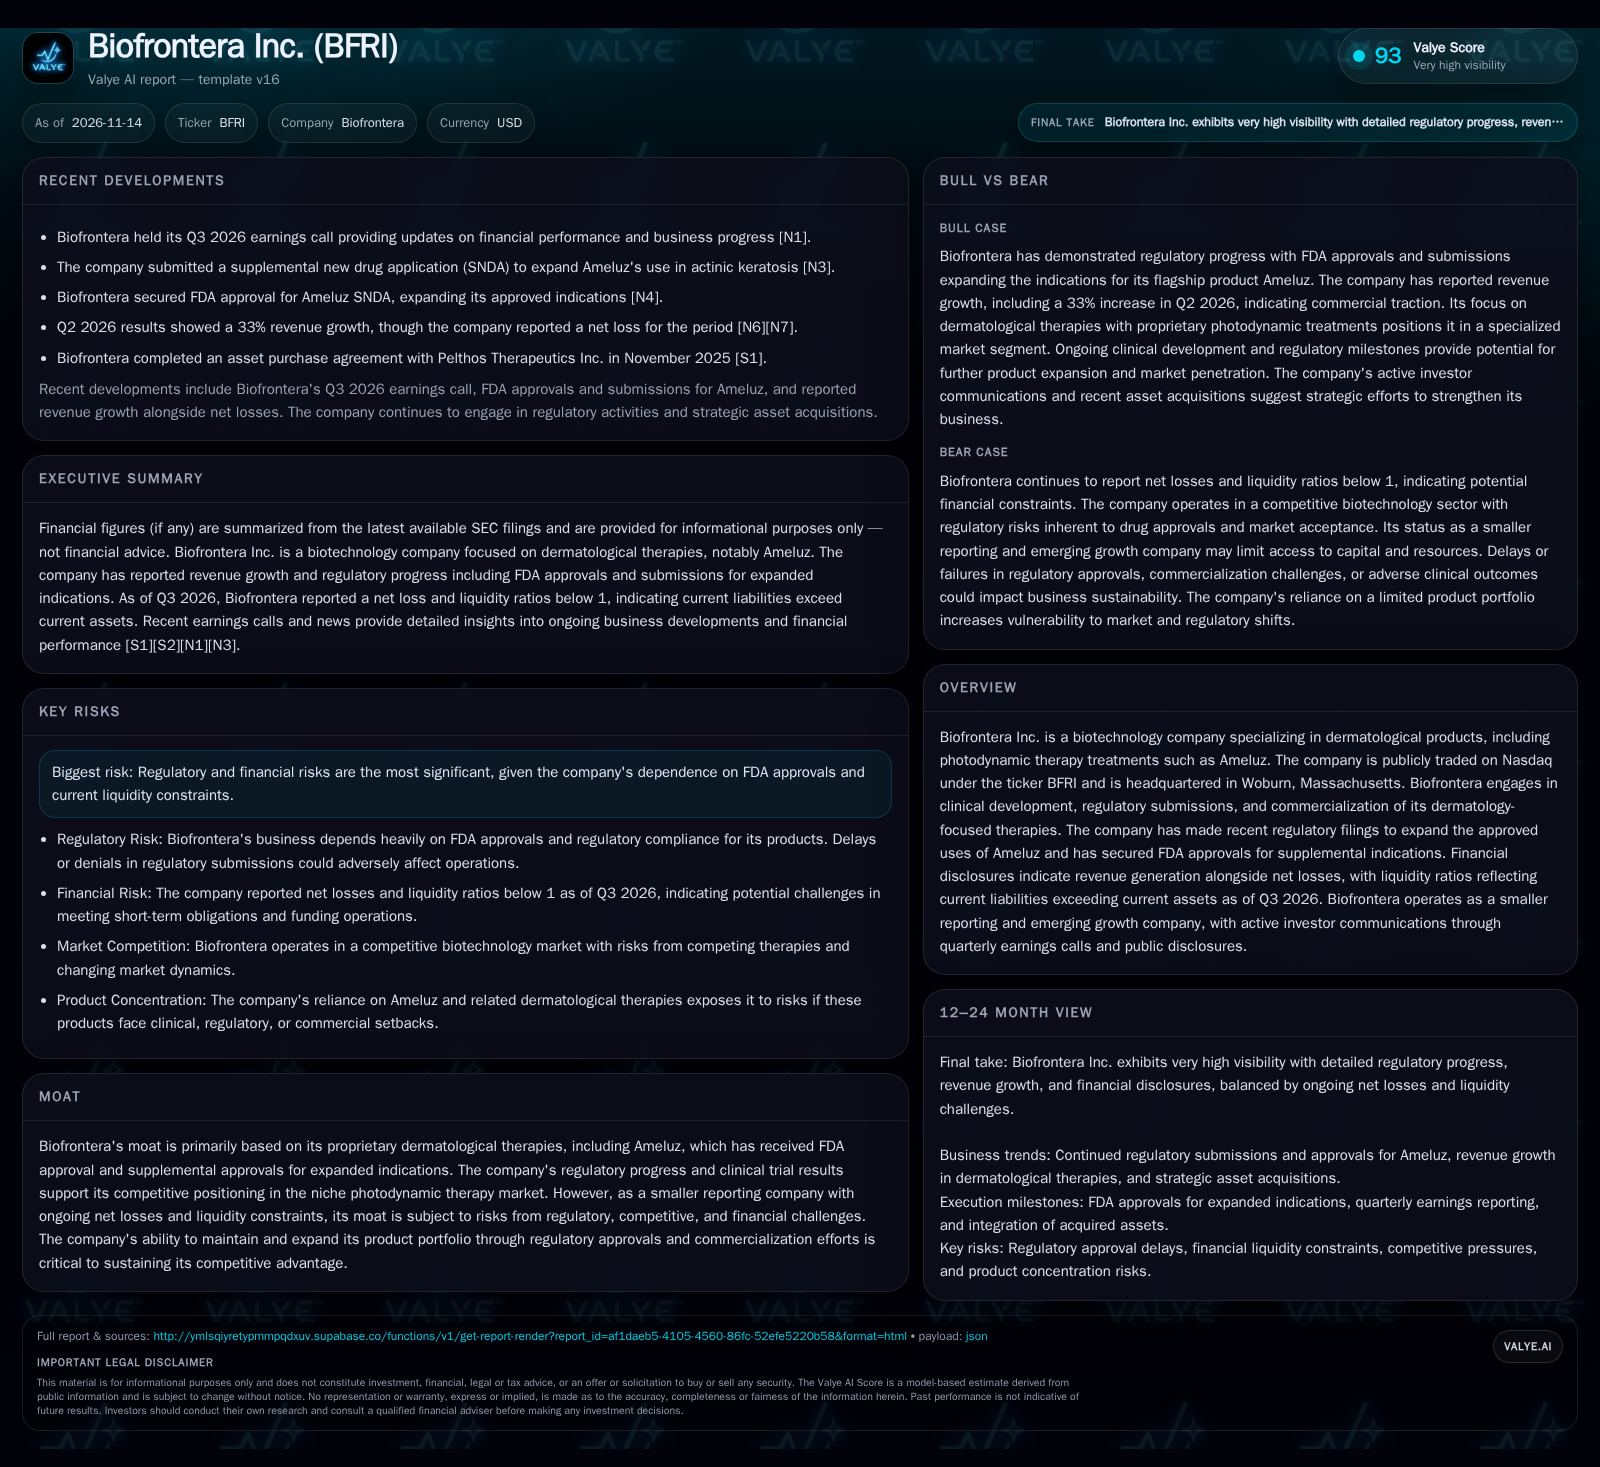
Biofrontera Inc., a specialist in photodynamic dermatological therapies, is experiencing revenue growth and pursuing regulatory expansion for its flagship product.
The company's future hinges on successful regulatory expansion, effective commercialization, and the ability to secure additional resources in a competitive and capital-intensive market.
Biofrontera Inc., a Nasdaq-listed biotechnology company headquartered in Massachusetts, is navigating a classic biotech tension: accelerating revenue growth from its proprietary dermatological therapies—including a reported 33% increase in Q2 2026—while contending with persistent net losses, low liquidity ratios, and a heavy reliance on regulatory success. The company’s push to expand the use of its lead product, Ameluz, via a supplemental new drug application, and its recent asset acquisition, underscore a strategy aimed at both deepening and diversifying its commercial footprint. However, with current liabilities outstripping assets and a quarterly net loss exceeding $6 million, Biofrontera’s ability to sustain momentum and capture long-term market value will depend on its execution across regulatory, financial, and competitive fronts.
Recent Financials and Strategic Moves: A Double-Edged Sword
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2] The company posted a net loss of $6.423 million for Q3 2026, equating to a quarterly EPS of -$0.42 [S2]. Despite these financial pressures, Biofrontera achieved a 33% year-over-year revenue increase in Q2 2026 [N6], suggesting that its dermatological therapies—anchored by Ameluz—are gaining commercial traction. The submission of a supplemental new drug application (SNDA) to expand Ameluz’s use in actinic keratosis [N3] and the completion of an asset purchase agreement with Pelthos Therapeutics Inc. in November 2025 [S1] signal an active growth and diversification agenda. However, the combination of accelerating revenue and persistent operating losses highlights the company’s precarious balancing act between growth ambitions and financial resilience.
How Biofrontera’s Dermatology Model Could Scale—Or Stall
Biofrontera’s revenue model centers on the commercialization of proprietary dermatological therapies, notably photodynamic treatments such as Ameluz. Revenue is likely driven by a mix of direct product sales to dermatologists and clinics, potentially supplemented by recurring orders for consumables and follow-up treatments if clinical adoption is robust. Pricing in dermatology, particularly for FDA-approved photodynamic therapies, tends to command a premium due to the specialized nature and clinical efficacy of these products. However, without explicit disclosure of gross margins or contract structures, it remains unclear how much fixed versus variable cost leverage is available to Biofrontera.
The company’s net losses and low liquidity ratios suggest that operating expenses—encompassing R&D, regulatory, and commercial infrastructure—are outpacing gross profit. If Ameluz’s label expansion is approved and subsequent uptake is strong, operating leverage could improve as incremental sales flow through a largely fixed cost base. Conversely, the need for ongoing clinical development, regulatory submissions, and potential new product launches (including assets from Pelthos Therapeutics) may require substantial additional capital. In effect, Biofrontera’s economics are caught between the promise of high-margin specialty drug sales and the reality of biotech’s capital-intensive scaling curve.
Market Niche, Moat Erosion, and the Threat of Substitutes
Biofrontera operates in the highly competitive dermatology and photodynamic therapy market, where its focus on proprietary treatments like Ameluz provides a degree of differentiation. The ability to secure and expand regulatory indications can offer a temporary moat, especially if clinical data supports superior efficacy, safety, or ease of use. However, the company’s position is vulnerable to several counterforces: established pharmaceutical players with broader dermatology portfolios, generic entrants targeting off-patent therapies, and alternative modalities (such as topical therapies or novel device-based treatments) that could erode adoption of photodynamic solutions.
Switching costs for dermatology clinics are typically moderate, as clinicians may be incentivized by payer reimbursement, patient outcomes, and workflow integration. Without evidence of substantial network effects, long-term contracts, or proprietary delivery mechanisms, Biofrontera’s competitive edge may hinge on continued clinical innovation and regulatory agility rather than intrinsic structural advantages. The recent asset purchase from Pelthos Therapeutics could diversify the pipeline, but integration risks and the challenge of commercializing new assets in a crowded field remain material.
Unlocking Value Through Regulatory Wins and Commercial Execution
The most favorable scenario for Biofrontera would involve successful FDA approval and market uptake of the expanded Ameluz indication, driving accelerated revenue growth and improved operating leverage. If the SNDA is granted and Ameluz firmly establishes itself as a standard of care in actinic keratosis, the company could see increasing demand from dermatology practices, expanded payer coverage, and potentially improved margins as scale effects take hold.
Confirmation of this scenario would come from sustained double-digit revenue growth in subsequent quarters, sequential improvement in gross and operating margins, and evidence of commercial milestones such as new clinic or network partnerships. Additional upside would be signaled by the successful integration and commercialization of Pelthos assets, as well as the ability to secure non-dilutive funding (e.g., milestone payments, partnerships) to support further R&D. Falsification would be indicated by regulatory delays, slow post-approval uptake, or persistent negative cash flow requiring dilutive capital raises.
Commercial Progress Offset by Financial Strain and Incremental Growth
The most plausible trajectory for Biofrontera is moderate revenue growth from its existing portfolio, with incremental gains from any approved label expansions, but continued net losses due to R&D and commercial spending outpacing top-line growth. The company may experience periodic boosts tied to regulatory milestones or new product introductions, but these are likely to be counterbalanced by ongoing cash burn and the need for capital infusions.
Evidence for this scenario would include single-digit to low double-digit revenue growth, persistent or widening operating losses, and the announcement of equity or debt financing to shore up liquidity. Falsification would be a sudden, sustained improvement in profitability or, conversely, an inability to secure needed financing, resulting in operational retrenchment.
When Liquidity Runs Thin: The Risks of Funding Gaps and Regulatory Setbacks
The adverse scenario for Biofrontera entails a combination of regulatory disappointment—such as an FDA rejection or significant delay of the Ameluz SNDA—alongside continued net losses and deteriorating liquidity. In this outcome, the company’s limited cash and sub-1.0 current ratio could force urgent capital raises on unfavorable terms, asset sales, or even restructuring.
Confirmation would come from declining or flat revenue, missed clinical or regulatory milestones, and worsening balance sheet metrics (e.g., declining cash, increasing payables). The inability to execute on the Pelthos asset integration or to generate meaningful new product revenue would further erode investor and partner confidence. Falsification would require news of a successful, non-dilutive financing, a surprise regulatory win, or a sharp inflection in sales performance.
Concrete Milestones That Will Define Biofrontera’s Next Chapter
Resolution and timing of the FDA decision on the Ameluz supplemental new drug application; regulatory clarity would be a key pivot point for the commercial outlook.
Quarterly revenue growth rates and evidence of sequential sales acceleration or deceleration, especially in the wake of any label expansion or new product launches.
Gross margin trends, if disclosed, to assess whether operating leverage is improving as revenues scale.
Cash flow from operations and changes in cash balance; a useful metric would be the company’s projected runway under various revenue scenarios.
Updates on the integration and commercialization progress of acquired assets from Pelthos Therapeutics.
Announcements of new funding arrangements—debt, equity, or partnerships—and their terms, which would directly impact dilution and strategic flexibility.
Any material changes in competitive dynamics—such as new product launches by rivals or shifts in reimbursement—that could affect market share or pricing power.
Disclosure of customer concentration or churn data, if available, to test the resilience of Biofrontera’s commercial relationships.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments