
Enhanced Group Inc.: Can a Hybrid Model of Sports, Telehealth, and AI Wellness Achieve Scale?
Formed through a high-profile SPAC merger, Enhanced Group Inc. integrates sports events, direct-to-consumer telehealth, and an AI-powered wellness platform. With new regulatory leeway for peptide therapies and a major European live entertainment acquisition pending, the company must prove it can turn liquidity and innovation into sustainable economics amid ongoing losses and operational complexity.
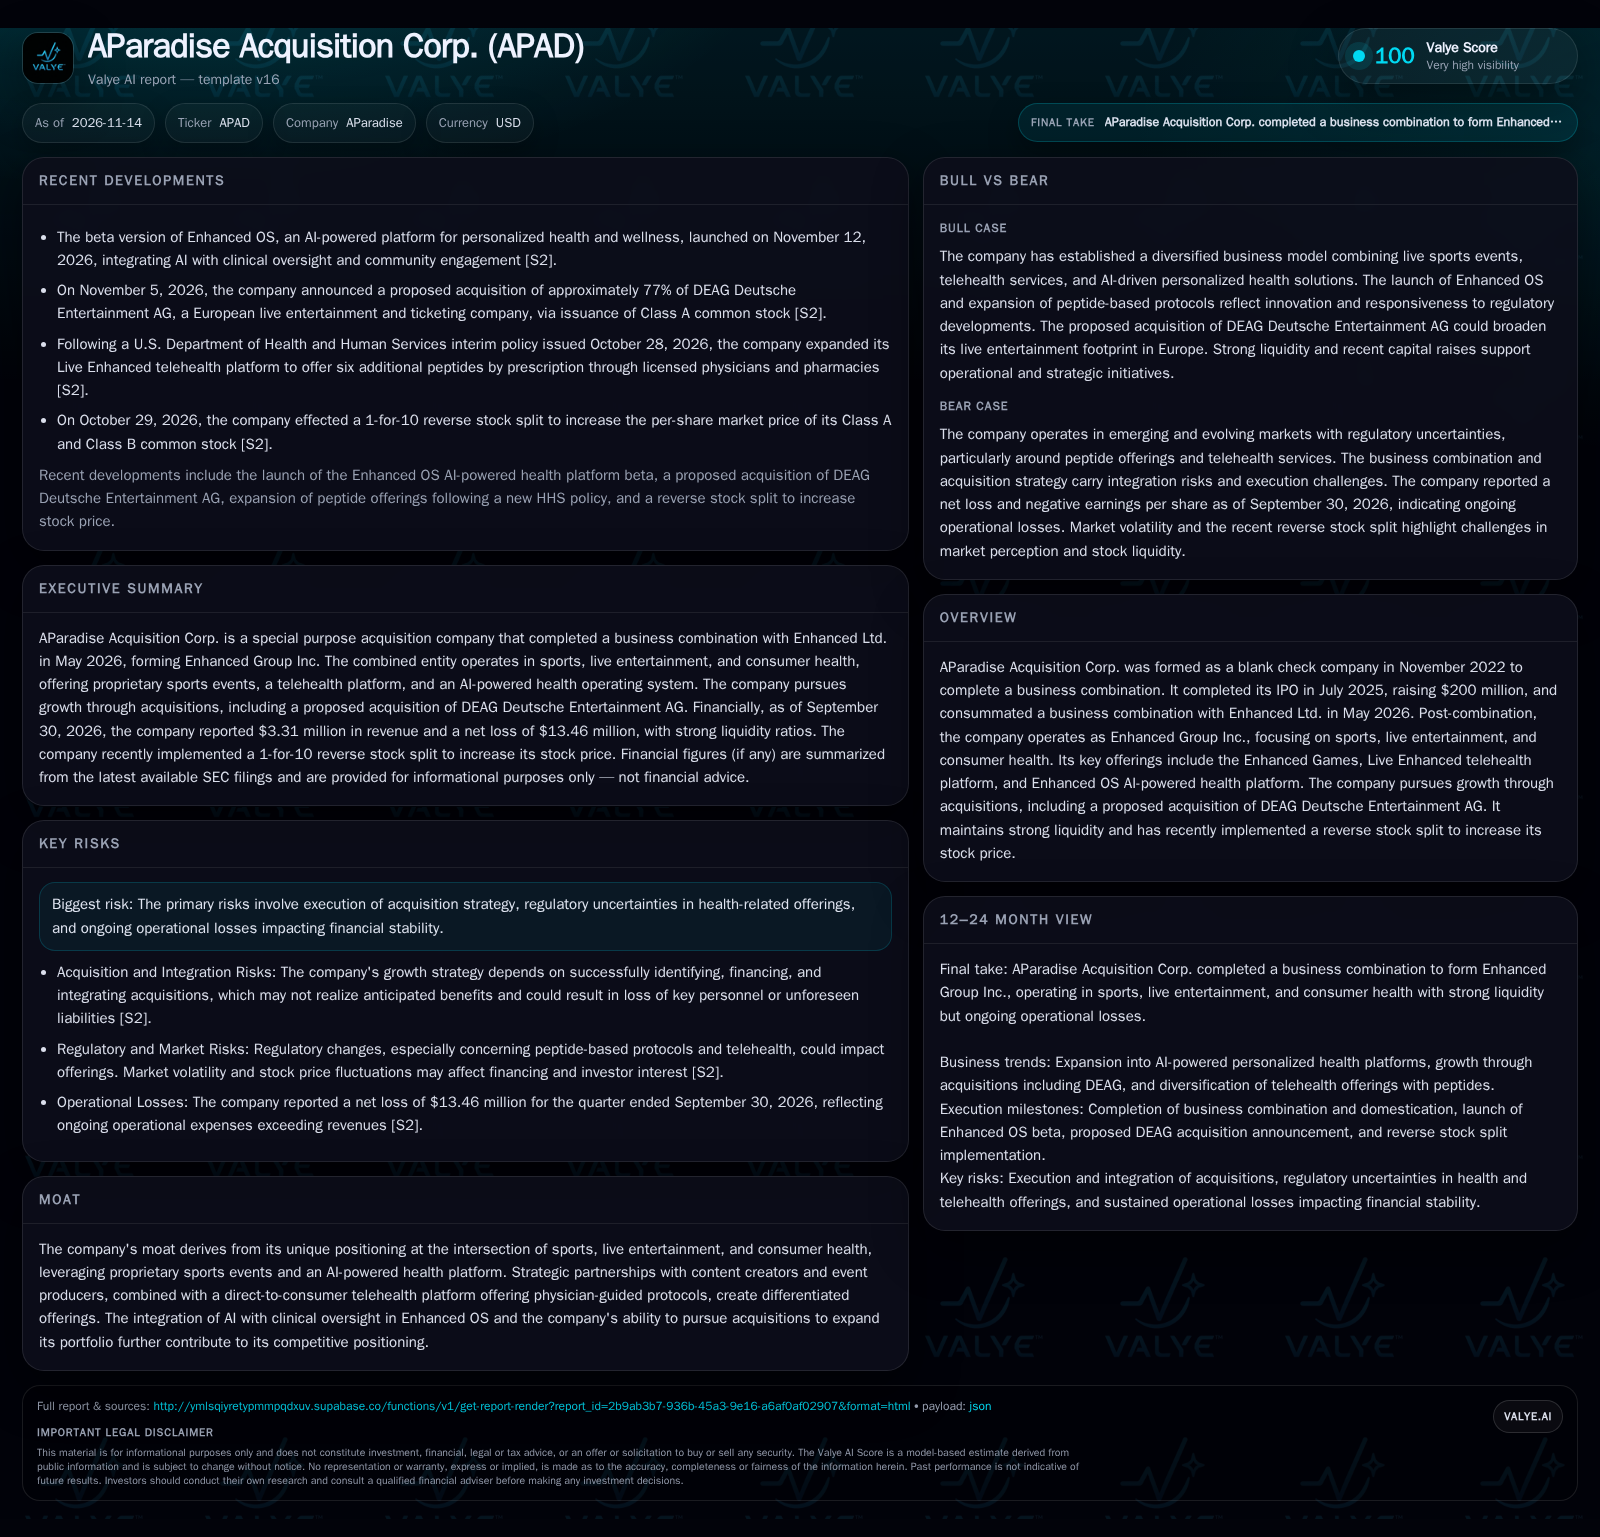
Enhanced Group Inc. (formerly AParadise Acquisition Corp.) completed its business combination in May 2026 and now targets the intersection of sports, live entertainment, and consumer health. Recent launches include an AI-powered wellness platform and expanded telehealth peptide offerings, alongside a pending acquisition of DEAG Deutsche Entertainment AG. [S1] [S2]
Enhanced Group Inc. (formerly AParadise Acquisition Corp.) is attempting to redefine the boundaries between sports, consumer health, and live entertainment. Following its SPAC merger with Enhanced Ltd., the company has quickly launched new AI-powered wellness tools and expanded its telehealth platform, capitalizing on recent regulatory shifts in peptide therapies. The pending acquisition of a majority stake in European live entertainment operator DEAG signals a bid for rapid scale and diversification.
Recent Milestones and Strategic Shifts Shape the Growth Narrative
Several material events now frame Enhanced Group Inc.'s trajectory. The company completed its business combination in May 2026, transforming from a SPAC into an operating entity with a focus on sports, live events, and consumer health solutions. Notably, it launched Enhanced OS, an AI-driven health and wellness platform, in beta on November 12, 2026, aiming to personalize health recommendations and foster user engagement under clinical oversight. Concurrently, the Live Enhanced telehealth platform expanded to offer additional peptide protocols after a U.S. policy change allowed broader compounding and prescribing by licensed physicians. These moves directly respond to evolving regulatory and technological landscapes. On the M&A front, Enhanced announced a proposed acquisition of approximately 77% of DEAG Deutsche Entertainment AG, a major European live entertainment and ticketing company, potentially diversifying both its revenue mix and geographic exposure. Financially, as of September 30, 2026, the company reported $3.31 million in revenue and a net loss of $13.46 million, with $12.07 million in cash and strong current and cash ratios. The company also completed a 1-for-10 reverse stock split to support its public listing. [S1] [S2]
Assessing the Economics of a Multi-Segment Platform
Enhanced Group’s business now spans three distinct but potentially synergistic segments: proprietary sports events (Enhanced Games), a subscription-based telehealth platform (Live Enhanced), and an AI-powered health operating system (Enhanced OS). Revenue mechanisms could include event ticketing, sponsorships, telehealth subscriptions, prescription fulfillment, and digital health services. The economics of each segment differ: live events are capital- and logistics-intensive with cyclical revenue, telehealth offers the potential for recurring subscription and prescription fees, and AI-driven platforms may scale with lower incremental costs if user adoption accelerates.
The company’s peptide-based protocols, recently enabled by regulatory change, introduce a high-margin prescription revenue stream but also regulatory and compliance costs. The ability to cross-sell protocols, apparel, and event experiences could improve average revenue per user (ARPU), but the cost of customer acquisition and medical oversight may pressure margins until scale is achieved. Integration of DEAG would add a large, established ticketing and live entertainment business with different fixed/variable cost dynamics, potentially improving revenue stability but also increasing complexity and integration risk.
Operating leverage is plausible if Enhanced can grow its digital and telehealth user base faster than platform costs, but the current net loss and limited revenue base suggest that scale and efficiency are not yet realized. The necessity of additional capital raises, as flagged in the risk disclosures, highlights the gap between current liquidity and the capital required for both organic and inorganic growth.
Where Enhanced Could Carve Out an Edge—And Where It Is Exposed
Enhanced Group’s ambition is to occupy a unique intersection: combining proprietary sports events with direct-to-consumer health solutions and AI-driven personalization. This hybrid model is rare, potentially enabling differentiated experiences and cross-segment brand engagement. However, each segment faces established competitors: global live entertainment and ticketing firms, telehealth platforms with national reach, and health-tech players deploying AI for wellness and longevity.
Enhanced’s moat may derive from integrating performance-enhancing protocols (such as peptides) into athlete-inspired consumer offerings, and from its proprietary sports properties that can generate exclusive content and community engagement. The AI-driven Enhanced OS, if able to deliver effective, personalized protocols under clinical oversight, could increase switching costs and retention by embedding itself in daily wellness routines. However, regulatory risk, especially around performance enhancement and telehealth, remains a potential Achilles’ heel. Larger, better-capitalized competitors in both health-tech and entertainment could respond with their own bundles or acquisitions, eroding any early-mover advantage. Success will depend on the company’s ability to execute across disparate domains and to sustain credibility with both consumers and regulators.
How Regulatory Tailwinds and Platform Adoption Could Drive Nonlinear Growth
The most optimistic scenario for Enhanced Group hinges on several reinforcing developments. First, continued regulatory accommodation for peptide therapies and telehealth could accelerate user adoption of the Live Enhanced platform, enabling the company to capture high-margin, recurring prescription revenue. If Enhanced OS’s AI-driven personalization proves clinically effective and drives engagement, the platform could see viral adoption—especially if paired with exclusive athlete content and community features. The DEAG acquisition, if completed and well-integrated, would provide immediate scale in European live events, creating cross-promotional opportunities and a more diversified, resilient revenue base.
Confirmation of this scenario would come from sequential growth in active platform users (especially subscribers and prescription patients), successful upselling of bundled services, and evidence of strong retention or low churn rates. Additional signs would include regulatory clarity or further policy liberalization, successful integration and revenue growth from DEAG, and positive clinical or user engagement outcomes from Enhanced OS.
A Complex Business Model Seeks Proof Points Amid Integration and Scaling Challenges
The most plausible near-term scenario is that Enhanced Group experiences moderate growth across its platforms, but faces lags in user adoption, integration complexity with DEAG, and ongoing regulatory scrutiny. Telehealth and AI-driven health platforms are crowded and require sustained investment in technology, compliance, and marketing. The live events segment may add revenue but also significant operational costs and exposure to cyclical demand.
Evidence confirming this scenario would include steady but unspectacular growth in users, prescriptions, and event revenue, continued net losses, and periodic updates on regulatory or integration hurdles. Conversely, rapid acceleration in any segment, or a material regulatory setback, would falsify the base case.
Integration Missteps and Regulatory Setbacks Could Derail the Growth Thesis
The adverse scenario would be triggered if Enhanced fails to integrate DEAG successfully, leading to operational disruptions, loss of key personnel, or financial underperformance of the acquired business. Simultaneously, if regulatory authorities tighten restrictions on telehealth, peptides, or AI-driven health recommendations, core offerings could be scaled back or face legal challenges. The company’s ongoing net losses, if not offset by rapid revenue growth or cost containment, may force dilutive equity raises or undermine investor confidence.
This scenario would be confirmed by missed revenue targets, higher-than-expected integration or regulatory costs, increased customer churn, or publicized compliance violations. A reversal of recent regulatory gains, such as re-tightening of peptide prescription rules, would also accelerate downside risk.
What Will Determine If Enhanced Group’s Hybrid Model Can Scale?
Active subscriber and prescription user count growth on the Live Enhanced platform—if disclosed—would help test adoption and monetization of new peptide offerings.
Engagement and retention metrics for Enhanced OS, including daily/monthly active users and protocol adherence rates, would clarify user stickiness and platform value.
Progress and terms in the proposed DEAG Deutsche Entertainment AG acquisition, including integration milestones and realized revenue synergies.
Updates on regulatory developments for peptide therapies and telehealth, especially any changes to the interim U.S. Department of Health and Human Services policy.
Gross margin trends across telehealth and digital platforms, as persistent negative margins would challenge the path to profitability.
Evidence of successful cross-selling or bundling between sports events, telehealth, and digital health offerings.
Disclosure of customer acquisition cost (CAC) and average revenue per user (ARPU), which would illuminate scalability and unit economics.
Capital-raising activity and dilution, as frequent equity offerings could signal ongoing cash burn or missed financial targets.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments