
Bogota Financial Corp.: Restructuring, Recovery, and the Realities of Regional Bank Scale
After a strategic balance sheet overhaul and a turbulent 2024, Bogota Financial Corp. has returned to profitability—but faces persistent structural headwinds in New Jersey’s hyper-competitive banking market. The company’s small scale, conservative lending, and regional focus shape both its margin potential and its vulnerability to external shocks.
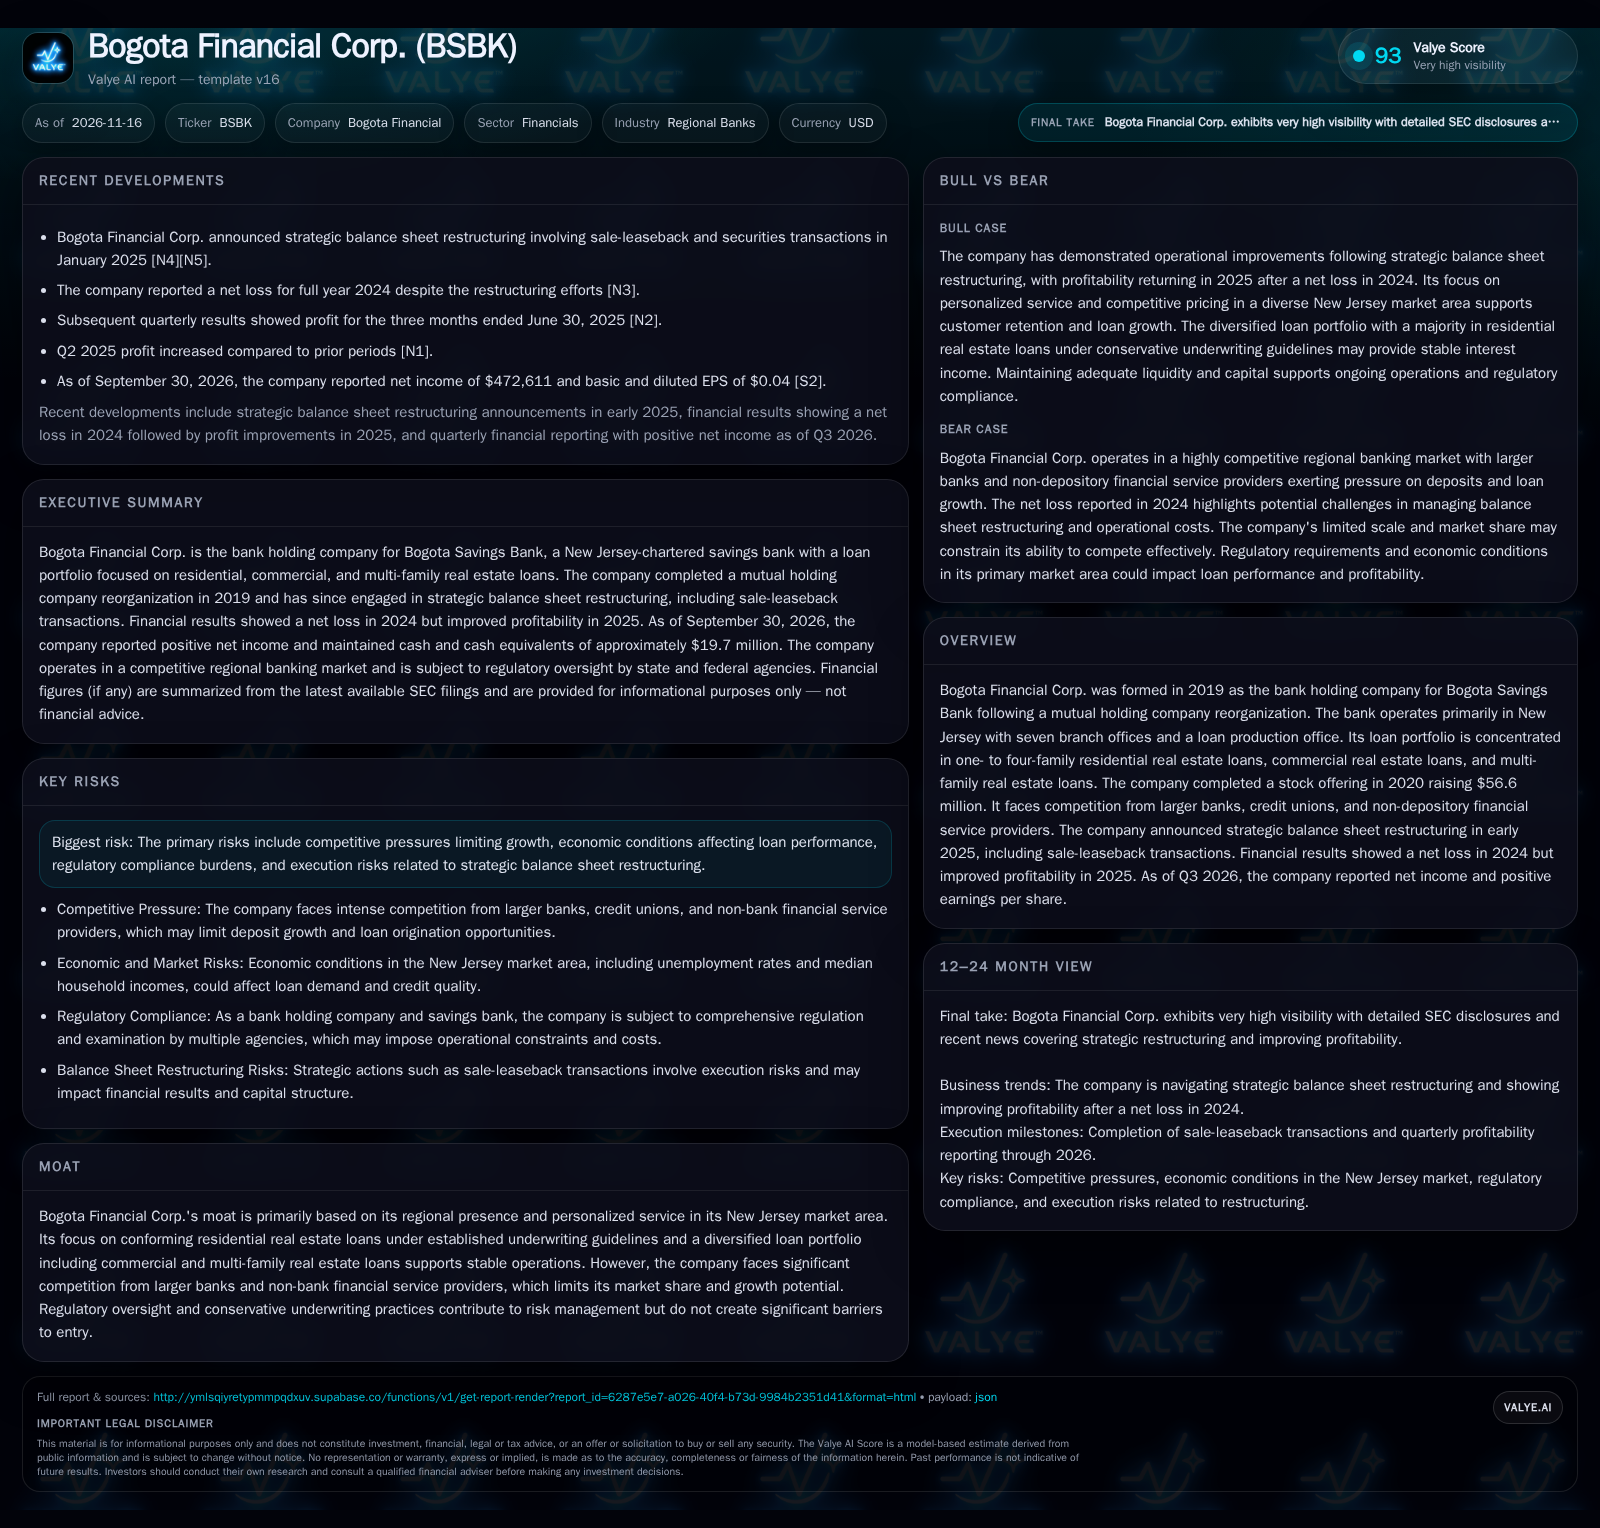
Bogota Financial Corp. executed a strategic balance sheet restructuring in early 2025 after a net loss in 2024, returning to profitability as of Q3 2026. The bank’s business remains concentrated in New Jersey real estate lending, with limited scale and intense competition from larger banks and fintechs. Margin recovery may reflect restructuring benefits, but long-term growth and profitability will hinge on loan growth, cost control, and resilience amid ongoing market and regulatory pressures. [S1] [S2] [N1] [N2] [N3] [N4] [N5]
Bogota Financial Corp. stands as a classic example of a small regional bank seeking stability and growth amid industry consolidation and technological disruption. After posting a net loss in 2024, the company undertook a strategic balance sheet restructuring—including sale-leaseback and securities transactions—that helped return it to profitability by Q3 2026. Yet, with assets under $1 billion, a heavy focus on New Jersey real estate lending, and formidable competition from both legacy banks and fintech upstarts, Bogota Financial’s future will likely be determined less by restructuring maneuvers and more by its ability to drive organic loan growth, defend its funding base, and manage costs in a challenging environment. [S1] [S2] [N1] [N2] [N3] [N4] [N5]
Profitability Returns, but Scale and Competition Remain Central Concerns
The most material recent development for Bogota Financial Corp. is its swing back to profitability after a net loss in 2024. The company reported net income of $472,611 for the quarter ended September 30, 2026, with basic and diluted EPS of $0.04, and held $19.7 million in cash and cash equivalents as of that date [S2]. This improvement followed a strategic balance sheet restructuring in early 2025, which included sale-leaseback transactions and securities sales aimed at shoring up capital and optimizing asset deployment [N4] [N5].
Despite these gains, Bogota Financial remains a small player with approximately $904.9 million in assets and $652.4 million in deposits as of year-end 2025 [S1]. Its lending is concentrated in New Jersey real estate, and it faces ongoing pressure from larger regional and national banks, as well as non-bank competitors. The sustainability of the recent profit trend—and the ability to grow beyond a niche presence—are open questions given these structural realities.
Loan Mix, Funding Costs, and the Limits of Operating Leverage
Bogota Financial’s primary revenue driver is net interest income from its loan portfolio, which is dominated by one- to four-family residential mortgages (68.3%), followed by commercial (27.8%) and multi-family real estate (remainder) [S1]. These loans are generally underwritten to Fannie Mae and Freddie Mac standards, with conservative loan-to-value ratios. While this supports credit quality, it also constrains the yield available relative to riskier lending categories.
On the funding side, deposits are the main liability, but the company’s small scale makes it vulnerable to pricing pressure as larger banks and high-yield digital competitors vie for customer funds. In a rising interest rate environment, this could compress net interest margins unless asset yields rise in tandem.
The sale-leaseback and securities transactions in early 2025 likely improved capital efficiency and provided liquidity, but also may have introduced ongoing lease expenses and reduced future asset appreciation potential [N4] [N5]. Operating leverage is limited by the company’s size: fixed costs such as compliance, branch operations, and technology are spread over a relatively small asset base, making cost discipline critical. Expansion or digitalization efforts would require additional capital or operational risk.
Market Niche versus Market Share: Can Personal Service Offset Scale Deficits?
Bogota Financial’s competitive position is defined by its hyper-local focus and personalized customer service, which differentiates it from larger, impersonal institutions [S1]. However, FDIC data as of June 2025 shows the company’s deposit market share is less than 1% even in its core counties, ranking 21st out of 43 in Bergen County and much lower elsewhere. This lack of scale limits pricing power, product breadth, and digital capabilities.
The bank faces direct competition from money center banks, large regionals, community banks, credit unions, and increasingly from fintechs and non-depository lenders that can deliver high-yield products and seamless digital experiences. Technology has eroded geographic barriers, allowing even non-local competitors to target Bogota’s customer base. While regulatory scrutiny and conservative lending help manage risk, they do not provide a durable moat in terms of customer stickiness or cost advantage.
Without the ability to materially outprice or out-service its larger rivals, Bogota Financial’s best defense may be its established relationships and local knowledge—but even these can be eroded if digital adoption accelerates or customer preferences shift rapidly.
Restructuring Catalyzes Sustainable Margin Expansion and Niche Growth
A favorable scenario for Bogota Financial involves its 2025 restructuring driving sustained margin improvement and freeing up capital for targeted loan growth. If the company can leverage its local reputation to capture a greater share of high-quality residential and commercial borrowers—while controlling funding costs through relationship-based deposits—it could expand its net interest margin even in a competitive environment.
The bank’s conservative underwriting, if paired with modest credit growth and stable asset quality, would support steady earnings and potentially attract further local depositors. Evidence confirming this scenario would include several consecutive quarters of rising net interest margin, loan growth outpacing deposit attrition, and low non-performing asset ratios. If management can also contain non-interest expenses despite inflationary pressures, positive operating leverage could emerge even at modest scale.
Modest Profitability Amid Ongoing Margin Pressure and Slow Growth
The most plausible scenario is that Bogota Financial maintains modest profitability, with earnings fluctuating quarter to quarter as it balances conservative lending, rising funding costs, and ongoing competition. The company’s core business—originating conforming residential and commercial real estate loans in New Jersey—remains relatively stable, but growth is incremental and largely limited to its existing geographic footprint.
Net interest margin may remain under pressure if deposit costs rise faster than loan yields, especially if the Federal Reserve maintains elevated rates or if digital competitors continue to offer aggressive pricing. Expense management will be a persistent challenge, as fixed costs and regulatory compliance weigh heavily on small banks. Evidence for this scenario would be steady but unremarkable earnings, flat or slow-growing loan and deposit balances, and a lack of significant expansion initiatives.
Competitive and Economic Shocks Erode Franchise Value
In an adverse scenario, intensifying competition for both loans and deposits leads to margin compression and market share loss. Larger banks and fintechs could poach customers with higher rates and superior digital offerings, forcing Bogota Financial to pay up for funding or accept lower-quality loans to sustain growth. Economic deterioration in its New Jersey footprint—such as rising unemployment or falling real estate values—could drive up credit losses and non-performing assets.
If the benefits of the 2025 restructuring prove transitory, the company could slip back into losses, especially if regulatory requirements or leaseback obligations increase fixed costs. Evidence of this scenario would include declining net interest income, rising non-performing loan ratios, deposit outflows, and a return to quarterly losses.
Testing the Bogota Financial Thesis: What Will Prove or Disprove Sustainable Recovery?
Quarterly net interest margin trends: Sustained or expanding NIM would suggest successful defense against rising funding costs; compression would signal renewed margin pressure.
Loan growth rates by category: Outperformance in residential, commercial, or multi-family segments would indicate effective local market capture; stagnation would suggest limited franchise traction.
Deposit base stability and cost of funds: A useful metric would be the rate of deposit growth or attrition and average cost of funds—critical for assessing competitive resilience.
Non-performing asset and charge-off ratios: Rising credit losses would undermine the conservative lending thesis; stability would support continued profitability.
Expense ratio (non-interest expense to average assets): If disclosed, trends in this ratio would reveal whether operating leverage is improving or deteriorating.
Impact and duration of sale-leaseback obligations: Monitoring ongoing lease costs versus the capital freed up by the transaction will help test the long-term benefit of restructuring.
Regulatory capital ratios: Sufficient capital buffers are essential for withstanding shocks and supporting growth; declining ratios would be a red flag.
Branch and digital channel productivity: If disclosed, metrics such as deposit per branch, online account growth, or digital loan origination would illuminate the company’s ability to compete in a changing landscape.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments