
Centene’s Managed Care Scale: Regulatory Uncertainty, Cost Pressures, and the Search for Margin Resilience
Centene remains the nation’s largest Medicaid and Marketplace insurer, but faces a complex environment shaped by regulatory changes, medical cost inflation, and membership attrition. Its ability to align premium rates with acuity, expand integrated care for complex populations, and contain SG&A will determine whether scale delivers durable economic advantage.
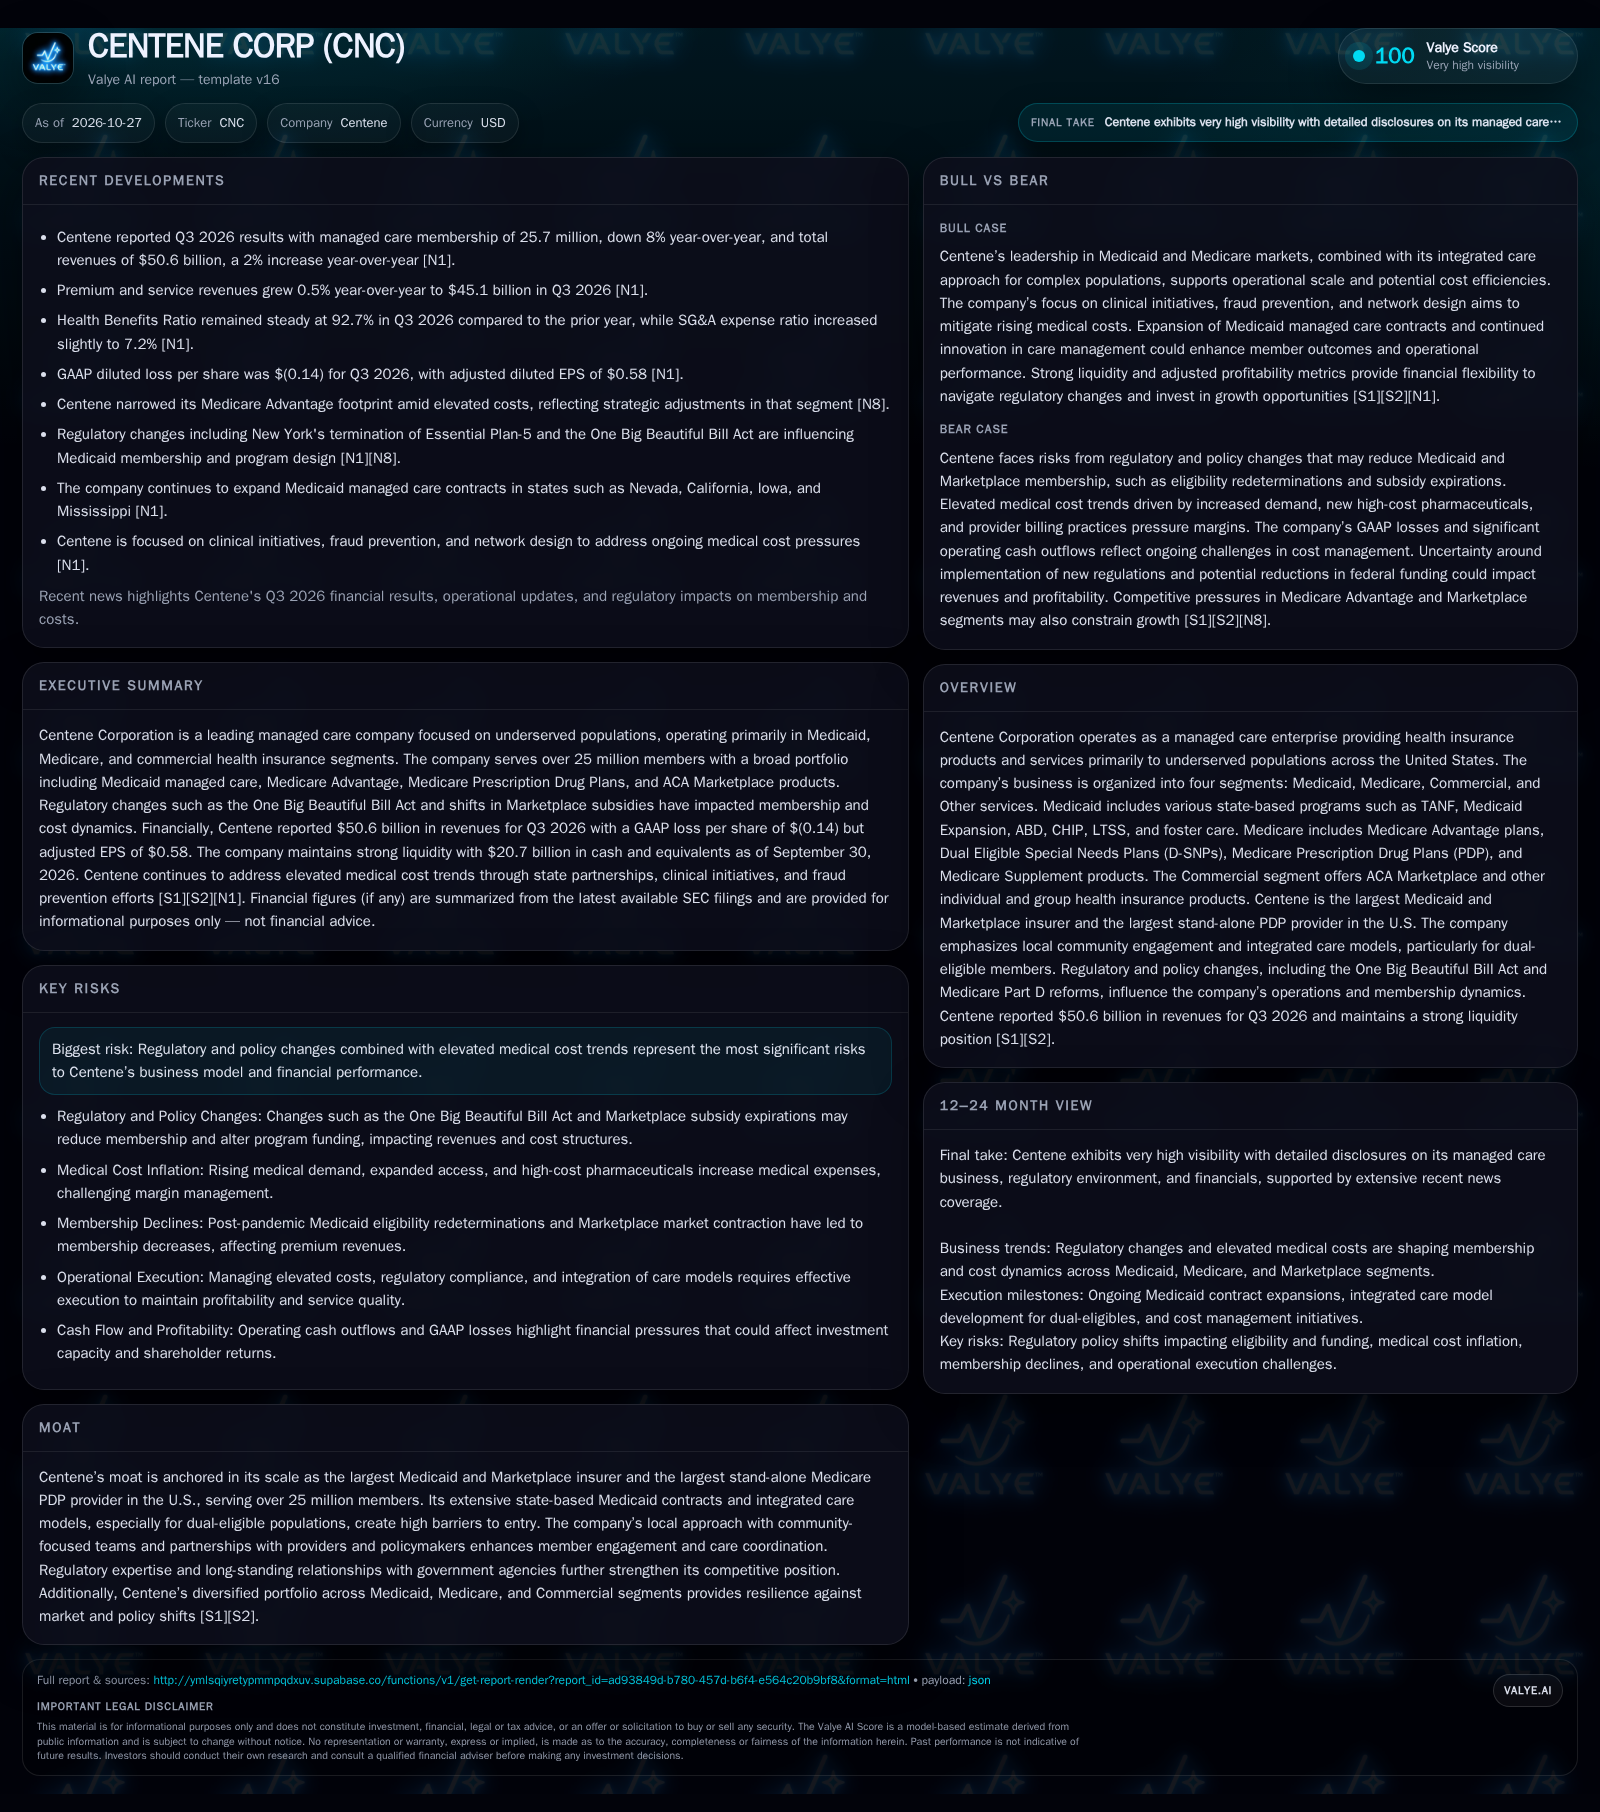
Centene’s leadership in Medicaid and Marketplace insurance provides scale advantages, but recent membership declines and persistent medical cost inflation threaten margins. Regulatory shifts—especially the One Big Beautiful Bill Act and changes to Marketplace subsidies—expose revenue to policy risk. The company’s focus on clinical initiatives and rate negotiations with states is critical, but elevated costs, GAAP losses, and operating cash outflows highlight the tension between growth and profitability [S1] [S2] [N1] [N8].
Centene Corporation’s position as the largest U.S. Medicaid and Marketplace insurer gives it differentiated reach into government-sponsored and ACA health plans for underserved populations. Yet, this scale is being tested by policy changes that threaten membership and revenue, and by medical cost inflation that pressures margins. Q3 2026 results show a company in transition: membership shrank year-over-year, revenue growth slowed, and GAAP profitability remains elusive despite massive premium flows. The central challenge ahead is whether Centene’s operational initiatives and rate negotiations can offset regulatory headwinds and cost pressures, or whether the high fixed costs of scale will magnify downside risks if enrollment and funding falter [S2] [N1] [N8].
Membership and Revenue Shifts Define Centene’s Current Operating Reality
Centene ended Q3 2026 with 25.7 million managed care members—a decline of 2.3 million from the prior year, reflecting both Medicaid redeterminations and a drop in Marketplace enrollment after subsidy expirations [S2] [N1]. While total revenue grew 2% year-over-year to $50.6 billion, premium and service revenue growth slowed to just 0.5% [S2] [N1]. The Health Benefits Ratio (HBR) was unchanged at 92.7%, indicating that medical cost inflation continues to absorb nearly all premium gains [S2]. On the expense side, the SG&A ratio ticked up to 7.2%. Notably, Centene reported operating cash outflows of $3.7 billion in Q3, attributed to timing of pass-through payments, and a GAAP diluted loss per share of $(0.14) [S2]. These facts illustrate a business at the intersection of scale-driven revenue, regulatory-driven membership volatility, and persistent margin compression.
How Centene’s Revenue Flows and Cost Structure Shape Economic Outcomes
Centene’s business model is fundamentally a scale-driven managed care platform: it contracts with states and the federal government to administer Medicaid, Medicare, and Marketplace plans, earning premium revenue in exchange for assuming medical cost risk. The company’s economics are dictated by the spread between capitation premiums and actual medical claims, with additional impact from administrative efficiencies and care management initiatives. Medicaid remains the largest segment (57% of 2025 revenues), followed by Commercial (21%) and Medicare (19%) [S1].
Margins are inherently thin; the Q3 2026 HBR of 92.7% leaves little room for error, and even modest medical cost surprises can swing profitability. The fixed cost base—encompassing IT infrastructure, regulatory compliance, and care management—offers some operating leverage if membership grows, but also introduces risk if enrollment shrinks or if states cut rates. Capital needs are relatively modest in terms of physical assets, but the business requires substantial working capital to manage premium flows, claims reserves, and periodic pass-through payments, as evidenced by the $3.7 billion operating cash outflow in Q3 2026 [S2]. The ability to negotiate rate increases in line with acuity and cost trends is central to sustaining margins.
Scale, State Relationships, and Regulatory Sophistication as Defenses—But Not Guarantees
Centene’s primary competitive advantages stem from its scale, state-by-state contract portfolio, and expertise in navigating complex regulatory environments. As the largest Medicaid and Marketplace insurer and the leading stand-alone Medicare PDP provider, it benefits from robust data, relationships with providers and state agencies, and the ability to spread administrative costs across a vast member base [S1].
However, these advantages are counterbalanced by acute regulatory risk—state contracts can be lost or repriced, and federal policy shifts (such as the One Big Beautiful Bill Act and Marketplace subsidy rules) can rapidly alter the addressable market [S1] [S2]. Competition remains intense, particularly in Medicare Advantage and Marketplace segments where both national carriers and regional plans vie for share. Further, technological innovation or new care delivery models could erode traditional managed care moats if Centene fails to keep pace with analytics, virtual care, or consumer engagement tools.
If Rate Alignment and Care Management Deliver, Margin Expansion Could Follow
A favorable scenario for Centene would unfold if the company succeeds in renegotiating Medicaid rates to accurately reflect rising acuity and medical costs, while deploying clinical initiatives and fraud prevention at scale to curb claims growth. Expansion of managed care contracts in states like Nevada, Iowa, and Mississippi could offset attrition elsewhere, while integrated care models for dual-eligible members—particularly through D-SNPs—may unlock both better outcomes and administrative savings [S2].
Confirmation of this scenario would come from sustained or growing membership in core Medicaid markets, stabilization or improvement in HBR and SG&A ratios, and a return to positive operating cash flow. Evidence of successful care management would include lower-than-peer medical cost growth and improved outcomes for high-risk populations. Additional contract wins or successful navigation of 2027 regulatory requirements for integrated care would further support the thesis.
Enduring Margin Compression Amid Regulatory and Cost Headwinds
The most plausible near-term outcome is that Centene continues to experience margin pressure due to medical cost inflation and regulatory-driven membership volatility. While the company may secure rate increases in some states, these are likely to lag actual cost trends, especially where fiscal constraints limit state flexibility. Membership could stabilize at a lower level as Medicaid redeterminations and Marketplace subsidy expirations work through the system, but revenue growth will remain subdued unless new contract awards or policy changes expand the eligible pool.
Key evidence for this scenario includes a persistently high HBR near current levels, modest SG&A drift, and only incremental improvement in operating cash flows. If Centene is unable to drive down medical trend or secure outsized rate relief, adjusted earnings growth will be muted and GAAP profitability could remain inconsistent. This scenario would be challenged if the company shows clear evidence of margin recovery or membership acceleration in the next several quarters.
When Policy Shocks and Cost Surges Overwhelm Scale
An adverse scenario could materialize if regulatory changes—such as deeper-than-expected Medicaid eligibility cuts, further Marketplace subsidy reductions, or aggressive state rate-setting—trigger additional membership losses and revenue declines. If medical cost inflation accelerates (due to new high-cost drugs or utilization spikes) and Centene fails to align premiums with rising claims, the thin margin structure could flip the business into sustained GAAP losses and negative cash flow.
Confirmation would come from another sharp drop in managed care membership, deterioration in HBR or SG&A ratios, and persistent operating cash outflows despite attempts at cost management. Losses of key state contracts or inability to comply with new integrated care mandates would further pressure the business, potentially forcing asset sales or retrenchment from less profitable markets.
Milestones and Metrics That Will Test Centene’s Margin and Growth Thesis
Quarterly managed care membership trends by segment (Medicaid, Medicare, Marketplace)—especially any reversal of recent declines.
Health Benefits Ratio (HBR) movement relative to both historical levels and peer benchmarks.
SG&A ratio progress and evidence of administrative cost containment, particularly as enrollment fluctuates.
Operating cash flow trajectory—return to positive territory would signal improved claims management and/or payment timing normalization.
New or renewed state Medicaid contract wins, especially in large or high-growth states, as evidence of competitive positioning.
Demonstrated ability to negotiate rate increases that match or exceed medical cost trends.
Results from clinical initiatives and fraud prevention—if disclosed, lower medical cost growth or improved outcomes for high-acuity populations.
Regulatory developments related to the One Big Beautiful Bill Act, Marketplace subsidy policy, and integrated care mandates for dual-eligibles.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments