
Corpay’s Digital Payments Drive: Margin Growth, Legal Hurdles, and Scale Advantages
Corpay, Inc. delivered double-digit revenue growth and robust profitability in Q3 2026, underscoring the potential of its digitized global payments platform. Yet, the company now faces a test of its operating leverage, regulatory resilience, and capacity to convert scale into long-term competitive advantage.
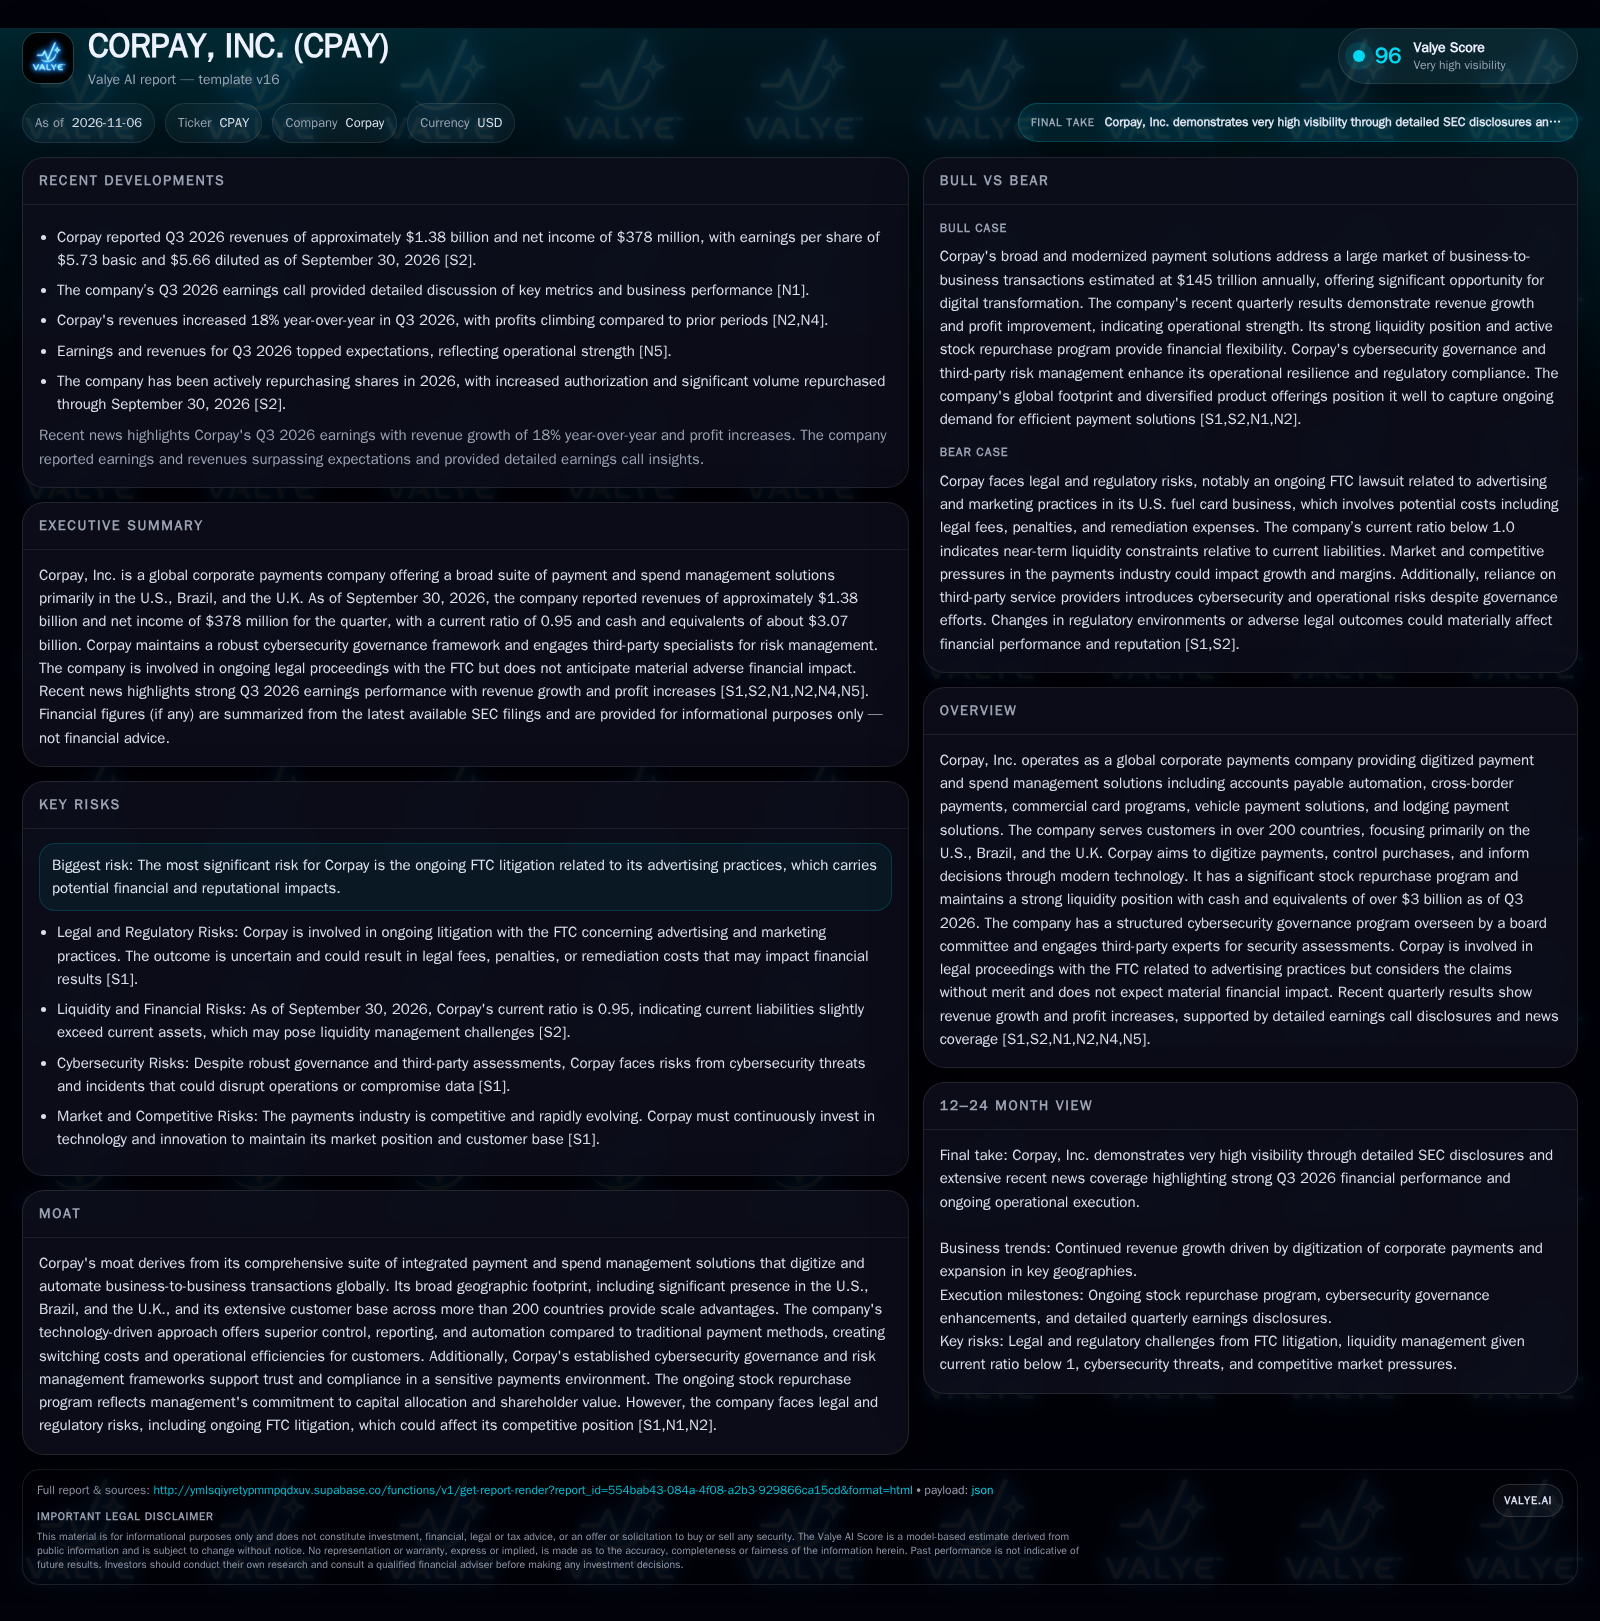
Corpay’s 18% year-over-year revenue increase and strong net income in Q3 2026 reflect operational momentum in global corporate payments. With a broad product suite and presence in over 200 countries, the company is positioned to benefit from ongoing digitization trends. [S2] [N1] [N2] [N4] [N5]
Corpay, Inc. is emerging as a formidable player in the global corporate payments market, leveraging its broad digital platform to automate and control business-to-business transactions. Its Q3 2026 results—highlighted by 18% revenue growth and substantial profitability—demonstrate the operational benefits of scale and digital adoption. Yet, as Corpay pushes for greater market share in the U.S., Brazil, and the U.K., the company must navigate a complex environment of regulatory scrutiny, tight liquidity management, and rapidly evolving customer and technology expectations. The next phase will test whether Corpay can sustain its growth trajectory while defending margins and managing risks inherent to global payments.
Financial Performance Highlights and Key Operational Advances
Corpay reported Q3 2026 revenues of approximately $1.38 billion, marking an 18% increase year-over-year. Net income reached $378 million, with basic EPS of $5.73 and diluted EPS of $5.66 for the quarter [S2] [N2] [N4] [N5]. This outperformance relative to expectations signals effective execution and strong demand for the company’s payment and spend management solutions. The company’s operations remain concentrated in the U.S., Brazil, and the U.K., which collectively account for nearly four-fifths of the business [S1].
On the balance sheet, Corpay held $3.07 billion in cash and equivalents as of September 30, 2026, with a current ratio of 0.95 and cash ratio of 0.18. These levels indicate that current liabilities slightly exceed current assets, raising the importance of prudent liquidity management in the near term [S2].
The company has also executed significant share repurchases in 2026, increasing its authorization and funding buybacks through a mix of cash flow, working capital, and debt [S2]. Finally, Corpay continues to contend with ongoing FTC litigation regarding advertising practices in its U.S. direct fuel card business, with management maintaining that the claims lack merit and are not expected to materially impact financial performance [S1].
Mechanisms Behind Corpay’s Path to Profitable Scale
Corpay’s business model is built around digitizing and automating business-to-business (B2B) payments, a market that remains highly fragmented and inefficient in many global regions. The company’s suite of solutions—ranging from accounts payable automation and cross-border payments to commercial cards and vehicle/lodging payment management—addresses both transaction processing and spend control, positioning Corpay as a value-added intermediary rather than a pure payment processor.
Revenue generation is likely a function of transaction volume, value-added service fees, foreign exchange spreads (for cross-border payments), and potentially subscription or platform access fees, though the exact commercial mechanics are not disclosed. The mix of transaction-driven and recurring revenue streams could offer a buffer against cyclical volume swings if recurring elements are material.
Operating leverage is a core opportunity. As more payment volume is routed through Corpay’s platform, incremental costs—particularly for software-driven services—should rise more slowly than revenues, supporting margin expansion. However, variable costs tied to payment processing, compliance, and customer support may constrain operating leverage if price competition intensifies or if regulatory/compliance demands escalate. The company’s ongoing investment in cybersecurity and third-party risk management is a necessary cost to maintain trust in a sensitive sector.
Assessing Corpay’s Competitive Position in a Saturated Payments Market
Corpay operates in a fiercely competitive sector populated by global payment processors, banks, fintechs, and specialized B2B platforms. Its competitive advantages may stem from its integrated suite covering multiple payment modalities, geographic reach (particularly in the U.S., Brazil, and U.K.), and technology-driven automation that offers customers superior control and reporting compared to legacy processes.
Switching costs could be meaningful for large enterprises that embed Corpay’s solutions into their procurement and financial workflows, especially if the platform offers robust integration with ERP and accounting systems. However, competition from both established financial institutions and nimble fintech startups means customer retention cannot be taken for granted. Price competition, rapid technology cycles, and evolving regulatory requirements all pose risks to margin and share.
Corpay’s ongoing investment in cybersecurity and governance is a necessary differentiator as payment fraud and cyber threats increase. The company’s broad international footprint may also provide scale advantages in cross-border payments, but exposes it to a patchwork of regulatory regimes and local competitors. The FTC litigation, while not expected to be material financially, could be leveraged by rivals to challenge Corpay’s reputation in sensitive verticals.
Potential for Margin Gains Through Scale and Digital Innovation
The bull case for Corpay is that it continues to outpace the market in digitizing B2B payments, capturing volume from manual, paper-based, or legacy electronic methods. If the company can demonstrate that incremental volumes drive disproportionately higher gross profits—due to technology-driven operating leverage—margin expansion could accelerate. Product breadth could further enable cross-selling, deepening customer relationships and raising switching costs.
A favorable scenario would be confirmed by sustained double-digit revenue growth, expanding operating margins, and evidence of growing wallet share among existing enterprise clients. Additional confirmation would come from new product launches or geographic expansions that demonstrate the company’s ability to replicate its model beyond its three core markets. A declining ratio of operating expenses to revenue, paired with stable or rising customer retention (if disclosed), would further validate the leverage thesis.
Regulatory risks would need to remain contained, with the FTC matter resolved favorably or fading as an overhang. Ongoing share buybacks could amplify EPS growth if cash generation remains robust.
Ongoing Digital Uptake Amid Margin and Regulatory Challenges
The most plausible medium-term outcome is that Corpay maintains a solid growth trajectory as B2B payment digitization continues, but faces persistent margin and operational headwinds. Competitive pricing pressure, rising compliance costs, and the need to invest in cybersecurity and regulatory management may limit the pace of margin expansion.
Revenue growth in the high-single to low-double digits could be sustained if Corpay retains its position in its core geographies and manages to incrementally grow its customer base. However, the company may need to balance technology investment, liquidity management, and capital returns (including share repurchases) without overextending its balance sheet. Resolution of the FTC litigation without material financial penalty would remove a potential overhang, but ongoing legal and regulatory costs may remain a feature of the business.
This scenario would be confirmed by steady, but not accelerating, revenue and profit growth; a stable or modestly reported liquidity-ratio trends; and continued focus on operational execution without significant negative surprises in compliance or customer retention.
Impact of Regulatory Issues or Liquidity Constraints on Growth Trajectory
The adverse scenario for Corpay involves one or more shocks: a negative outcome in the FTC litigation or other regulatory actions leading to material fines, mandated operational changes, or reputational damage; a deterioration in liquidity due to working capital stress or unexpected outflows; or a sharp slowdown in growth due to competitive encroachment or technology disruption.
If the company is forced to divert significant resources to address legal or compliance issues, this could constrain technology investment, slow innovation, and erode customer trust. A persistent current ratio below 1.0, especially if cash outflows accelerate, could force Corpay to curtail share buybacks, raise outside capital, or even divest non-core assets.
This scenario would be confirmed by rising legal or compliance expenses, negative news flow regarding regulatory outcomes, customer attrition, or a significant deceleration in top-line growth. An observable increase in short-term borrowing or working capital draws (if disclosed) would further support the downside thesis.
Elements Shaping Corpay’s Capacity to Expand and Maintain Market Standing
Sustained revenue growth rates in the double digits, particularly in core markets and new geographies, would help test whether Corpay is capturing share from legacy payment modalities.
Operating margin trends and the ratio of operating expenses to revenue, as disclosed, will show whether the company is achieving operating leverage or facing rising cost pressures.
The resolution, escalation, or any financial impact of the FTC litigation and any new regulatory actions should be monitored for potential disruption.
Customer retention rates and share of wallet among key enterprise clients—if disclosed—would provide insight into switching costs and competitive stickiness.
Product launch cadence and adoption rates in new or adjacent markets would help gauge Corpay’s ability to innovate and expand its addressable market.
Cybersecurity incident disclosures or third-party audit outcomes would be critical to track given the sensitivity of the payments sector.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments