
Solventum’s Strategic Crossroads: Diversified Healthcare, Earnings Momentum, and the Implications of a Pending Portfolio Shift
Solventum’s broad healthcare portfolio and global reach underpin recent operational outperformance, but a strategic review of its Health Information Systems segment and ongoing profitability challenges spotlight the company’s evolving risk-reward profile. The next phase will hinge on segment focus, innovation yield, and the outcome of portfolio realignment.
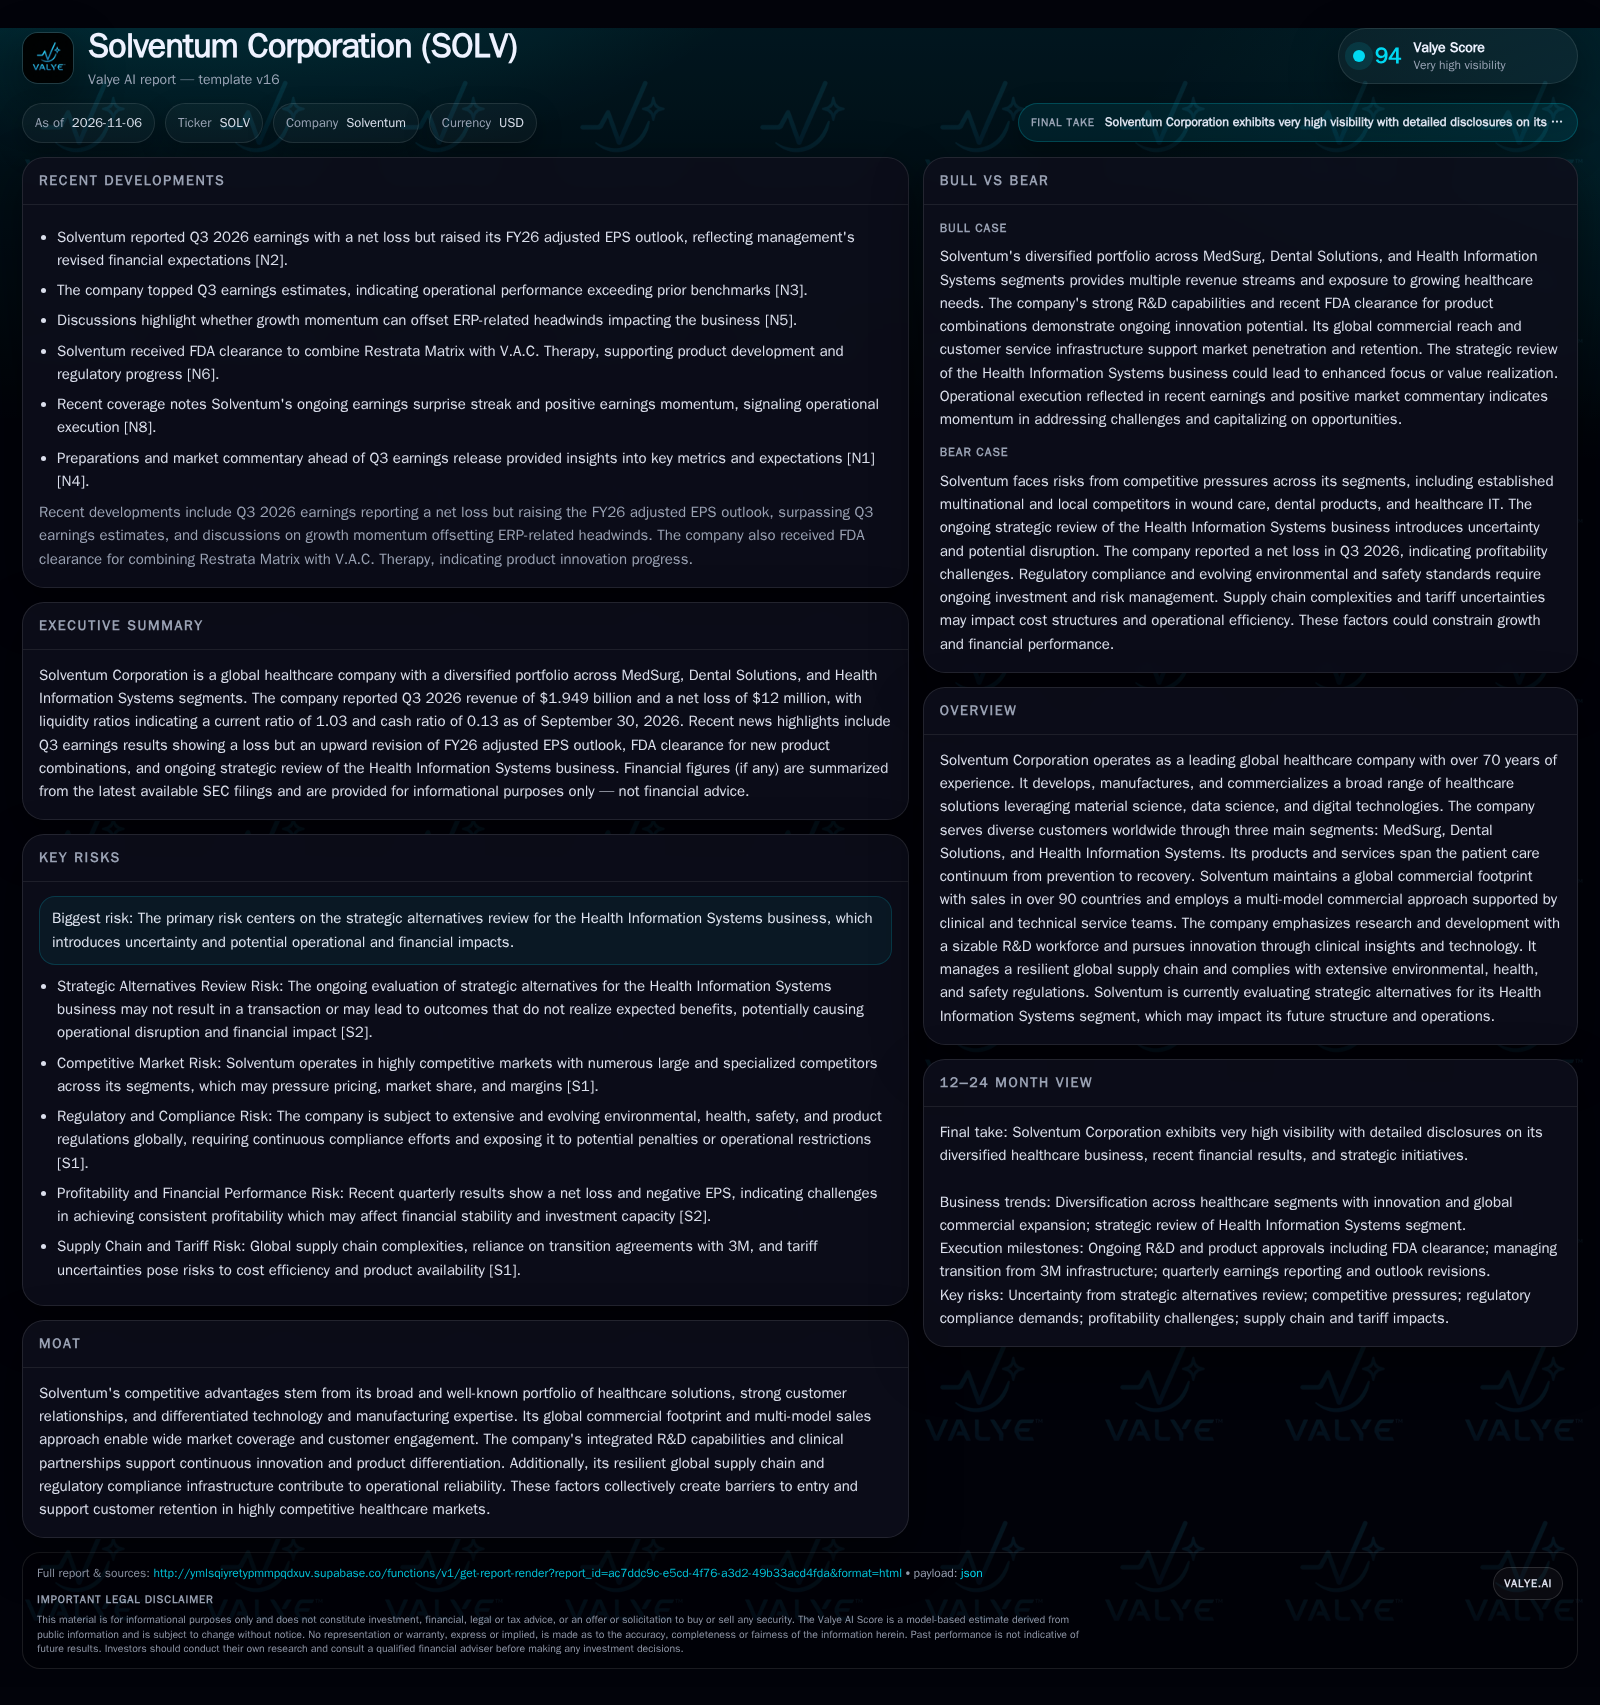
Solventum reported stronger-than-expected Q3 2026 results, raising its FY26 adjusted EPS outlook despite a net loss. Its MedSurg and Dental Solutions segments anchor a diverse portfolio, while the Health Information Systems unit faces a strategic review that could reshape the company. Execution on innovation, supply chain resilience, and clarity around the portfolio review are likely to determine the sustainability of recent momentum. [S2] [N2] [N3]
Solventum Corporation stands at a pivotal moment: its diversified healthcare platform is delivering operational wins, evidenced by a raised full-year EPS outlook and an ongoing streak of earnings surprises, even as profitability remains elusive. The company’s dominant MedSurg segment, supported by Dental Solutions and a technology-driven Health Information Systems unit, provides both breadth and optionality. However, with the Health Information Systems segment under strategic review, Solventum’s near-term trajectory could shift dramatically. The interplay between innovation, cost structure, and the outcome of this portfolio review will likely determine whether recent momentum can translate into durable value creation.
Recent Results and Strategic Moves: What’s Shaping Solventum Right Now
Solventum reported Q3 2026 revenue of $1.949 billion and a net loss of $12 million, with basic and diluted EPS at -$0.07. Despite the loss, management raised its full-year adjusted EPS outlook, citing operational progress that outpaced expectations. This suggests internal confidence in cost controls or revenue growth, even as the company faces ongoing ERP-related headwinds. The Health Information Systems segment is undergoing a strategic alternatives review, which introduces substantial uncertainty around future revenue composition and operational focus. These developments are occurring against the backdrop of a global footprint, with the MedSurg segment generating the majority of sales and Dental Solutions and Health Information Systems providing additional diversification. Recent headlines highlight an earnings surprise streak, indicating that operational execution has, at least for now, offset some structural challenges. [S2] [N2] [N3] [N5] [N8]
The Economics of Diversification: Segment Mix, Margin Levers, and Cost Structure
Solventum’s business model spans consumables, devices, and software, each with distinct economic profiles. The MedSurg segment—its largest—likely benefits from recurring demand for wound care and surgical supplies, which historically offer stable but competitive margins. Dental Solutions, while smaller, serves both procedure-driven and ongoing care markets, potentially supporting higher per-unit margins but also facing intense pricing pressure from global competitors. The Health Information Systems segment introduces a software and services model, which, if structured as a subscription or recurring revenue business, could contribute higher gross margins and operating leverage if scaled successfully.
Operating leverage in this context is mixed: manufacturing and distribution scale in MedSurg and Dental Solutions can lower unit costs, but R&D, regulatory compliance, and complex supply chains create significant fixed costs. In Health Information Systems, software development and support costs are partially fixed, but margins can expand with adoption. The company’s sizable R&D investment (about 2,000 employees) underlines a bet on innovation to drive future pricing power and differentiation. However, the current net loss signals that Solventum’s cost base—whether from transition costs, integration expenses, or underperforming segments—remains a drag on profitability. If the Health Information Systems review results in divestiture or restructuring, the company’s fixed-cost base and capital allocation priorities could change materially.
Competing Across Healthcare: Strengths, Threats, and the Search for Defensible Niches
Solventum’s competitive position is rooted in a broad solution set, robust customer relationships, and global reach. The MedSurg business faces competition from both multinational device makers and specialized wound care firms—categories characterized by price-based competition, clinical differentiation, and bundled procurement. Dental Solutions must contend with established dental manufacturers and regional players, where innovation cycles and practitioner loyalty can drive share shifts. Health Information Systems operates in an intensely fragmented landscape, with competition ranging from large health IT vendors to agile, niche software providers.
Potential sources of advantage for Solventum include its multi-channel sales infrastructure (direct, distribution, e-commerce), integrated clinical support, and an R&D engine capable of incremental and step-change innovation. However, the company’s reliance on transition agreements with 3M during its operational separation could be a double-edged sword: it provides stability in the near term but may constrain agility or cost optimization post-transition. Regulatory compliance and global supply chain resilience are also necessary but not sufficient for long-term moat maintenance, especially as digital and software-based healthcare solutions become more prominent.
Innovation and Portfolio Focus Unlock Value: The Bullish Chain of Events
A favorable scenario for Solventum would see its MedSurg and Dental Solutions segments leveraging innovation to capture share in core markets, while the Health Information Systems review culminates in a value-creating outcome—such as a divestiture at an attractive multiple or a refocused, higher-margin software business. Operational improvements, supply chain resilience, and successful management of ERP-related disruptions could translate rising revenue into sustained earnings growth.
Evidence that would confirm this scenario includes: continued earnings beats and upward revisions to guidance, successful launches of differentiated products (such as new wound care technologies or digital dental tools), margin expansion in core segments, and a clearly communicated and well-received outcome for the Health Information Systems review (e.g., a premium sale, strategic partnership, or credible plan for margin improvement). A return to consistent profitability and robust free cash flow would reinforce the thesis.
Portfolio Realignment Amid Margin Pressure: The Most Plausible Trajectory
The most likely outcome is that Solventum continues to deliver mid-single-digit revenue growth, anchored by its MedSurg and Dental Solutions franchises, while Health Information Systems remains a source of strategic uncertainty and margin drag. The strategic review could result in a sale, spin-off, or internal restructuring, but the process may take time and carry associated costs or operational distractions. ERP-related and supply chain headwinds are likely to persist, offsetting some of the gains from innovation and operational execution.
Confirmation would come from stable or slightly improving margins, ongoing modest earnings surprises, and incremental progress on the Health Information Systems review (such as updates on bids, restructuring plans, or cost takeout initiatives). Falsification would involve worsening profitability, customer attrition in core segments, or a failed or value-destructive outcome from the Health Information Systems process.
Strategic Uncertainty and Cost Rigidities Derail Progress
In a negative scenario, the Health Information Systems review results in either a failed sale, a value-destructive divestiture, or prolonged internal disruption, eroding management focus and investor confidence. Margin pressure in MedSurg or Dental Solutions—driven by competitive pricing, supply chain cost inflation, or regulatory changes—could compound losses. If ERP-related issues persist or escalate, operational inefficiencies could further erode earnings.
This scenario would be confirmed by a reversal of the earnings surprise trend, downward guidance revisions, customer or market share losses, and/or adverse outcomes from the Health Information Systems review. Prolonged net losses and negative free cash flow would likely force a reassessment of the company’s capital structure or long-term strategic direction.
What Will Determine Solventum’s Next Phase of Value Creation?
Progress and outcome of the Health Information Systems strategic alternatives review, including terms of any divestiture, restructuring, or retained business model.
Trends in gross and operating margins by segment—especially evidence of margin expansion or contraction in MedSurg and Dental Solutions (if disclosed).
Sustained ability to beat or meet quarterly earnings guidance and the underlying drivers (volume, pricing, mix, cost controls).
R&D pipeline productivity, as indicated by new product launches, regulatory clearances, or adoption of clinically differentiated offerings.
Resolution and impact of ERP-related headwinds on operational efficiency, customer service, and supply chain reliability.
Changes in customer retention or share trends within key hospital, dental, and health system accounts (if disclosed).
Evolution of the company’s liquidity position and capital allocation policy, especially in the event of a major portfolio transaction.
Any regulatory, tariff, or supply chain shocks that could alter cost structure or product availability.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments