
Clinuvel Pharmaceuticals: Product Development, Profit Pressures, and the Strategic Stakes of Dividend Continuity
Clinuvel Pharmaceuticals maintains reported liquidity position and has filed a regulatory dossier for NEURACTHEL® Instant, signaling ongoing product development.
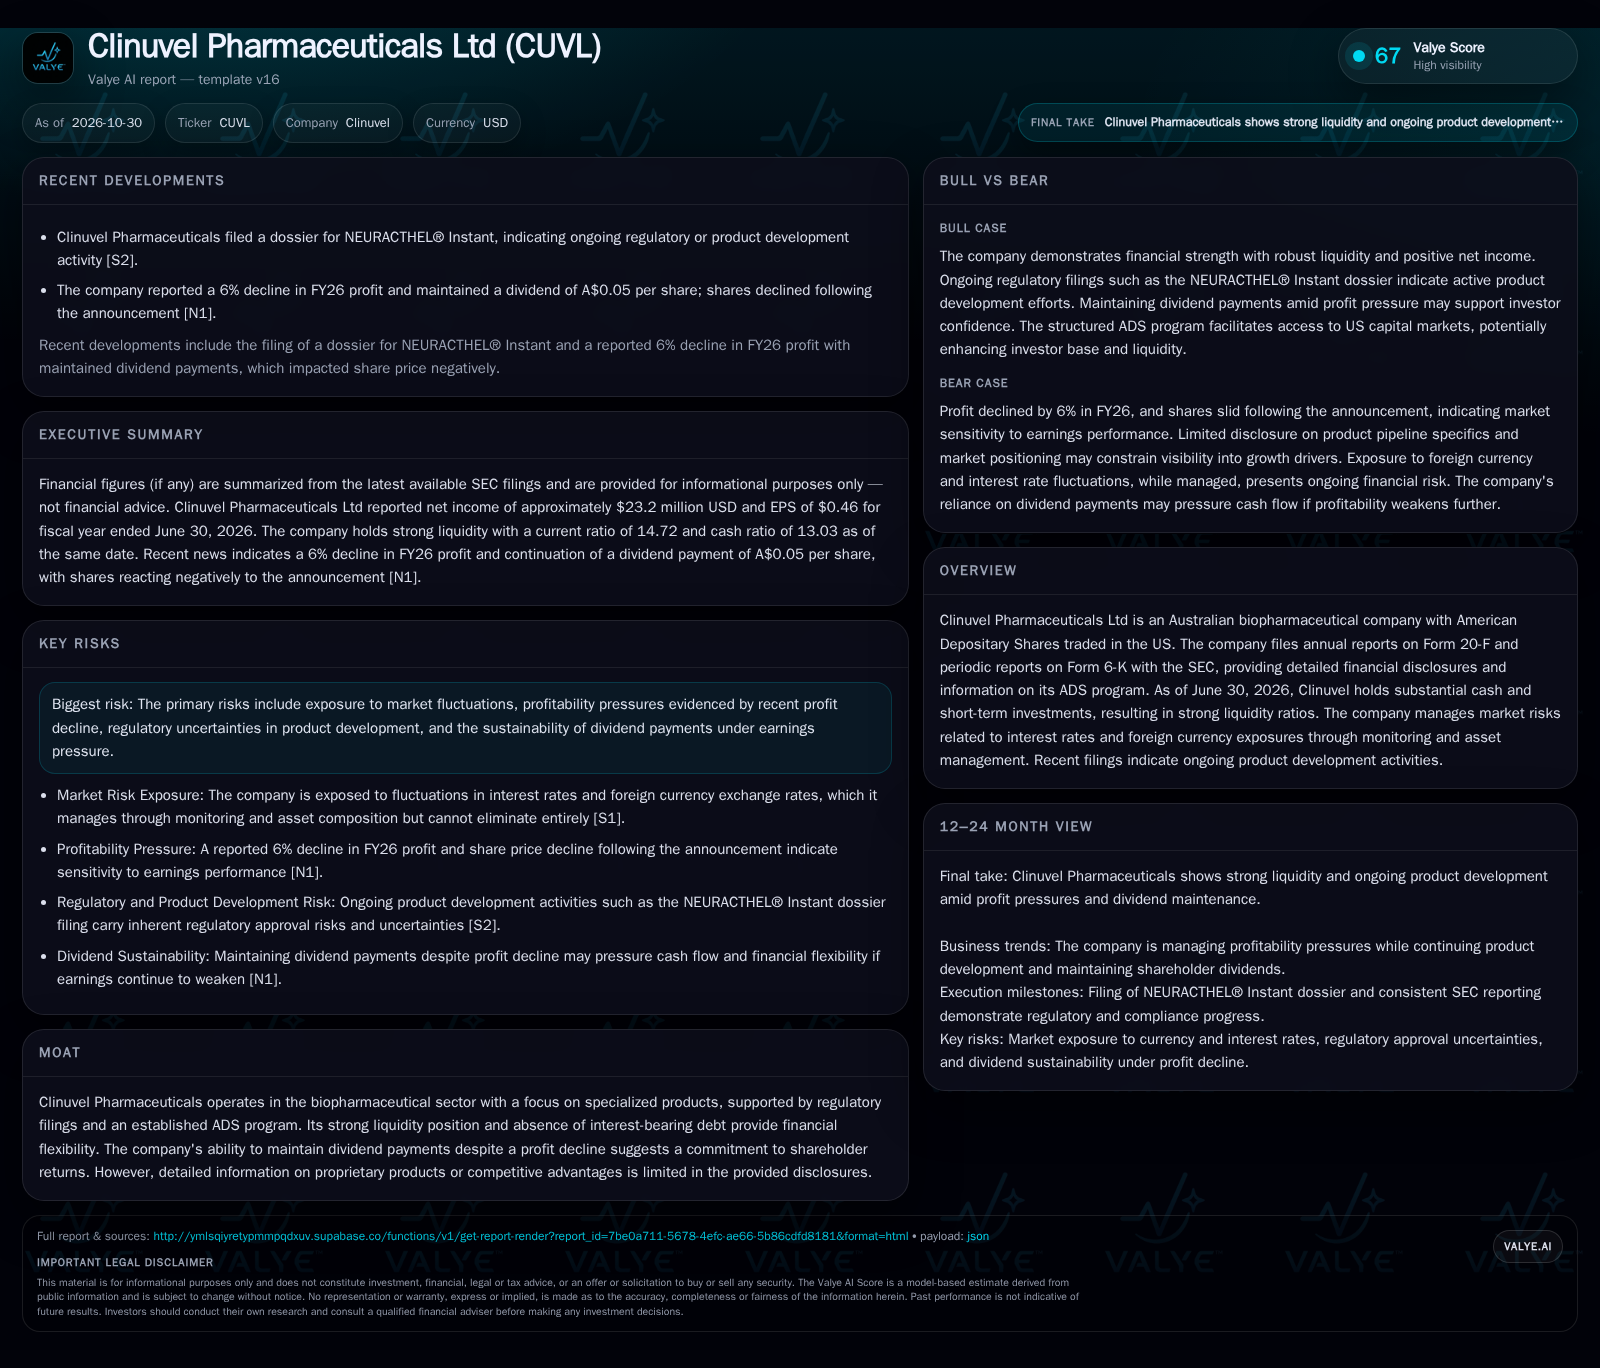
Clinuvel Pharmaceuticals maintains reported liquidity position and has filed a regulatory dossier for NEURACTHEL® Instant, signaling ongoing product development. However, a 6% profit decline in FY26 and negative share reaction to maintained dividends highlight pressures on earnings and market expectations. The company’s ability to translate its financial strength into sustainable growth and defend its position amid sector uncertainties remains the central question for investors. [S1] [S2] [N1]
Clinuvel Pharmaceuticals stands at a pivotal crossroads: it boasts a formidable liquidity position and continues to advance its product pipeline, as evidenced by the recent NEURACTHEL® Instant dossier filing. Yet, a 6% year-over-year profit decline and a negative market response to its maintained dividend underscore the tension between defending shareholder returns and navigating sector headwinds. The company’s challenge now is to leverage its financial strength into durable growth while managing regulatory risk and market expectations in the face of intensifying competition and profitability pressures. [S1] [S2] [N1]
Recent Financial and Regulatory Developments Reshape the Investment Narrative
Clinuvel Pharmaceuticals reported a net income of $23.2 million USD for fiscal 2026, with basic and diluted EPS of $0.46, yet this represented a 6% decline in profit compared to the prior year. The company’s balance sheet remains robust, with $13.9 million USD in cash and $160.1 million USD in short-term investments, yielding a current ratio of 14.72 and a cash ratio of 13.03. Notably, the company has no interest-bearing debt, which provides significant potential financial flexibility. In August 2026, Clinuvel maintained its dividend at A$0.05 per share despite shrinking profits, a decision that coincided with a drop in share price, reflecting investor concerns over earnings momentum. Additionally, the recent filing of a regulatory dossier for NEURACTHEL® Instant signals active product development and pursuit of new revenue streams. [S1] [S2] [N1]
How Clinuvel’s Revenue Model and Cost Structure Could Evolve
Clinuvel’s economics hinge on the commercialization of specialized biopharmaceutical products, likely focused on rare and underserved indications where pricing power can be meaningful, but market size may be constrained. Revenue growth historically depends on product launches, regulatory approvals, and the uptake of novel therapies. High gross margins are typical in this sector if products achieve market exclusivity, but fixed costs such as R&D, regulatory, and commercial infrastructure can create operating leverage—magnifying both upside from successful launches and downside from delays or failures.
However, maintaining a dividend amid profit contraction could constrain reinvestment flexibility if earnings pressure persists. Without interest-bearing debt, Clinuvel avoids interest expenses, but growth remains tied to internal cash generation or potential equity issuance for larger initiatives. The cited source reports dividend-related activity; that disclosure alone does not establish dividend-policy continuity, management confidence, or a material constraint on capital flexibility.
The recent NEURACTHEL® Instant dossier filing suggests Clinuvel is investing in pipeline expansion, which could provide new revenue streams but also entails lengthy regulatory timelines and significant upfront costs. The challenge for the company is to balance these investments with ongoing shareholder returns and to ensure that operating leverage works in its favor as new products reach the market.
Competitive Dynamics in Rare Disease Pharmaceuticals and the Strategic Value of Pipeline Progress
Clinuvel operates in the highly competitive biopharmaceutical sector, where differentiation often derives from proprietary products targeting rare or underserved conditions. The sector is characterized by high barriers to entry due to regulatory complexity and the specialized nature of therapy development, but competitors—ranging from large pharma to nimble biotech—are continuously seeking similar opportunities.
In this environment, sustainable competitive advantage typically depends on pipeline breadth, speed of development, regulatory execution, and the ability to secure reimbursement at premium price points. The filing of the NEURACTHEL® Instant dossier may position Clinuvel for a new product launch, which could bolster its competitive standing if approved. However, without detailed disclosure on the pipeline or product exclusivity, it is uncertain whether Clinuvel’s portfolio is sufficiently differentiated to secure durable market share.
The real test is whether the company can convert its financial strength into pipeline progress and commercial success faster than competitors with similar or greater resources. Substitution risk is present if other companies develop more efficacious or cost-effective therapies for the same indications.
Pipeline Success and Regulatory Approvals Unlock New Growth and Margin Expansion
In a favorable scenario, Clinuvel’s investment in NEURACTHEL® Instant and other pipeline assets results in successful regulatory approvals and timely commercial launches. This would enable the company to access new patient populations, expand its addressable market, and potentially command premium pricing due to first-mover advantages or unmet medical need. As new products ramp, operating leverage could drive margin expansion, with incremental revenue flowing to the bottom line given the high fixed-cost base.
Upside would be confirmed by positive regulatory decisions, strong initial uptake of NEURACTHEL® Instant (if approved and launched), and evidence of increasing revenue contribution from new products. Sustained or growing dividends alongside profit recovery would further validate the ability to balance growth investment with shareholder returns. Additional pipeline disclosures, strategic partnerships, or licensing deals would also support the upside thesis by diversifying revenue sources and mitigating single-product risk.
Balancing Incremental Pipeline Progress with Ongoing Earnings Pressure
The most plausible middle path is that Clinuvel continues to invest in its pipeline while experiencing modest near-term earnings pressure. Revenue from existing products may plateau or grow slowly, with profitability constrained by ongoing R&D and regulatory spending. Dividend payments are maintained, but further increases are unlikely until new products contribute meaningfully to earnings.
This scenario would be confirmed by stable or slightly declining net income, continued high liquidity ratios, and incremental regulatory milestones (such as dossier acceptances or phase advancements) without immediate commercial impact. The absence of major product setbacks or regulatory rejections would keep this scenario intact.
Profit Erosion, Pipeline Delays, and Dividend Strain Threaten Strategic Flexibility
In an adverse scenario, Clinuvel faces further profit erosion due to stagnating or declining core product sales, compounded by delays or failures in bringing new products like NEURACTHEL® Instant to market.
Downside would be confirmed by a continued decline in net income, a spike in R&D costs without offsetting revenue gains, and regulatory setbacks such as dossier rejections or prolonged review timelines. Evidence of cash burn accelerating or liquidity ratios deteriorating—especially if dividend payments are maintained despite shrinking profits—would indicate rising financial strain. Any signals of cost-cutting in R&D or commercial activities could further suggest that management is reacting defensively rather than investing for growth.
What Will Determine If Clinuvel’s Financial Strength Translates to Lasting Value?
Progress and regulatory outcomes for NEURACTHEL® Instant, including dossier acceptance, review timelines, and—if disclosed—commercial launch dates.
Quarterly or semi-annual net income trends, especially the trajectory relative to dividend payments and R&D investment.
Updates on product pipeline breadth and stage, including additional filings, phase advancements, or regulatory news.
R&D and SG&A spending trends, which would indicate management’s commitment to pipeline progress versus cost containment.
Any disclosed commercial partnerships, licensing deals, or market expansion initiatives that could diversify revenue sources.
Liquidity and working capital trends, particularly if cash and short-term investments begin to decline faster than anticipated.
If disclosed, new product uptake rates and revenue contributions post-launch of NEURACTHEL® Instant or other pipeline assets.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments