
DUKE Robotics: Dual-Use Drone Platforms, Commercialization Stakes, and the Economics of Scaling Niche Robotics
DUKE Robotics Corp. straddles military and civilian drone applications with proprietary stabilization technology and a flagship defense partnership. Recent commercial deployments and new leadership signal momentum, but the company’s modest revenue base and reliance on key channels underscore the challenge of scaling profitably in specialized, regulation-heavy markets.
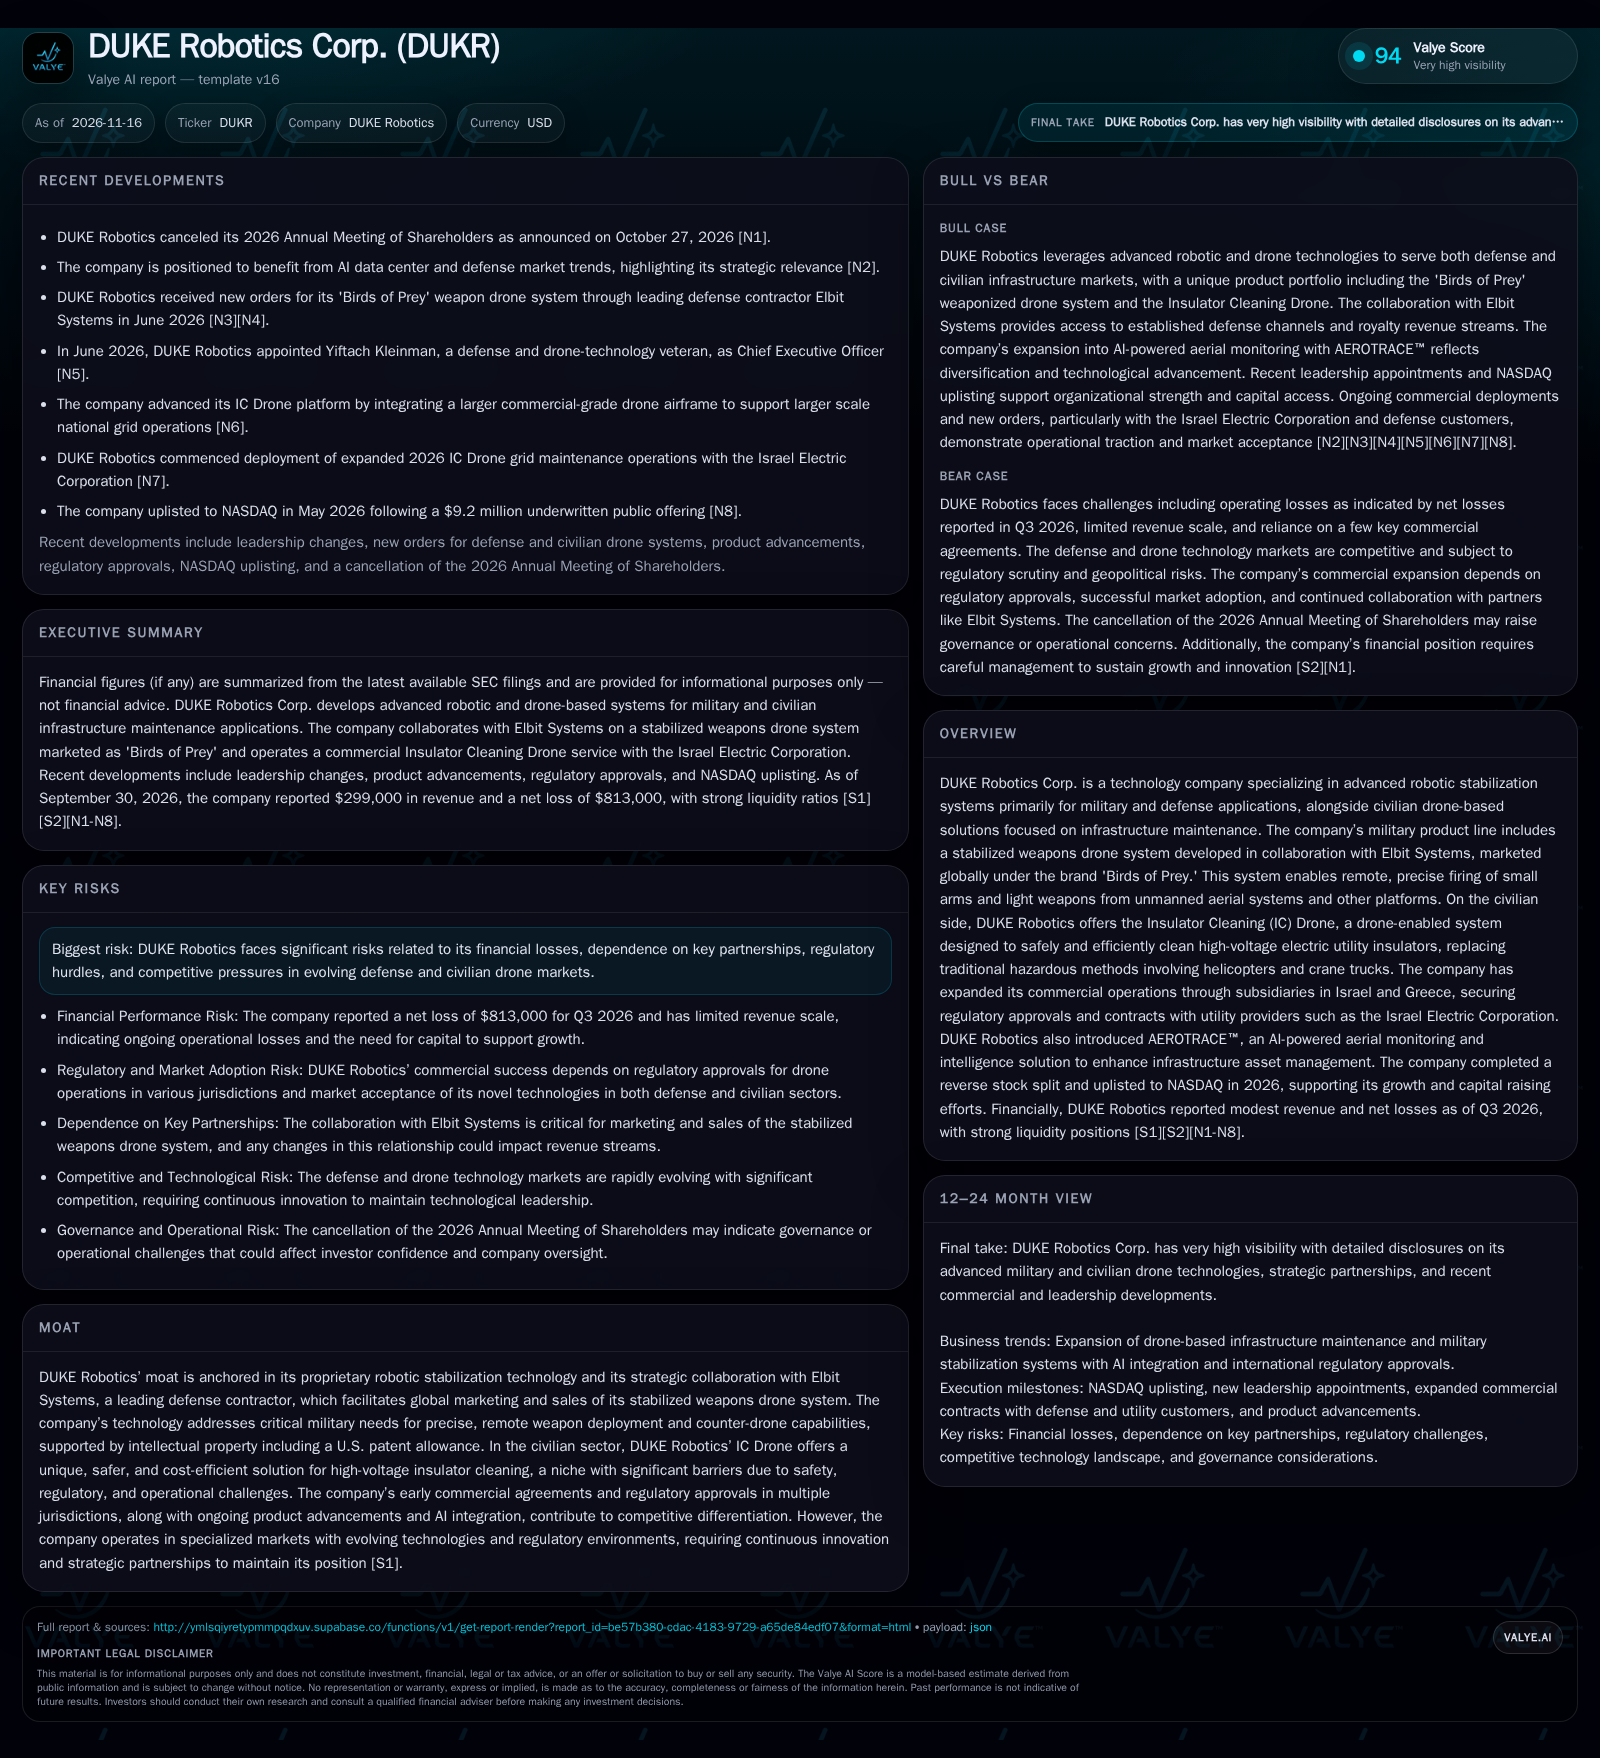
DUKE Robotics is commercializing advanced drone platforms for both defense and civilian infrastructure maintenance. The company’s military-grade stabilized weapons drone is sold through a royalty-bearing collaboration with Elbit Systems, while its Insulator Cleaning Drone is deployed with Israel Electric Corporation and now features enhanced capabilities. Despite achieving regulatory milestones, expanded orders, and a NASDAQ uplisting, DUKE remains in an early revenue phase with ongoing losses and high dependence on select customers and partners. Execution on global expansion and broadening its product base will be critical to validating its business model and achieving sustainable profitability. [S1] [S2] [N3] [N4] [N7] [N8]
DUKE Robotics Corp. operates at the intersection of advanced robotics, drone technology, and dual-use applications. With products spanning weaponized drones for military use and specialized systems for civilian infrastructure maintenance, DUKE is seeking to carve out defensible niches in two highly regulated, capital-intensive markets. Recent commercial wins, the launch of next-generation platforms, and a NASDAQ uplisting point to strategic momentum, but the company’s modest revenue and persistent losses highlight the challenges of moving from technical validation to commercial scale. The real test will be DUKE’s ability to expand beyond initial deployments and partnerships, manage regulatory complexity, and demonstrate that its differentiated technology can command pricing power and recurring revenue in both defense and critical infrastructure verticals.
Recent Orders, Product Upgrades, and a New Leadership Era: Where DUKE Robotics Stands Now
DUKE Robotics enters late 2026 with several pivotal developments: the company reported Q3 revenue of $299,000 and a net loss of $813,000, reflecting an early commercialization phase and ongoing operating losses.Cash and equivalents stood at $6.4 million after a $9.2 million NASDAQ public offering and a 25-for-1 reverse split, giving DUKE a reported current ratio of 10.68 and cash ratio of 10.17 as of September 30, 2026 [S2] [N8].
Operationally, DUKE recorded new orders for its 'Birds of Prey' stabilized weapons drone system through its collaboration with Elbit Systems, indicating continued demand in the defense segment [N3] [N4]. On the civilian side, expanded deployment of the IC Drone with Israel Electric Corporation (IEC) and the launch of the upgraded ICDS2 platform signal ongoing traction in utility infrastructure maintenance [S1] [N7].
The appointment of industry veteran Yiftach Kleinman as CEO in June 2026 marks a leadership shift aimed at driving both commercialization and technology strategy [N5]. The introduction of AEROTRACE™, an AI-driven aerial monitoring product, shows DUKE’s intent to diversify into data-driven infrastructure solutions [S1].
How DUKE’s Dual-Use Platform Model Could Unlock Operating Leverage
DUKE Robotics’ business model is built around two primary revenue streams: royalties and commissions from military drone sales (via Elbit Systems) and direct sales or service contracts for civilian drone platforms targeting utility infrastructure. The military segment leverages DUKE’s proprietary stabilization technology, but the company is not the direct seller; instead, it depends on royalties and commissions from Elbit, which likely constrains both margin and control over volume and pricing [S1] [N3] [N4]. In the civilian market, the IC Drone is sold or deployed as a service to utilities, with the Israel Electric Corporation contract providing proof-of-concept and ongoing revenue extensions [S1] [N7].
The economics of these models diverge: defense royalties may provide high-margin, lumpy revenue but with limited visibility and dependence on partner success; civilian contracts could offer more recurring, predictable revenue if DUKE secures multi-year agreements or scales to additional utilities. The recent launch of the ICDS2 and AEROTRACE™ suggests an effort to move up the value chain by integrating AI analytics and expanding addressable use cases, potentially enabling higher pricing or bundled service models.
Operating leverage remains limited at current scale: Q3 2026 revenue of $299,000 is dwarfed by ongoing costs, resulting in persistent net losses [S2]. The capital raised from the public offering provides a cushion for further R&D and business development, but DUKE’s ability to reach break-even will depend on either significant order volume (military or civilian), higher-margin service offerings, or expansion into new geographies.
Where DUKE Robotics Sits in the Drone and Robotics Competitive Landscape
DUKE’s competitive position is shaped by its proprietary stabilization technology and its dual focus: weaponized drones for defense and specialized cleaning drones for utilities. In defense, the collaboration with Elbit Systems provides a channel to global military customers and leverages Elbit’s established relationships and credibility. However, this also makes DUKE reliant on a single, powerful partner for market access and subject to the priorities and procurement cycles of national defense customers.
The civilian infrastructure market is less crowded but not without alternatives: utilities traditionally use helicopters, cranes, or manual crews for insulator cleaning. Competing drone solutions, if they emerge, would need to match DUKE’s safety, stability, and regulatory credentials. The company’s early regulatory approvals in Israel and Greece, and operational track record with IEC, offer first-mover advantages, but switching costs for utilities may be moderate if competing technologies gain traction or regulatory standards evolve.
The integration of AI analytics via AEROTRACE™ and the push into European and US markets could help DUKE differentiate further, but the company faces competition from established industrial drone providers and specialized robotics startups, many of which are also layering AI into their offerings. The real moat may depend on a combination of technical performance, regulatory approval, and deep integration with customer workflows—rather than pure hardware or software IP.
From Niche Deployments to Platform Adoption: What Would Drive Sustainable Growth?
A favorable scenario for DUKE Robotics would see rapid scaling of both military and civilian business lines. On the defense side, a material increase in 'Birds of Prey' orders through Elbit—potentially driven by rising geopolitical tensions or expanded adoption by NATO-aligned militaries—could deliver high-margin royalty streams and enhance DUKE’s brand as a leading provider of weaponized drone stabilization.
In the civilian sector, successful expansion beyond Israel Electric Corporation, particularly into European and US utilities, would provide recurring revenue, validate the IC Drone’s value proposition, and demonstrate the scalability of the service or platform model. The ICDS2’s improved performance and AEROTRACE™’s analytics capabilities could unlock premium pricing or new data-as-a-service revenue streams.
Evidence that would confirm this scenario includes: multi-year, multi-customer civilian contracts; a step-change in order volume from Elbit; public reference customers in new geographies; and a shift to positive operating cash flow. Falsification would come from stagnating order growth, loss of key contracts, or inability to penetrate new markets.
Early-Stage Commercialization with Gradual Expansion and Persistent Volatility
The most plausible trajectory is that DUKE continues to advance incremental deployments in both its military and civilian segments, but revenue remains lumpy and below the threshold for profitability over the next 12-24 months. The Elbit partnership provides episodic defense royalties, while the IEC contract and potential European pilots anchor the civilian business, but neither segment achieves rapid scale without further channel and customer wins.
Ongoing R&D and product upgrades consume cash, offset by the capital raised, but DUKE faces regular pressure to prove commercial traction and convert proof-of-concept wins into broader adoption. Margins may improve modestly if service-based or analytics-driven revenues grow, but the company remains exposed to contract concentration risk and the cyclical nature of defense procurement.
This scenario would be confirmed by continued contract extensions, slow but steady expansion into new markets, and quarterly financials that show gradual revenue growth but ongoing operating losses. Failure to secure new anchor customers or diversify revenue streams would signal downside risk.
Reliance on Key Partners and Limited Commercial Scale Could Constrain Viability
The adverse scenario for DUKE would involve stagnation or contraction in both main business lines. If Elbit Systems reduces orders or shifts focus, DUKE’s military royalties could decline sharply, exposing the company’s dependence on a single partner and limiting its ability to invest in new technology or market development.
On the civilian front, failure to win additional contracts beyond IEC—or loss of regulatory approval in key jurisdictions—would cap revenue at sub-scale levels and impede the company’s ability to achieve operating leverage. Increased competition, technological obsolescence, or regulatory hurdles could further erode DUKE’s position.
Confirmation of this scenario would include declining or flat revenue, loss of IEC or Elbit as anchor customers, significant cash burn without offsetting growth, or inability to enter new markets. Early warning signs may also include product development delays, failed regulatory bids, or negative customer feedback.
Testing the Thesis: What Will Reveal DUKE Robotics’ Commercial and Strategic Trajectory?
The volume and frequency of new orders for the 'Birds of Prey' system through Elbit Systems, and any indication of expanded adoption by new military customers.
The number, size, and duration of civilian contracts for the IC Drone platform, especially outside of Israel—multi-year, multi-utility deals would be strong validation.
Progress in regulatory approvals and operational authorizations for drone deployments in new geographies, particularly in the US and EU.
Revenue mix evolution: the proportion of income derived from defense royalties versus direct civilian contracts or data/analytics services.
Cash burn rate and quarterly operating loss trends, especially as they relate to the $6.4 million cash balance and the need for future capital raises.
Product development milestones, including the commercial impact of the ICDS2 upgrade and the adoption of AEROTRACE™ in pilot or production environments.
Customer concentration: dependence on Elbit and IEC versus a growing, diversified customer base—if disclosed.
Any changes in the Elbit partnership structure, contract terms, or royalty/commission rates, which could materially alter DUKE’s economics.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments