
FuboTV After the Hulu Live Combination: Scale, Synergies, and the Search for Profitable Growth
The union of FuboTV and Hulu + Live TV has created a major force in U.S. streaming, but the path to sustainable profitability hinges on integration execution, debt management, and the ability to drive higher-margin advertising and subscriber monetization in a fiercely competitive market.
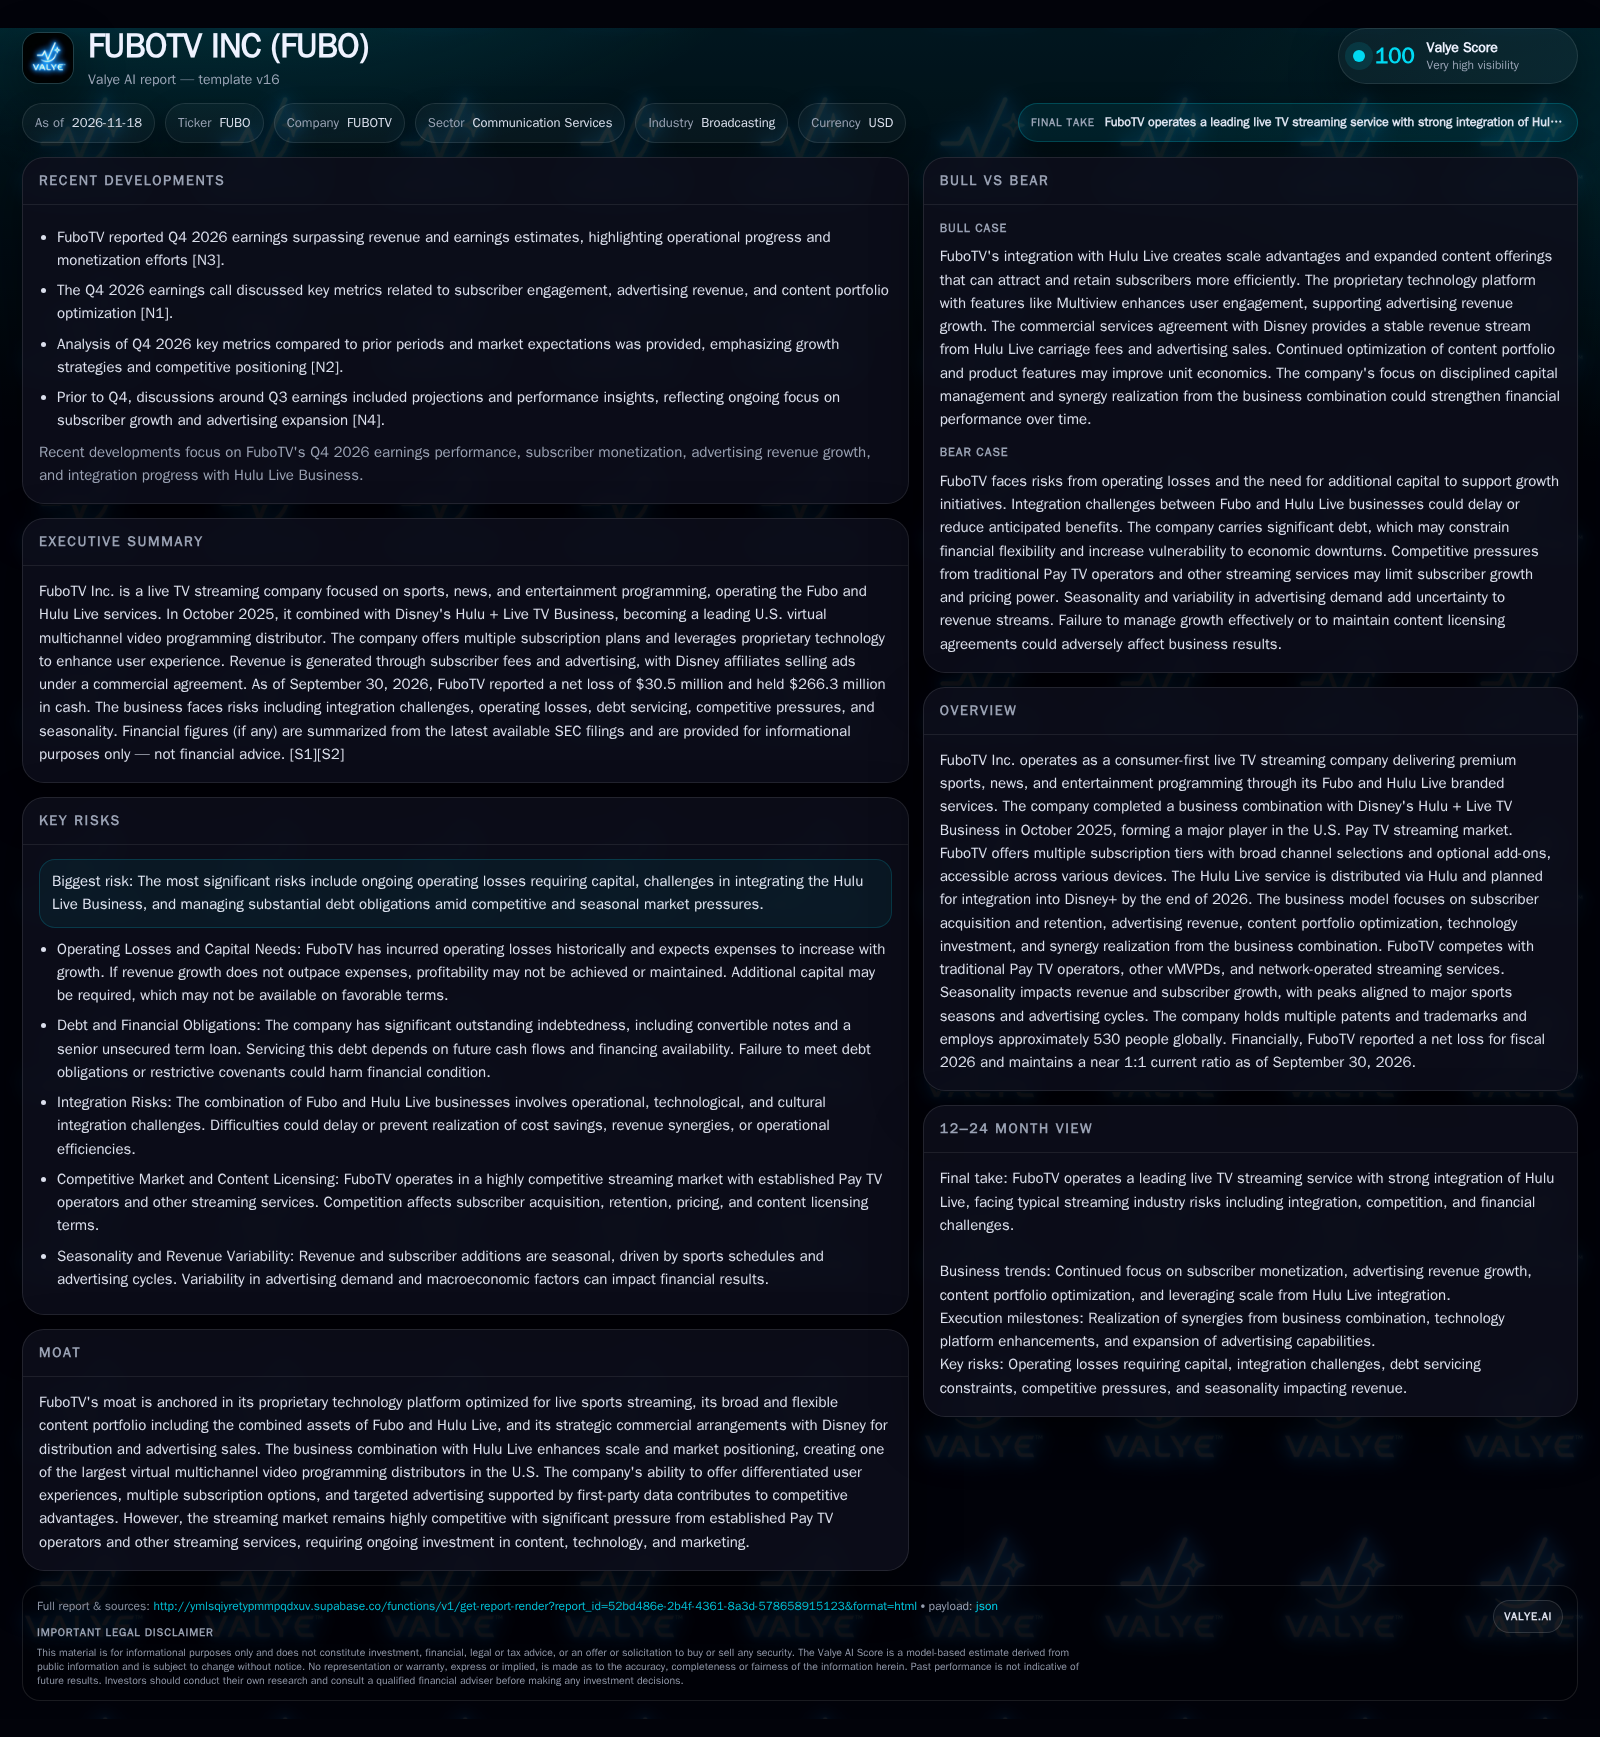
FuboTV’s combination with Hulu + Live TV vaults it into the top ranks of U.S. Pay TV streaming, bringing scale and a broadened content portfolio. The business now benefits from a significant wholesale revenue arrangement with Disney, expanded advertising opportunities, and a proprietary technology platform. Yet, the company faces continued operating losses, substantial debt, and integration risks. The next phase will test whether FuboTV can deliver on promised synergies, contain costs, and capture value from its expanded reach amid intense competition and shifting consumer preferences. [S1] [S2] [N3]
FuboTV’s transformation from a niche sports-focused streaming service to a scale player in U.S. Pay TV was catalyzed by its 2025 merger with Hulu + Live TV. This move instantly broadened FuboTV’s content portfolio and subscriber base, positioning it as the sixth largest Pay TV provider and the second largest vMVPD in the country. However, with scale comes complexity: FuboTV must now integrate two large businesses, manage substantial debt, and carve out sustainable margins in a streaming market defined by high content costs and relentless competition. The coming quarters will reveal whether the company can convert scale into durable value—or if integration and market headwinds will erode its growth ambitions.
How the Hulu Live Merger Is Shaping FuboTV’s Business Model and Financial Profile
The October 2025 combination of FuboTV with Disney’s Hulu + Live TV business is the pivotal recent development, creating the U.S.’s second-largest virtual multichannel video programming distributor (vMVPD) and the sixth largest overall Pay TV company. This strategic move instantly expanded FuboTV’s subscriber footprint and content library, particularly in sports, news, and entertainment programming. The immediate financial impact is visible in the company’s latest figures: as of September 30, 2026, FuboTV reported $266.3 million in cash, a current ratio of 0.99, and a net loss of $30.5 million for the fiscal year, with $322.8 million in debt outstanding. [S1] [S2]
Crucially, the newly acquired Hulu Live segment operates under a wholesale fee arrangement with Disney, in which Disney pays FuboTV a percentage of Hulu Live’s carriage fee expenses—starting at 95% in 2025-2026 and rising to 99% by 2028. This structure provides revenue visibility but leaves limited incremental margin, meaning FuboTV’s path to profitability likely depends on driving higher-margin revenue streams such as advertising and premium add-ons. Integration efforts and synergy realization, meanwhile, remain a major operational focus and risk. [S1] [S2]
Revenue Streams, Cost Pressures, and the Challenge of Margin Expansion
FuboTV’s revenue model rests on two pillars: subscription fees from its Fubo and Hulu Live branded packages, and advertising revenue generated via both in-house and Disney affiliate sales. The company offers a range of tiered subscription plans (Sports, Pro, Elite, Latino, etc.) with optional add-ons, allowing for some ARPU (average revenue per user) optimization. However, the core Hulu Live business is accounted for via a wholesale contract, providing FuboTV with a fixed percentage of Hulu Live’s carriage fee expenses and thus limiting upside from direct price increases or margin expansion on that segment. [S1]
Advertising revenue is positioned as a key lever for margin improvement, with Disney affiliates selling ad inventory and sharing proceeds. This arrangement could benefit from increased scale and first-party data, but is also sensitive to macroeconomic advertising cycles and the effectiveness of ad targeting. Content costs—especially for sports rights—remain a substantial fixed expense, and the combined business is exposed to high operating leverage: subscriber growth and ARPU expansion can drive profitability, but churn, content inflation, or underwhelming ad demand can quickly erode margins. The company’s $322.8 million in debt and history of operating losses underscore the need for disciplined capital allocation and cost control. [S1] [S2]
Where FuboTV Stands Among Streaming Giants and Traditional Pay TV
FuboTV now competes head-to-head with both legacy Pay TV operators (such as DIRECTV and Comcast) and digital-native vMVPDs like YouTube TV and Sling TV. It also faces pressure from network-operated direct-to-consumer (DTC) services (e.g., Peacock, Paramount+) and new streaming offerings from traditional providers. FuboTV’s scale advantage post-merger brings negotiating leverage for content and potential operating efficiencies, but also exposes it to the full force of industry rivalry.
The company’s proprietary technology platform—featuring innovations like Multiview for simultaneous streaming—offers some product differentiation, especially for sports fans. Yet, switching costs for consumers remain low, and the proliferation of bundled and unbundled streaming options has eroded the pricing power of all but the largest content aggregators. FuboTV’s partnership with Disney for distribution and ad sales is a competitive asset, but may not be enough to fend off aggressive pricing, content bidding wars, and changing consumer viewing habits. The market’s ongoing transition from linear to streaming means that scale and user engagement are necessary but not sufficient for durable advantage.
How Integration Success and Advertising Growth Could Transform FuboTV’s Economics
The bull case for FuboTV hinges on its ability to realize operational synergies from the Hulu Live merger, achieve efficient subscriber acquisition and retention, and grow high-margin advertising revenue. If the company can leverage its enlarged user base and proprietary data to increase ARPU—through premium add-ons, targeted ads, and upselling—while controlling content and operating costs, the path to sustainable profitability becomes plausible.
Confirmation of this scenario would require evidence of improving operating margins, declining net losses (or a shift to positive net income), and robust advertising growth outpacing content cost inflation. Additionally, successful integration milestones—such as platform unification, churn reduction, and cross-selling between Fubo and Hulu Live subscribers—would signal that the company is capturing the intended benefits of the combination. Signs of increased pricing power or reduced content acquisition costs through scale would further support the upside thesis.
What a Realistic Near-Term Outcome Looks Like for FuboTV
The most plausible trajectory for FuboTV over the next 12–24 months is continued top-line growth driven by the expanded subscriber base and modest ARPU gains, offset by ongoing operating losses as integration costs, content expenses, and debt servicing remain high. Advertising revenue may grow, but not fast enough to fully offset content inflation and integration expenditures. The wholesale revenue from Hulu Live will provide stability but limited incremental margin, keeping overall profitability elusive in the near term.
Evidence for this scenario would include sequential revenue growth with persistent but narrowing losses, integration updates indicating gradual progress but also ongoing challenges, and stable or slightly improving ARPU. If margin improvement is modest and debt levels remain high, the company may need to pursue additional capital or refinancing to sustain growth and investment.
Where the Model Breaks: Integration Drag, Debt Stress, or Market Share Loss
The bear case emerges if FuboTV struggles with post-merger integration—operational disruptions, cultural clashes, or failed technology harmonization could erode subscriber experience, drive up costs, and accelerate churn. If advertising revenue fails to scale or macroeconomic conditions weaken ad demand, the company’s losses could deepen. Content cost inflation or intensified competition could further compress margins, especially if FuboTV lacks pricing power to pass on higher expenses.
Inability to refinance or raise new capital on favorable terms would heighten solvency risk. Confirmation of this downside scenario would include widening operating losses, negative free cash flow, missed integration milestones, elevated churn, or adverse credit events.
Milestones and Metrics That Will Reveal FuboTV’s True Trajectory
Net subscriber additions and churn rates for both Fubo and Hulu Live segments, if disclosed, will indicate whether the combined platform is achieving retention and acquisition targets.
Advertising revenue growth and ARPU (average revenue per user) progression are critical for assessing the company’s ability to monetize its expanded user base.
Updates on integration milestones—including platform unification, operational cost savings, or cross-branding initiatives—will reveal synergy realization.
Content cost as a percentage of revenue and trends in carriage fee expenses will spotlight the pressure on gross margins.
Debt servicing metrics, such as interest expense and refinancing activity, will provide early signals of financial stress or flexibility.
Operating cash flow and free cash flow trends will help gauge whether the business is moving toward self-sustaining economics.
Evidence of successful premium add-on attachment rates or upselling to higher-tier plans would suggest effective monetization.
Any changes in the terms or economics of the Disney wholesale agreement or advertising partnership could materially alter the margin profile.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments