
Etoiles Capital Group: Rapid Growth, Governance Trade-Offs, and the Realities of Investor Relations in Volatile Markets
Etoiles Capital Group has scaled its investor relations business rapidly in Hong Kong, but recent quarterly losses and project-based revenue highlight the challenge of sustaining momentum.
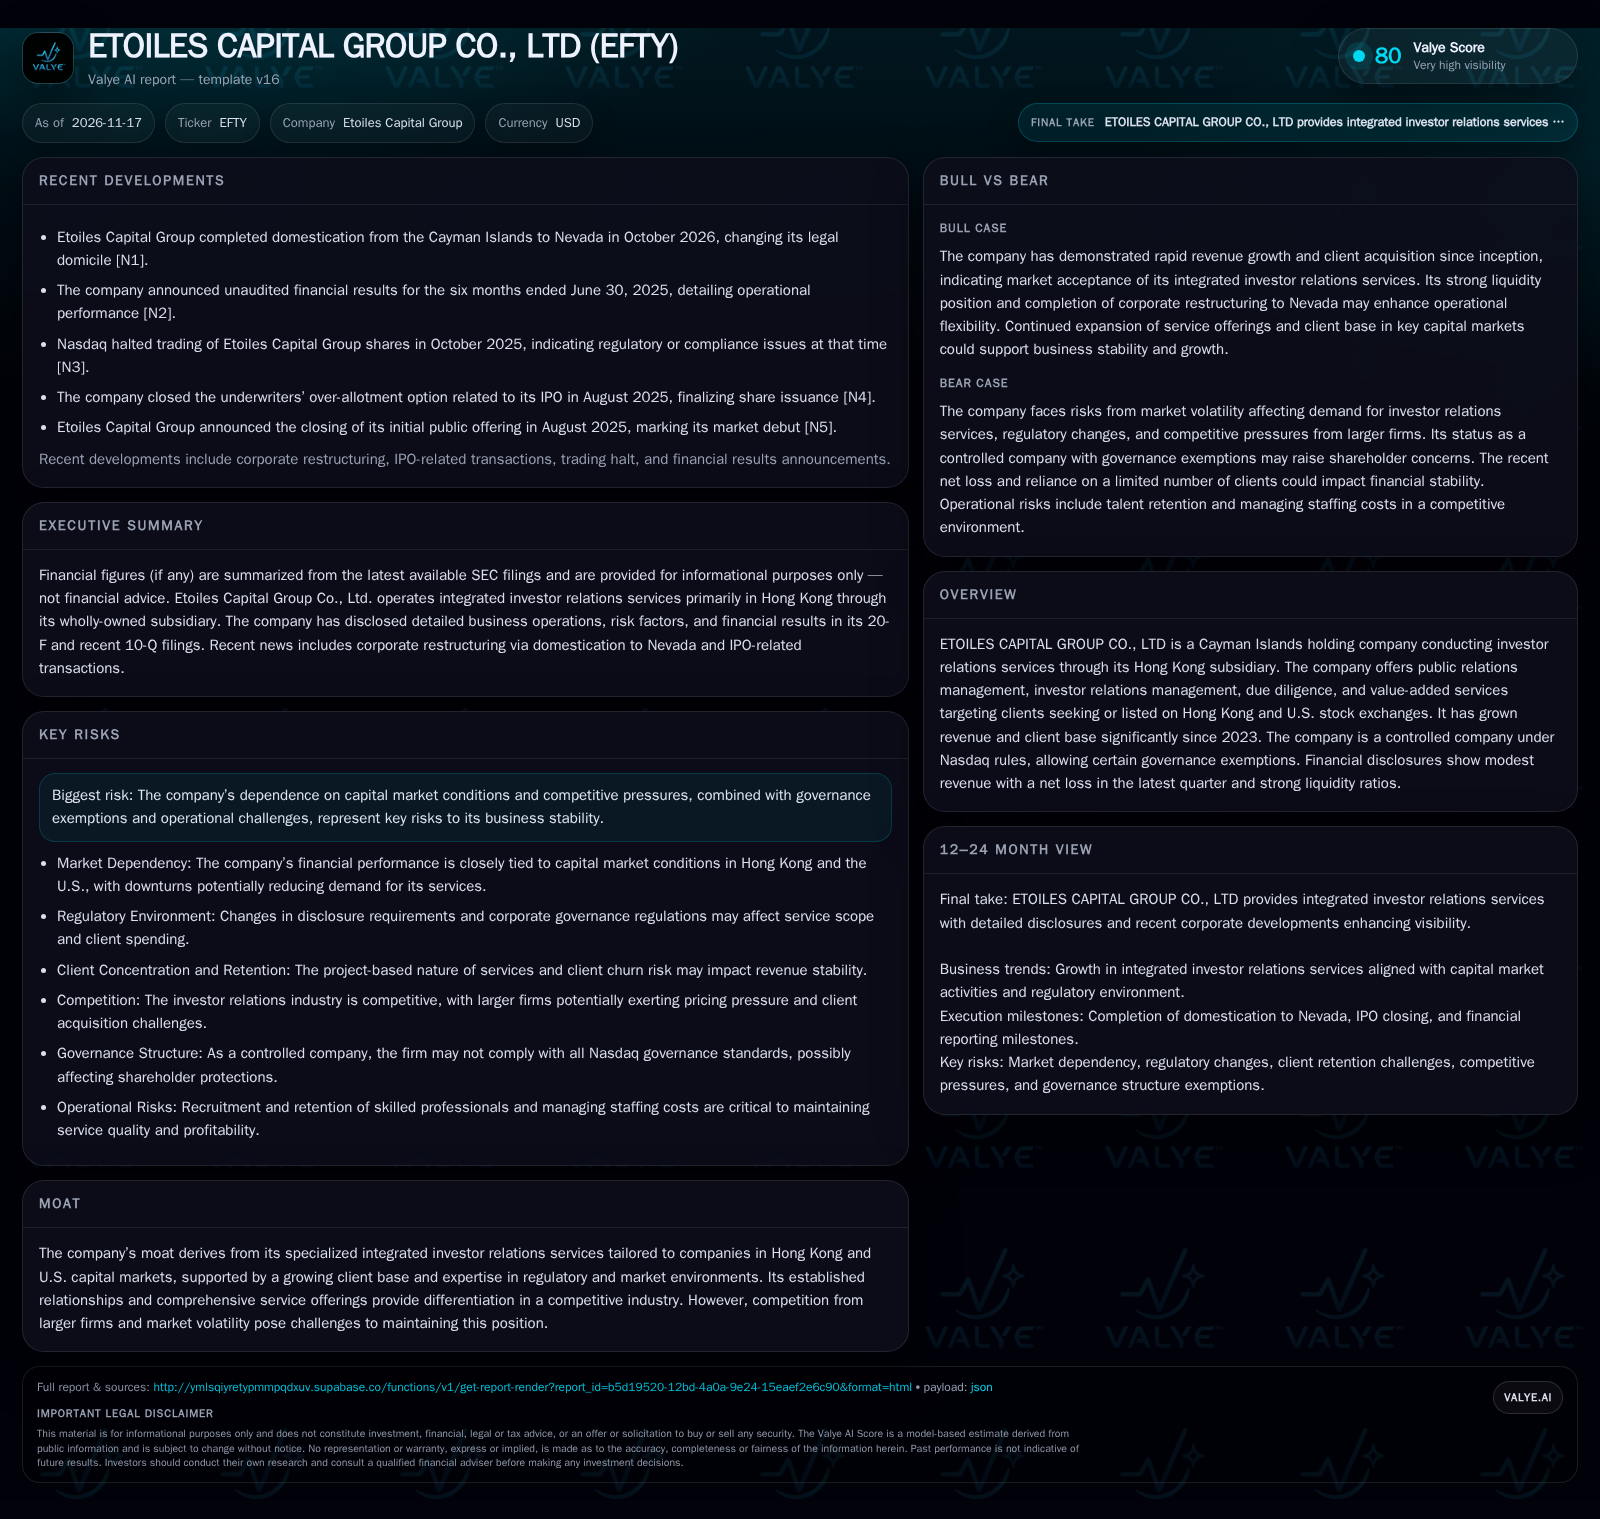
Its status as a controlled company under Nasdaq rules grants governance exemptions but may heighten shareholder risk. The business remains exposed to shifts in capital market activity, competitive pricing, and client churn, making future revenue stability and margin expansion contingent on execution and external conditions. [S2]
Etoiles Capital Group’s trajectory since 2023 demonstrates a rapid transition from a single-client consultancy to a multi-million-dollar investor relations service provider operating in Hong Kong’s dynamic capital markets. The company’s ability to scale revenues and client relationships has been notable, but its most recent quarterly loss underscores the fragility of project-based consulting models—especially in sectors tied closely to market sentiment and deal flow.
Recent Financials Highlight Growth and Exposure to Losses
Etoiles Capital Group reported revenues of $849,494 and a net loss of $134,766 for the quarter ended September 30, 2026, with basic and diluted EPS of -$0.0085. This marks a shift from prior rapid growth—revenues increased from $0.1 million in 2023 to $2.5 million in 2024 and $3.2 million in 2025, while client count rose from 1 in 2023 to 22 in 2024 and 18 in 2025. As of September 30, 2026, the company maintained cash and equivalents of $3.85 million, current assets of $5.87 million, and current liabilities of $1.52 million, resulting in a current ratio of 3.86 and a cash ratio of 2.53. [S2]
The company completed a legal domestication from the Cayman Islands to Nevada in October 2026, following its IPO and related over-allotment closing in August 2025. These moves may increase operational flexibility and transparency, but the immediate operating performance reflects the inherent volatility of project-based consulting tied to capital markets. [N1] [N4] [N5]
How Etoiles Generates Revenue and the Economics of Project-Based Consulting
Etoiles Capital Group’s revenue is primarily derived from integrated investor relations services: public relations management, investor engagement, tailored due diligence, and value-added offerings such as website design and promotional video production. These services are typically contracted on a project or retainer basis, with clients consisting of companies seeking or maintaining listings on Hong Kong and U.S. exchanges, as well as financial industry firms. Pricing is often bespoke, reflecting the complexity and duration of client mandates.
The economics of this business model are characterized by high sensitivity to volume (number and size of client mandates) and mix (degree of value-added services or multi-service contracts). Fixed costs are relatively low, as most expenses are staffing and professional services, leading to a largely variable cost base. However, recruitment and retention of skilled professionals is a key operational cost that can pressure margins, especially in tight labor markets or periods of client churn.
Operating leverage is limited unless the firm can increase average revenue per client or secure longer-term, recurring mandates. The need for ongoing investment in talent and technology to differentiate service offerings may require periodic capital outlays, but with a cash-rich balance sheet, Etoiles is currently positioned to absorb moderate investment or short-term losses. Absent a shift toward more recurring revenue, however, the business will remain exposed to fluctuations in capital markets and client demand. [S2]
Navigating a Crowded Field: Differentiation and Competitive Pressures
Etoiles operates in a highly competitive investor relations landscape, facing both large global consultancies and specialized boutique firms. Its integrated service offering—spanning PR, IR, due diligence, and digital media—may provide a degree of differentiation, particularly for smaller or cross-listed companies seeking one-stop solutions. However, larger competitors may possess greater resources, established client relationships, and the ability to offer bundled services at lower prices.
Switching costs for clients are generally low, as investor relations and PR mandates are often project-based and not contractually recurring. Retention depends on service quality, perceived value, and the personal relationships of key professionals. The company’s recent client growth suggests market acceptance, but the slight decline in client count from 22 in 2024 to 18 in 2025 could signal intensifying competition or churn.
Potential substitutes include in-house IR/PR teams, automated communication platforms, and larger agencies with broader geographic reach or regulatory expertise. The ability to maintain a differentiated, high-touch service—especially in handling crisis communications, complex due diligence, or multi-jurisdictional listings—will be critical to sustaining margins and defending market share. [S2]
What Could Drive Sustained Growth and Margin Expansion
A favorable scenario for Etoiles Capital Group would involve a sustained rebound in Hong Kong and U.S. capital markets, driving increased IPO, listing, and corporate activity. This would translate into more mandates for investor relations, public relations, and due diligence support, enabling the company to grow its client base and potentially secure more multi-year or retainer contracts, thereby smoothing revenue volatility.
Margin expansion could result from leveraging its existing service platform—cross-selling value-added digital offerings, increasing average revenue per client, and achieving economies of scale in project delivery. Successful recruitment and retention of high-caliber professionals would underpin service quality and help win larger, more complex mandates. If the company can transition even a portion of its revenue mix to recurring contracts or develop proprietary digital tools that embed it deeper with clients, operating leverage would improve.
Confirmation of this scenario would come from consecutive quarters of revenue growth, rising average client spend, improved gross and operating margins, and evidence of longer client tenures or contract renewals. A successful expansion into additional geographies or regulatory environments would further support the thesis.
Steady-State: Managing Through Cycles with Project-Based Volatility
The most plausible medium-term outcome is that Etoiles continues to operate as a niche player in Hong Kong’s investor relations market, experiencing lumpy revenue tied to capital market cycles and project wins. The business remains profitable in strong market years but is vulnerable to periods of lower IPO or corporate activity, with profitability fluctuating as staffing and operational costs are adjusted to demand.
Client churn and project-based mandates remain features of the model, putting pressure on management to continually win new business and retain talent.
This scenario would be confirmed by continued variability in quarterly revenues and margins, stable but not accelerating client counts, and limited evidence of multi-year or retainer contracts. Any sustained improvement in operating leverage or margin profile would likely require a strategic pivot or new service innovation.
Vulnerabilities Exposed: What Could Drive Prolonged Losses or Erosion
A negative scenario could unfold if Hong Kong and U.S. capital market activity weakens, reducing demand for investor relations and related consulting. This would result in lower new client wins, reduced project size, and increased competitive pricing pressure, particularly from larger firms willing to discount for market share.
Operationally, the company may face rising staffing costs or difficulty retaining key professionals, eroding service quality and client satisfaction. Governance concerns—stemming from its controlled company status and Nasdaq exemptions—could deter institutional clients or investors, compounding reputational and commercial risks.
Confirmation would come from consecutive quarters of declining revenue, persistent net losses, shrinking client base, and deteriorating gross or operating margins. An inability to replace lost clients or adapt the service model to new market realities would accelerate downside risks.
Benchmarks for Testing Etoiles Capital Group’s Resilience and Trajectory
Quarterly client count and client retention rates, if disclosed, to assess whether the company can maintain or grow its customer base amid competitive pressures.
Revenue mix between project-based and any recurring (retainer or multi-year) contracts, which would indicate progress toward revenue stability.
Average revenue per client and average contract size, as rising figures here would suggest success in upselling services or winning larger mandates.
Gross and operating margin trends, especially in relation to staffing costs, to test for improving efficiency or margin compression.
Disclosure of new service offerings, digital tools, or geographic expansion, which could signal innovation and differentiation.
Material shifts in capital market activity in Hong Kong or the U.S., as these external factors have a direct impact on demand for investor relations services.
Any changes to governance structure or shareholder rights, particularly regarding the controlled company status and Nasdaq exemptions.
Evidence of major client wins, renewals, or losses, as these events can be leading indicators of future revenue and reputation.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments