
8x8’s AI-Driven Platform Ambitions Meet a Refinancing Reality Check
8x8’s unified communications and customer experience platform is seeing traction in multi-product adoption and platform usage growth, but margin pressure and imminent debt maturities create a high-stakes test of its ability to convert innovation into sustainable financial health.
8x8’s AI-powered platform is demonstrating increased usage and multi-product adoption, particularly through communication APIs and integrations with enterprise ecosystems. However, sequential margin compression and $297 million in debt coming due within 18 months put the company’s refinancing ability and operational resilience in sharp focus.
8x8 is at a critical inflection point where the promise of its integrated, AI-powered communications platform is running headlong into the reality of margin compression and a looming wall of debt. While the company’s platform migration and API-driven growth have enabled multi-product adoption and operational efficiencies, its declining gross margins and constrained liquidity raise existential questions about sustainability. The next 12 to 18 months will be defined as much by 8x8’s ability to refinance and manage its capital structure as by its capacity to execute on innovation and customer retention.
Margin Compression and Debt Deadlines Dominate the Near-Term Outlook
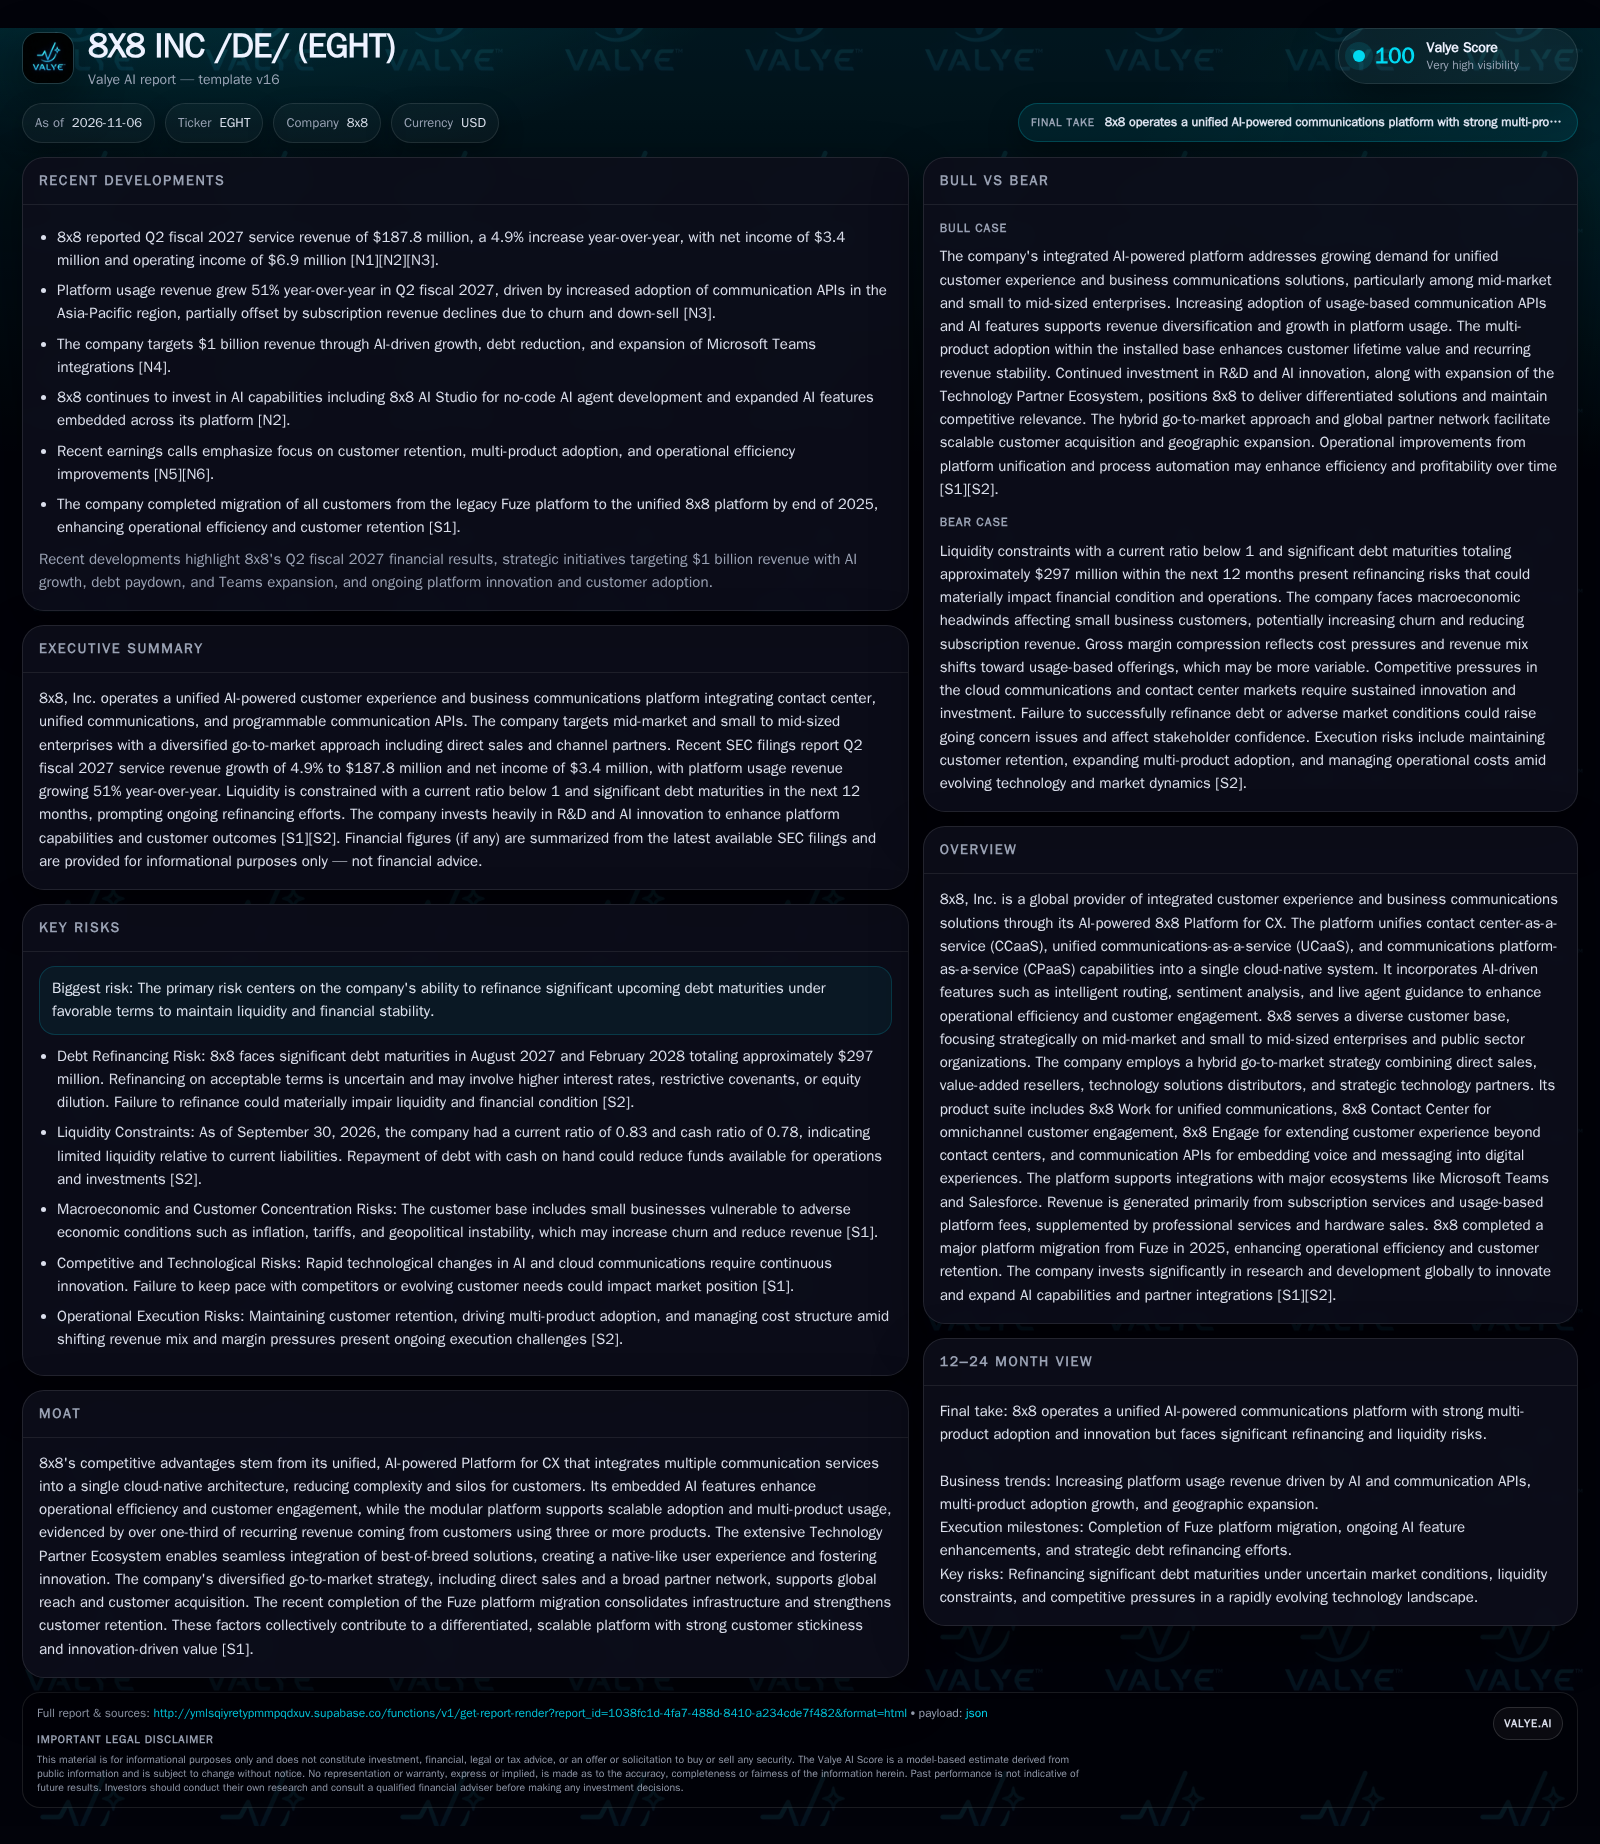
8x8 reported a 4.9% year-over-year increase in service revenue for Q2 fiscal 2027, reaching $187.8 million, and achieved net income of $3.4 million. However, gross margin dropped to 59.7% from 64.8% in the prior year, reflecting an unfavorable shift in revenue mix—specifically, increased reliance on lower-margin platform usage revenue and cost structure changes.[S2] Platform usage revenue grew 51% year-over-year, powered by adoption of communication APIs in Asia-Pacific, but this was offset by declines in higher-margin subscription revenue due to churn and down-sell.[S2]
The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2] Management has noted that failure to refinance could materially affect liquidity and raise going concern issues.[S2]
Operationally, the full migration from the legacy Fuze platform was completed by December 2025, streamlining operations and supporting improved customer retention, with over one-third of recurring revenue now coming from customers using three or more 8x8 products.[S1]
How 8x8’s Revenue Mix and Cost Structure Shape Economic Outcomes
8x8’s core revenue streams include recurring subscription service revenue from UCaaS and CCaaS, usage-based platform revenue (notably from communication APIs and AI interactions), and ancillary revenue from professional services and hardware sales.[S1] The mix between high-margin subscription revenue and lower-margin usage revenue is a critical driver of gross margin and profitability. Recent results suggest that while platform usage growth is robust, it is not yet enough to compensate for churn and down-sell in subscription services—leading to margin compression.[S2]
The company’s business model relies on scaling software and platform services; fixed costs (notably R&D and platform operations) are high, but marginal costs for digital services are relatively low, offering operating leverage if recurring revenue growth outpaces churn and discounting. However, the need for continued R&D investment to keep pace with rapid AI and platform innovation, coupled with the cost of maintaining a global partner and integration ecosystem, puts pressure on near-term margins.
Capital needs are acute due to the debt maturity schedule: with $297 million due within 18 months and a cash balance of just over $100 million, 8x8 must secure refinancing or alternative capital. This restricts its ability to invest aggressively in growth or weather further margin compression without external support.[S2]
Integration, Ecosystem, and AI: Where 8x8 Can Stand Out—and Where It’s Vulnerable
8x8’s platform strategy—integrating CCaaS, UCaaS, and CPaaS with embedded AI—addresses a growing market demand for unified customer engagement solutions, especially among mid-market and public sector customers. The ability to offer seamless integration with Microsoft Teams, Salesforce, and other major ecosystems is a source of differentiation, as is the focus on no-code AI agent development and journey optimization.[S1]
However, 8x8 operates in a fiercely competitive landscape. Larger, better-capitalized vendors and pure-play cloud communication providers have the resources to drive product innovation, pricing pressure, and aggressive customer acquisition. The risk is that 8x8’s innovation cadence and ecosystem breadth may not be enough to offset scale disadvantages or counteract churn if competitors match or surpass its AI capabilities.
Customer switching costs are moderate: while integration and multi-product adoption create some stickiness, enterprise customers are typically sophisticated buyers who can evaluate and migrate to alternative platforms if service, innovation, or pricing lags. The challenge for 8x8 is to convert its technical integration and AI lead into tangible, defensible economic advantages before liquidity constraints force tough trade-offs.
A Virtuous Cycle: If API Adoption and Multi-Product Expansion Accelerate
The favorable scenario for 8x8 is one in which accelerated adoption of communication APIs, AI-driven features, and integrated platform solutions drives both higher platform usage revenue and improved cross-sell into existing accounts. If the company can sustain or expand multi-product adoption—already representing over one-third of recurring revenue—churn could decline, average revenue per customer could rise, and operational leverage could improve as fixed costs are spread over a larger revenue base.[S1]
Confirmation of this scenario would include: continued double-digit growth in platform/API usage revenue; stabilization or improvement in gross margin as revenue mix shifts back toward higher-value subscriptions; successful debt refinancing with minimal equity dilution or onerous covenants; and evidence of declining churn and rising net dollar retention. Falsification would be signaled by persistent margin erosion, failure to refinance debt, or continued net subscription losses.
Stability Hinges on Execution: Managing Debt and Margin Pressures While Growing Platform Usage
The most plausible outcome is that 8x8 manages to refinance its near-term debt, albeit at higher cost or with some dilution, and continues to grow platform usage revenue while facing ongoing pressure on subscription revenue and gross margins. Multi-product adoption likely stabilizes churn in core segments, but overall revenue growth remains modest as competitive pricing and customer retention challenges persist.
Margins may remain below historical norms due to the higher proportion of lower-margin usage revenue and the need for sustained investment in R&D and partner integrations. Operational efficiency gains from the Fuze migration and automation initiatives could partially offset these pressures, but significant margin expansion is unlikely without a return to higher subscription growth.
Evidence supporting this scenario would include successful, if costly, refinancing; steady (but not accelerating) growth in platform usage; and stabilization of gross margins. Negative signals would include failed or highly dilutive refinancing, renewed churn spikes, or further margin compression.
Liquidity Crunch: What Happens if Refinancing Falters and Churn Persists
The adverse scenario centers on the risk that 8x8 fails to refinance its $297 million in maturing debt on acceptable terms, triggering a liquidity crunch that forces drastic cost-cutting, asset sales, or even restructuring.[S2] In this situation, margin pressure is likely to worsen as the company is forced to prioritize near-term cash generation over long-term investment, potentially leading to underinvestment in R&D, weakening its competitive position.
Churn could accelerate if customer service or platform innovation suffers, driving further subscription revenue declines and eroding the base needed for cross-sell and usage expansion. The company’s ability to retain partners and key integrations could also be impaired if financial instability undermines confidence.
Signals confirming this scenario would include failure to secure refinancing, material going concern disclosures, rapid headcount or R&D cuts, and a spike in customer cancellations. Falsification would require clear evidence of successful refinancing and stabilization of operational metrics.
Milestones and Metrics That Will Reveal 8x8’s Path Forward
Progress and announced terms on the refinancing of $297 million in debt due August 2027 and February 2028.
Quarterly gross margin trends to determine if margin erosion can be arrested or reversed, especially in light of revenue mix shifts.
Churn rates and net dollar retention, particularly among customers using three or more products, if disclosed.
Growth rates in platform usage revenue (notably API and AI-driven interactions), with attention to geographic and segment breakdowns.
Subscription revenue stabilization or further declines—watch for signals of success or failure in cross-sell and retention initiatives.
R&D and product development spending levels, as a proxy for the company’s ability to sustain innovation under financial constraints.
Updates on major partnerships, integrations (e.g., with Microsoft Teams and Salesforce), and ecosystem expansion.
Material changes in headcount, customer support responsiveness, or partner engagement, which could indicate operational stress or investment cutbacks.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments