
Evolus: Cash-Pay Aesthetics, Competitive Pressures, and the Realities of Scaling in a Crowded Market
Evolus, Inc. is navigating the high-stakes medical aesthetics field with a portfolio focused on neurotoxin and injectable filler products. While recent revenue growth and market recognition suggest commercial traction, the company’s persistent losses, reliance on discretionary spending, and exposure to regulatory and supply chain risks highlight the delicate balance between growth ambitions and operational sustainability.
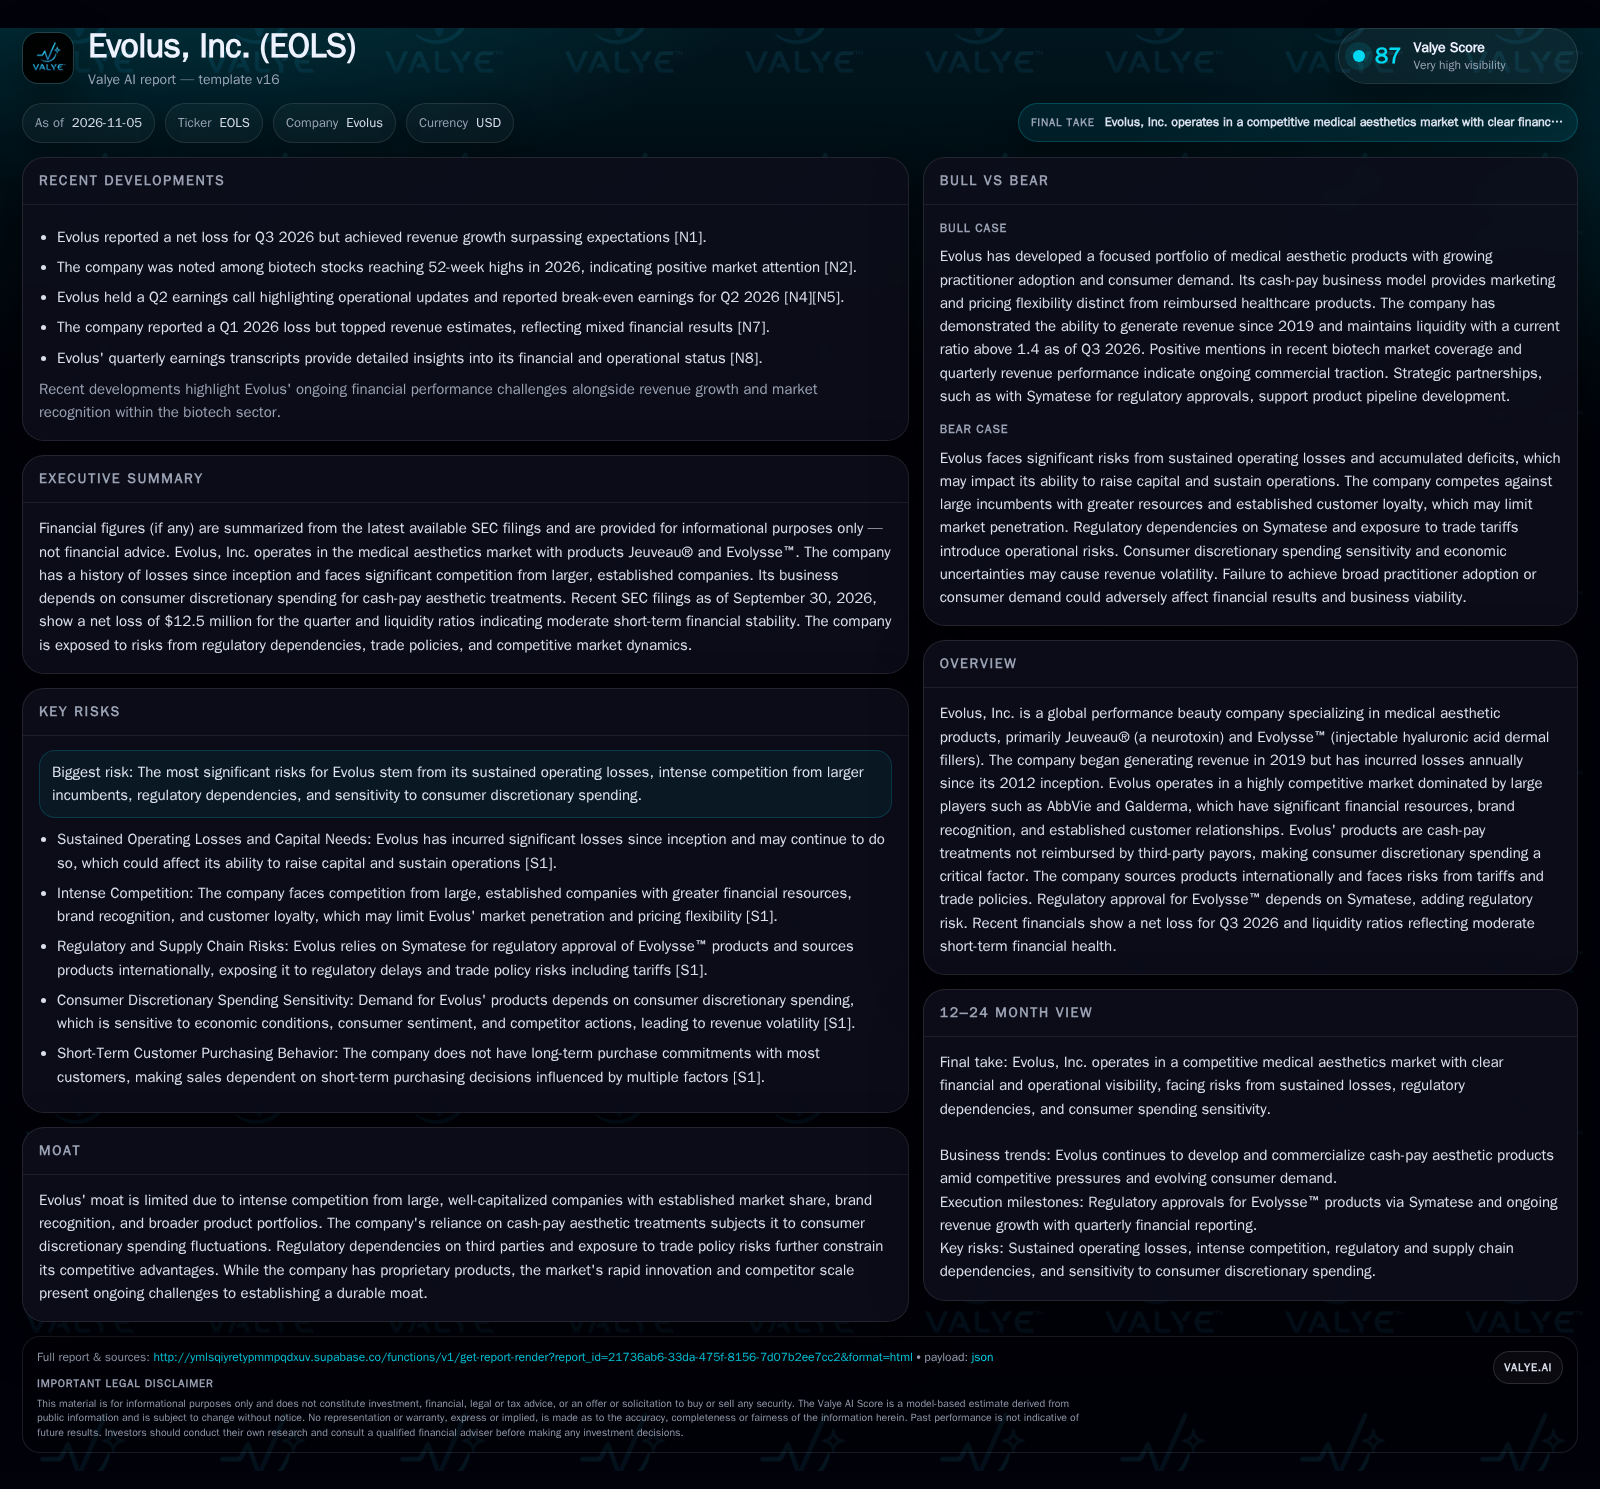
Evolus, Inc. reported a Q3 2026 net loss of $12.5 million despite revenue growth outpacing expectations, earning a spot among biotech stocks hitting 52-week highs. Its business depends on consumer spending for cash-pay aesthetic treatments, faces intense competition from larger incumbents, and is exposed to regulatory and supply chain risks—including dependencies on Symatese for product approvals. The company’s moderate short-term liquidity provides some operational leeway, but ongoing losses and market dynamics remain critical pressure points. [N1] [N2] [S2]
Evolus, Inc. is at a pivotal point in its evolution within the medical aesthetics landscape. The company’s Q3 2026 results illustrate both progress and persistent fragility: while revenue growth has attracted positive market attention, continued operating losses, reliance on cash-pay consumer demand, and dependence on external partners for regulatory approval underscore the business’s inherent risks. As Evolus seeks to carve out a durable niche against well-capitalized incumbents, its ability to convert commercial momentum into sustainable profitability will be tested by economic cycles, regulatory hurdles, and the unforgiving dynamics of a crowded market.
Recent Financial Performance and Operational Milestones: What’s Changed for Evolus?
Evolus reported a net loss of $12.5 million for Q3 2026, continuing its track record of operating losses since inception. Despite this, the company achieved revenue growth that surpassed expectations, with recent earnings calls highlighting operational progress and even a break-even quarter in Q2 2026. This combination of top-line momentum and ongoing bottom-line pressure reflects both the promise and the challenge facing the business. Evolus also gained market attention by reaching 52-week highs among biotech stocks in 2026, suggesting increased investor interest and recognition within the sector. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [N1] [N2] [N4] [N5] [S2]
How Evolus Makes—and Could Lose—Money in Cash-Pay Aesthetics
Evolus generates revenue from Jeuveau®, a neurotoxin for wrinkle reduction, and Evolysse™, a hyaluronic acid-based dermal filler. Both products are sold as cash-pay procedures, meaning practitioners and patients pay out of pocket rather than relying on insurance reimbursement. This model offers pricing flexibility and avoids the administrative burden of third-party payors, but it also exposes demand to fluctuations in consumer discretionary spending and economic sentiment.
The company’s cost base includes international sourcing, regulatory expenses (especially for Evolysse™ approval via Symatese), marketing, and commercial infrastructure to build practitioner adoption. Fixed costs in R&D and regulatory affairs are significant, while variable costs scale with product volume. Operating leverage could be realized if top-line growth outpaces fixed cost increases, but persistent losses suggest that current volumes and pricing have not yet reached the level needed to cover overhead and generate positive cash flow.
Capital needs remain material, given the history of losses and ongoing investment in product development and commercialization. Without long-term purchase commitments from customers, revenue visibility is limited, making cash flow planning more challenging in the face of economic headwinds or competitive responses.
Competitive Dynamics: Fighting for Share Against Market Giants
Evolus operates in a market dominated by established players like AbbVie and Galderma, both of which possess extensive financial resources, entrenched brand loyalty, and well-developed practitioner networks. These incumbents can outspend on marketing, absorb regulatory or supply chain shocks, and bundle broader portfolios to lock in customers. Evolus’ proprietary products offer differentiation but are not immune to rapid innovation cycles or the risk of being outmaneuvered by larger rivals.
Barriers to entry in aesthetics are moderate: while regulatory hurdles and practitioner relationships matter, the absence of reimbursement means switching costs for practitioners may be lower than in other medical verticals. Evolus’ reliance on international sourcing and third-party partners (notably Symatese for regulatory filings) introduces additional vulnerabilities. Competing on price could win share but risks compressing margins in a market where scale matters. Substitution risk exists from emerging minimally invasive and non-injectable treatments, which could shift practitioner and patient preferences over time.
A Path to Profitability: What Would a Breakout Look Like for Evolus?
The most favorable scenario for Evolus involves sustained double-digit revenue growth, driven by successful regulatory approval and commercial launch of Evolysse™ in major markets, alongside continued adoption of Jeuveau®. If the company can deepen practitioner relationships and drive repeat usage, it could achieve operating leverage as fixed costs are spread over a larger revenue base. Robust consumer demand, perhaps buoyed by macroeconomic tailwinds and effective direct-to-consumer marketing, would further support this growth.
Confirmation of this scenario would include consecutive quarters of revenue outperformance, gross margin expansion indicating pricing power or cost efficiencies, and a clear path to consistent profitability. Additional signals would be successful regulatory milestones for new products, expansion into new geographies, and evidence of practitioner loyalty (such as increasing reorder rates or long-term partnerships, if disclosed). Falsification would come from stalled revenue growth, margin contraction, or regulatory setbacks delaying the Evolysse™ pipeline.
Sustaining Momentum Amid Competition and Economic Fluctuations
The most plausible trajectory for Evolus is continued revenue growth at a moderate pace, with periodic volatility tied to consumer sentiment and competitive actions. The company may see sequential improvement in operating results but remain unprofitable as marketing and regulatory costs persist. Evolus’ position as a smaller challenger means it must carefully balance investment in commercial expansion with discipline on costs.
Under this scenario, Evolus maintains enough liquidity to operate but may need to raise additional capital if losses persist or investment ramps up for new product launches. Practitioner adoption grows, but is partially offset by aggressive moves from incumbents (such as price promotions or new product launches). Evidence supporting this path would include steady, if uneven, revenue growth, gradual gross margin improvement, and ongoing regulatory progress. Warning signs would be deteriorating liquidity, rising operating losses, or evidence of market share loss to incumbents.
Where the Model Breaks: Prolonged Losses, Regulatory Delays, and Demand Shocks
A negative scenario could unfold if Evolus faces prolonged regulatory delays for Evolysse™, struggles to gain additional practitioner traction, or encounters a sharp downturn in consumer discretionary spending (for example, in a recessionary environment). Intense competitive pushback from larger players could erode pricing and compress margins, while trade policy shifts or supply chain disruptions might inflate costs or restrict product availability.
Confirmation of this scenario would involve declining or stagnant revenues, widening operating losses, and deteriorating liquidity—potentially forcing the company to seek dilutive financing or scale back operations. Setbacks in regulatory milestones, loss of key practitioner relationships, or negative sentiment in the aesthetics market would further pressure the business. A useful falsification would be the company’s ability to maintain or grow share despite macro or competitive headwinds, or to secure non-dilutive funding that supports ongoing investment.
Testing the Evolus Thesis: Concrete Developments to Track in 2027
Quarterly revenue growth rates and their relationship to practitioner adoption trends (if disclosed) will be essential in assessing whether top-line momentum is sustainable.
Gross margin progression, especially in the context of product mix (Jeuveau® versus Evolysse™) and any pricing actions or cost efficiencies, would help test the potential for operating leverage.
Updates on the regulatory approval timeline and outcomes for Evolysse™, including any disclosed milestones with Symatese, are critical for pipeline visibility.
Practitioner reorder rates or customer retention metrics, if disclosed, would provide insight into the stickiness of Evolus’ practitioner base.
Competitive responses, including new product launches, price changes, or marketing campaigns from major incumbents, may impact Evolus’ market share trajectory.
Changes in macroeconomic indicators or consumer discretionary spending trends could materially affect the demand environment for cash-pay aesthetic treatments.
Progress on international expansion or entry into new markets, if announced, would signal management’s ability to diversify and scale the business.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments