
Red Violet’s Expanding Identity Intelligence Platform: Durable Growth, Competitive Frictions, and the Stakes of Scale
Red Violet’s AI-powered CORE™ platform continues to add customers and users across its IDI and FOREWARN brands, driving robust revenue and margin expansion. With a recent capital raise and a focus on recurring, auto-renewing contracts, the company is positioned to scale—but must navigate intensifying competition, regulatory uncertainties, and the operational demands of broadening its platform.
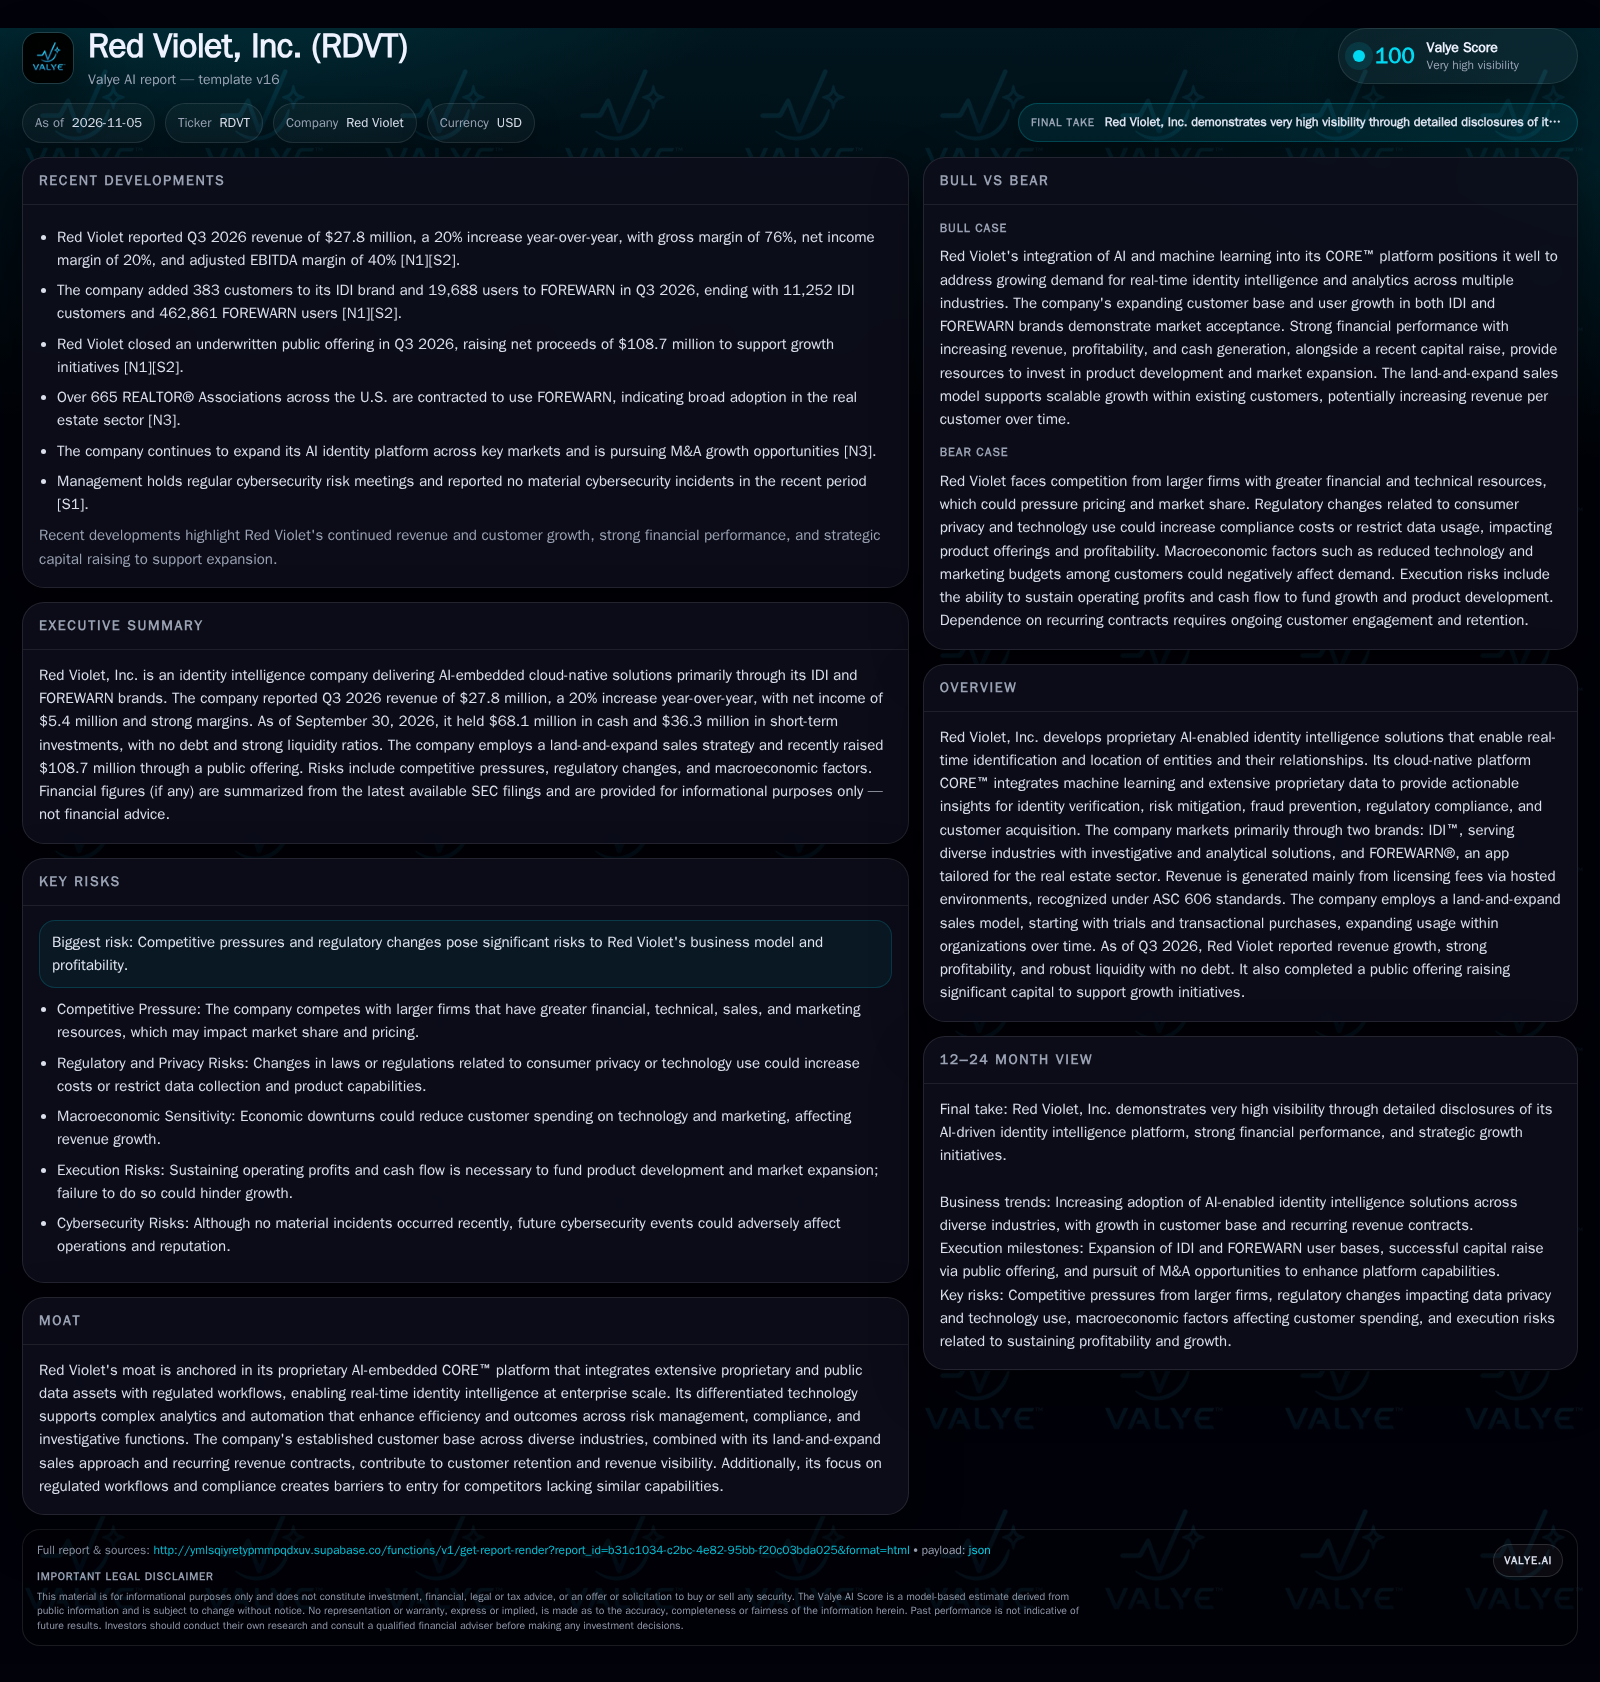
Red Violet posted 20% year-over-year revenue growth for Q3 2026, driven by rising adoption of its AI-embedded identity intelligence solutions across diverse sectors. The company’s strong margins and $108.7 million capital raise support continued investment in platform expansion and M&A. However, competition from larger players, regulatory risk, and the challenge of sustaining customer engagement remain critical factors for future performance. [S2] [N1] [N3]
Red Violet, Inc. is capitalizing on the rising demand for real-time, AI-driven identity intelligence across a spectrum of industries. Its cloud-native CORE™ platform, marketed through the IDI and FOREWARN brands, has delivered robust customer and user growth, translating into significant revenue and margin expansion in 2026. With a recently fortified balance sheet and a business model emphasizing recurring revenue, Red Violet is positioned for further scale. The key question is whether its technology edge, sales execution, and capital will be sufficient to fend off larger competitors and adapt to evolving regulatory and market dynamics.
Recent Performance Underscores Platform Momentum and Financial Strength
For Q3 2026, Red Violet reported $27.8 million in revenue—a 20% increase from the prior year—alongside a 76% gross margin, 20% net income margin, and 40% adjusted EBITDA margin [S2]. These results reflect continued adoption of its CORE™ platform, which leverages AI and proprietary data for identity verification, fraud prevention, and compliance across sectors. As of September 30, 2026, the IDI brand had 11,252 billable customers (up 383 in the quarter) and FOREWARN had 462,861 users (up 19,688) [S2].
Red Violet’s liquidity is notable: $68.1 million in cash, $36.3 million in short-term investments, and total liquidity of $165.7 million (including U.S. Treasury securities), with no debt and a current ratio of 16.21 [S2]. The company completed an underwritten public offering in Q3, raising $108.7 million to support growth initiatives [S2] [N1].
The company’s revenue is substantially generated from licensing fees, recognized based on usage or monthly/annual contracts, most of which are annual or longer with auto-renewal features—providing a foundation for recurring revenue [S1] [S2].
Recurring Revenue, High Margins, and the Leverage of Data-Driven Scale
Red Violet’s business model centers on licensing access to its AI-powered identity intelligence platform via hosted environments—through online interfaces, APIs, and custom integrations. The company’s revenue mix is shaped by a blend of transactional (per-use) and subscription-like (monthly, annual, or longer-term with auto-renewal) contracts [S1] [S2]. This model creates a recurring revenue base, supports revenue visibility, and reduces cyclicality compared to pure transactional models.
Operating leverage is evident: gross margins at 76% suggest significant economies of scale in data processing and platform delivery, while a 40% adjusted EBITDA margin reflects disciplined cost structure and the scalability of cloud-native software economics [S2]. As customer usage grows (via the land-and-expand approach), incremental revenue may carry high contribution margins once the fixed costs of data acquisition, platform development, and compliance are covered.
Capital intensity appears low for core operations, with substantial cash and no debt. The recent capital raise ($108.7 million) provides optionality for investment in platform enhancements, customer acquisition, or M&A [S2]. However, future capital needs could rise if regulatory or data acquisition costs escalate, or if competition requires stepped-up investment in product and sales.
Competitive Landscape: Proprietary Tech, Customer Entrenchment—But Larger Rivals Loom
Red Violet’s competitive position is anchored by its proprietary AI-embedded CORE™ platform, which integrates regulated workflows and extensive data assets to deliver actionable insights for identity verification, risk management, and compliance [S1]. The breadth of its data, the integration of AI/ML, and vertical-specific solutions (e.g., FOREWARN in real estate) may create switching frictions for established customers—especially as workflows become embedded in client operations.
However, the company faces formidable competition from larger identity, analytics, and information services players with deeper resources and broader sales reach. Such competitors may offer bundled solutions, undercut pricing, or invest aggressively in R&D and compliance, challenging Red Violet’s ability to sustain differentiation and pricing power. Regulatory scrutiny of data privacy and usage is also a potential equalizer, as compliance costs and barriers rise across the industry.
Customer acquisition and retention hinge on Red Violet’s ability to demonstrate superior insight, reliability, and compliance. The land-and-expand model can drive increasing revenue per customer if product value is proven, but competitors with established relationships or more comprehensive datasets could slow expansion or force price concessions.
Compounding Value Through Expansion and Cross-Sell: What Would Drive a Bullish Outcome
If Red Violet continues to execute on its land-and-expand sales strategy, the company could see accelerating growth in revenue per customer as initial deployments expand across customer departments and geographies. The strong net customer and user additions in Q3 2026, combined with recurring, auto-renewing contracts, suggest a pathway to compounding annualized revenue [S2].
Further upside could come from successful cross-selling between IDI and FOREWARN, deepening integration into client workflows, and leveraging AI-driven analytics to launch new high-value features or verticals. M&A, enabled by the recent capital raise, could add scale, capabilities, or proprietary datasets—expanding the platform’s addressable market [N3].
Confirmation of this scenario would include continued double-digit customer/user growth, rising average revenue per user, successful integration of new acquisitions, and evidence of increasing multiyear contract value or retention rates (if disclosed).
Sustained Growth with Mounting Competitive and Regulatory Pressures
The most plausible medium-term path is for Red Violet to maintain healthy revenue and margin growth—driven by ongoing expansion in its core customer and user bases, incremental product improvements, and disciplined capital deployment. Recurring, auto-renewing contracts provide revenue visibility, while high margins allow continued investment in platform enhancements and compliance.
However, as the market matures, growth rates may moderate due to competitive discounting, increased customer sophistication, and regulatory headwinds that raise operating costs or limit certain data uses. Larger competitors could erode pricing power or win enterprise deals, while customers may demand greater integration or customization, increasing operational complexity.
This scenario would be corroborated by steady, if slightly decelerating, customer and user growth; stable or gradually compressing margins; and ongoing product launches or incremental M&A activity. Warning signs would be a sharp slowdown in net additions, rising churn (if disclosed), or significant increases in compliance or customer acquisition costs.
Margin Compression and Growth Stalls: When Competitive and Regulatory Forces Collide
In a negative scenario, intensified competition from larger incumbents or aggressive new entrants could force Red Violet to reduce pricing or increase investment in product and compliance, compressing margins. Regulatory changes—such as tighter data privacy laws or restrictions on data sharing—could limit the utility of the CORE™ platform, increase compliance costs, or disrupt existing revenue streams.
Additionally, a macroeconomic downturn could prompt customers to cut back on technology and marketing spend, slowing new sales and potentially triggering churn among existing users. If the company fails to expand its product set or demonstrate clear ROI, customers may seek alternative providers or negotiate lower fees.
This scenario would be confirmed by a pronounced deceleration or reversal in revenue/user growth, shrinking gross and EBITDA margins, significant increases in compliance or legal costs, or evidence of lost contracts due to regulatory or competitive pressures.
What Will Prove Red Violet’s Platform Durability and Growth Ambitions?
Sustained net growth in billable IDI customers and FOREWARN users quarter-over-quarter—especially if growth rates remain at or above recent levels.
Average revenue per customer/user (if disclosed), as an indicator of successful cross-sell, upsell, and land-and-expand execution.
Gross and EBITDA margin trends: continued high margins would suggest operating leverage and successful cost management, while compression could signal competitive or regulatory pressure.
Churn or retention rates (if disclosed) across both IDI and FOREWARN, as a direct measure of customer entrenchment and satisfaction.
Regulatory developments affecting data privacy, data access, or AI use in identity intelligence; any material compliance cost increases or product restrictions.
Pace and nature of new product feature launches, vertical expansions, or integrations with customer systems.
Execution and integration of M&A deals: evidence that acquisitions are accretive, add proprietary data or technology, and support platform stickiness.
Customer concentration metrics (if disclosed), to assess exposure to large enterprise contract risk and diversification of revenue sources.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments