
Hackett Group: Navigating Fixed-Fee Complexity, Debt Leverage, and the Stakes of Human Capital in Professional Services
Hackett Group’s recent earnings beats highlight solid execution, but the company’s reliance on fixed-fee contracts, rising debt, and the inherent complexity of revenue recognition put a premium on management discipline and accurate forecasting. The economic model’s sensitivity to project estimation accuracy, coupled with a competitive advisory landscape, frames both the opportunity and the risk for shareholders.
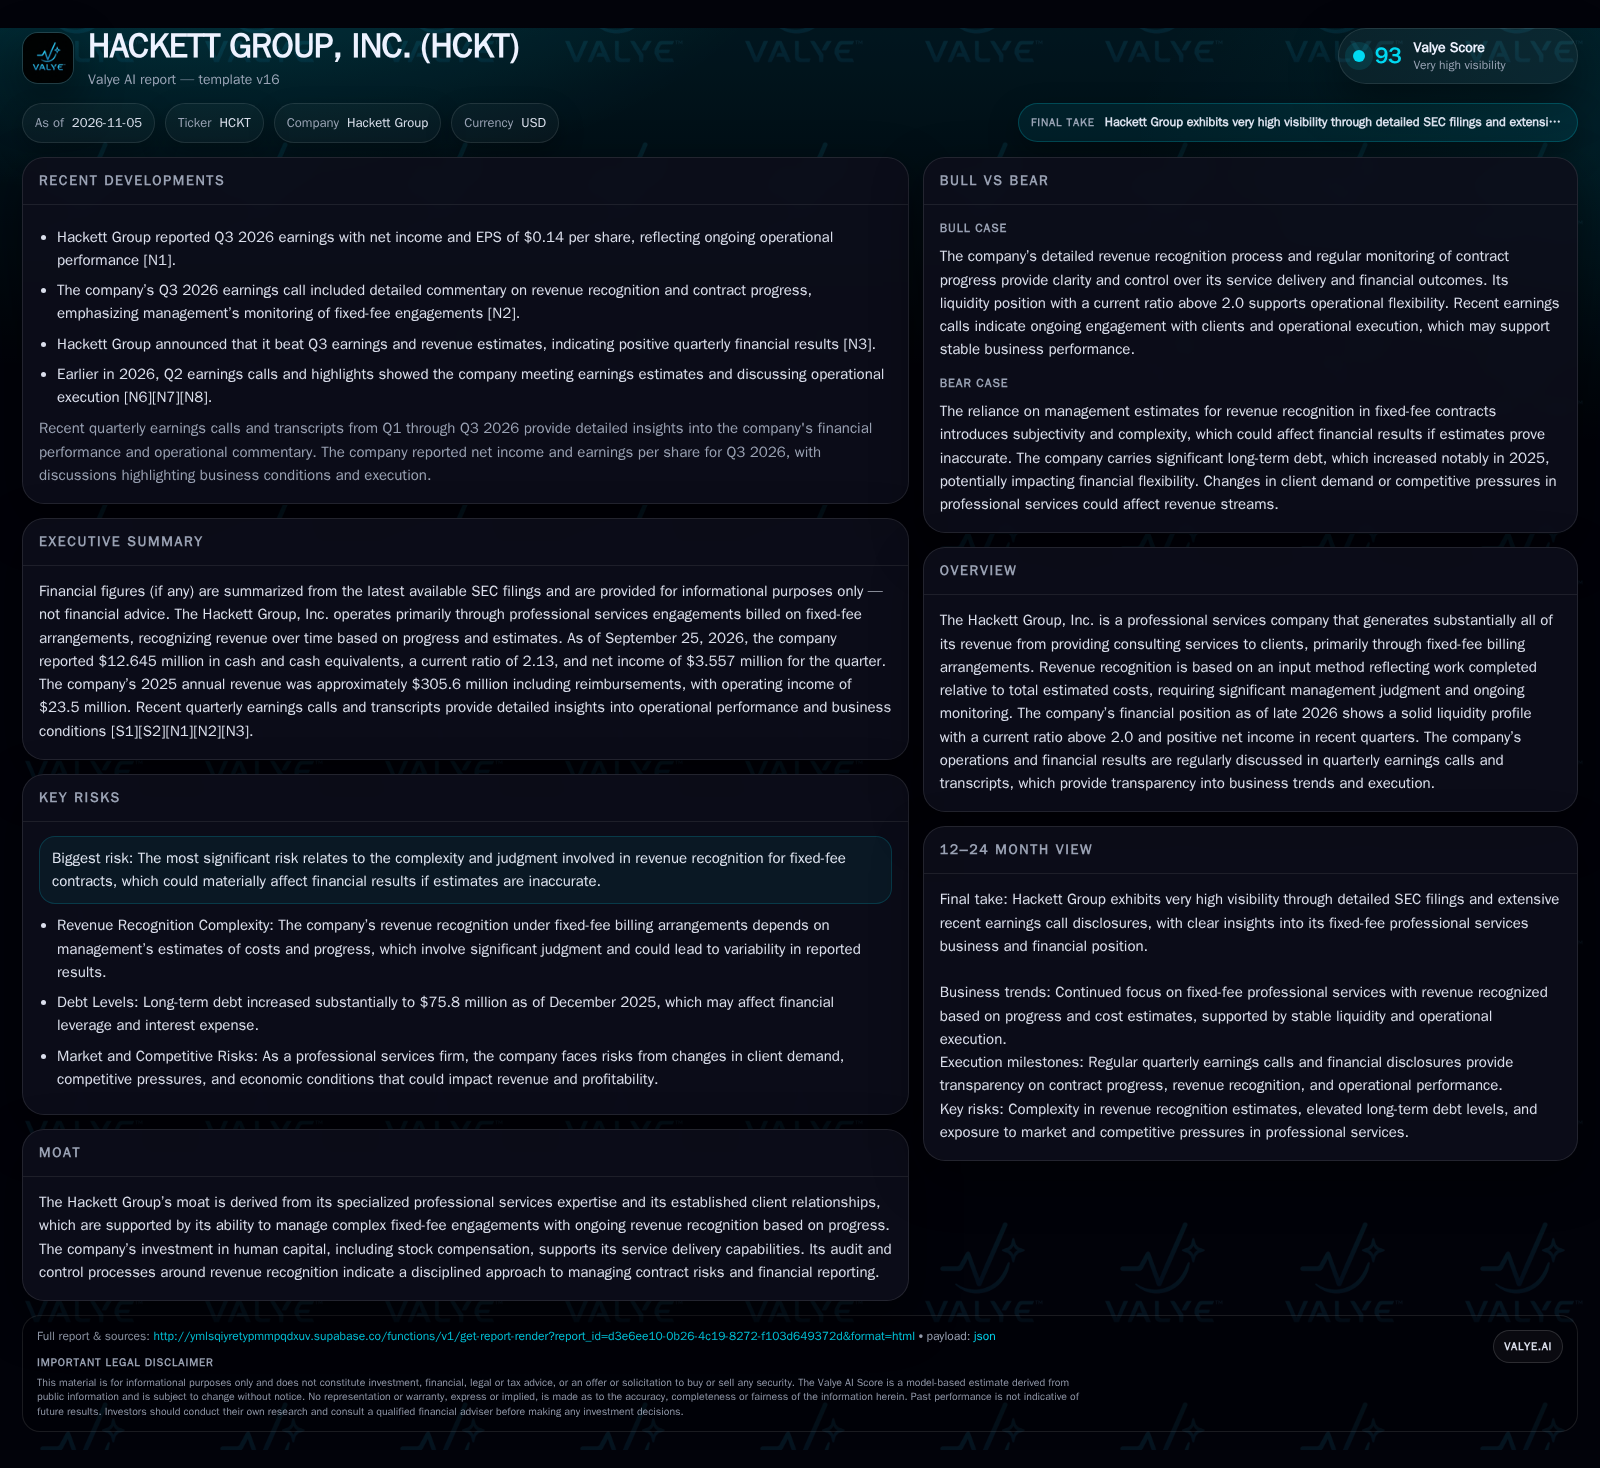
Hackett Group’s Q3 2026 earnings and revenue exceeded expectations, underpinned by a reported current ratio and positive net income. However, the company’s business model—centered on fixed-fee contracts—relies on management’s judgment for revenue recognition, introducing estimation risk. Elevated long-term debt and exposure to competitive pressures in the professional services sector remain material watchpoints for future performance. [S1] [S2] [N3]
Hackett Group’s recent performance showcases the strengths and tensions at the heart of its professional services business: steady earnings, prudent liquidity, and a model built on fixed-fee project delivery. While the company’s above-expectation Q3 results underscore operational discipline, its reliance on managerial estimates for revenue recognition and an increased debt load introduce additional layers of risk. In a sector where talent, estimation accuracy, and client trust are paramount, Hackett’s future depends on its ability to manage these variables more effectively than its peers.
Earnings Momentum and Financial Position: The Latest Snapshot
Hackett Group reported net income of $3.557 million for the quarter ended September 25, 2026, with basic and diluted EPS of $0.14 per share. The company reported liquidity-ratio trends of 2.13, supported by $12.645 million in cash and cash equivalents, and current assets of $90.062 million versus current liabilities of $42.194 million. The company’s long-term debt stood at $75.818 million as of December 2025, a notable increase from prior years. Recent news indicates that Q3 earnings and revenue exceeded consensus estimates, building on a trend of meeting or beating expectations in previous quarters. These facts suggest operational resilience and prudent short-term liquidity, yet the rising debt level and the complexity of project-based revenue recognition remain central to the company’s risk/return profile. [S1] [S2] [N3]
How Fixed-Fee Contracts Shape Revenue, Margins, and Risk
Hackett Group’s revenue model centers on professional services delivered primarily through fixed-fee contracts, where fees are set in advance and revenue is recognized over time based on estimated project completion. This approach can offer predictable topline visibility and incentivize operational efficiency, but it also exposes the company to estimation risk: if actual project costs exceed initial assumptions, realized margins can be compressed or negative.
Personnel costs are the dominant expense, reflecting the labor-intensive nature of consulting and advisory services. Significant stock compensation indicates a strategic focus on attracting and retaining high-value talent, which is critical for client delivery and company reputation. Operating leverage is present but limited by the variable nature of human capital costs—margins may expand with higher utilization rates, but a downturn in project flow or mispricing of contracts can quickly erode profitability.
The company’s capital needs are moderate compared to asset-heavy sectors, but the increased long-term debt signals either investment in growth initiatives or a shift in financial strategy, which could amplify returns if growth materializes but magnifies downside if estimates prove optimistic. The key economic hinge is management’s ability to accurately scope, price, and deliver projects within budgeted assumptions.
The fixed-fee contract structure inherently transfers a degree of project risk from clients to Hackett Group, necessitating robust project management and forecasting capabilities. This risk transfer can incentivize efficiency but also requires sophisticated cost controls and contingency planning to mitigate potential overruns. Furthermore, the timing of revenue recognition under fixed-fee agreements can introduce volatility in reported financials if project milestones are adjusted or if there are changes in estimated completion percentages. Such volatility underscores the importance of transparent and conservative estimation methodologies to maintain investor confidence and avoid earnings surprises.
Advisory Differentiation, Talent Dynamics, and Market Counterforces
Hackett Group competes in a fragmented professional services landscape, facing pressure from global consulting majors, niche boutiques, and technology-enabled advisory firms. Its competitive positioning depends on a blend of proprietary methodologies, domain expertise, and the ability to deliver measurable client value within agreed timelines and budgets.
Investment in human capital—evidenced by stock compensation—is both a strength and a vulnerability: it can attract top-tier consultants, but retention is challenged by industry-wide demand for experienced professionals and the risk of losing key personnel to competitors. Switching costs for clients are relatively modest in consulting, emphasizing the importance of relationship management, intellectual property, and consistent delivery.
Technology substitution is an emerging counterforce. Digital transformation and AI-enabled tools may automate or commoditize certain advisory functions, pressuring pricing power for traditional consulting engagements. The question is whether Hackett can integrate technology into its offerings to enhance differentiation, client stickiness, and margin structure.
If Execution Discipline and Strategic Investment Drive Outperformance
The most favorable scenario for Hackett Group rests on management’s ability to consistently estimate project scope and costs, maintaining or expanding margins on fixed-fee contracts. If the company leverages its human capital investment to win higher-value, tech-enabled projects, it could further differentiate itself in a crowded market and command premium pricing.
Strategic use of increased leverage could amplify returns—if debt-funded initiatives lead to sustainable revenue growth and operational scale without material estimation errors. Upside would be confirmed by continued quarterly earnings beats, margin expansion, reduced revenue volatility, and evidence of successful technology integration into client solutions.
Falsification would come from missed estimates, rising cost overruns, or a spike in project rework/write-downs, which would indicate that the estimation process is not robust enough to sustain profitable growth.
Sustained but Bounded Growth Amid Estimation and Competitive Constraints
The most plausible outlook is for Hackett Group to maintain steady, incremental growth in revenue and earnings, with periodic fluctuations driven by project mix, client demand, and the inherent estimation risk of fixed-fee contracts. Margins may remain stable or improve modestly if utilization rates are high and project scoping remains disciplined.
Confirmation of this scenario would involve a continued pattern of meeting or slightly exceeding consensus estimates, stable or gradually improving operating margins, and manageable debt service. Evidence of retention of key personnel and client relationships would support ongoing competitiveness.
This scenario would be challenged if competitive pressures intensify, leading to price erosion, or if a downturn in client demand results in underutilization of consulting capacity.
Estimation Errors, Debt Overhang, and the Risks of Project Mispricing
The principal downside risk is that Hackett Group’s management underestimates project complexity or costs on fixed-fee engagements, leading to margin compression, project losses, or revenue reversals. A pattern of estimation errors would undermine investor confidence and could trigger financial restatements or client disputes.
Rising long-term debt compounds this risk by increasing fixed obligations—if operating income falters, leverage could constrain strategic flexibility, potentially leading to cost-cutting, layoffs, or curtailed investment in talent and technology. Competitive dynamics could exacerbate these pressures if clients shift to lower-cost or more technologically advanced rivals.
Downside would be confirmed by missed earnings, declining margins, increased write-downs or project rework, and signs of talent attrition, all of which would signal that the current economic and operational model is under strain.
Factors That Will Determine Hackett Group’s Long-Term Advantage
Quarterly trends in margins and project profitability, especially in the context of fixed-fee contract performance.
Frequency and magnitude of project write-downs or revenue reversals related to estimation errors—if disclosed.
Utilization rates of consulting personnel, which would indicate operational efficiency and demand health—would help test the thesis.
Retention rates of key consultants and management, especially given the importance of human capital.
Level and cost of long-term debt service relative to operating cash flow.
Adoption and integration of technology-enabled advisory services, as evidenced by new offerings or client wins.
Client concentration and renewal rates, which would indicate the stickiness of relationships and revenue visibility—if disclosed.
Changes in competitive positioning or market share within core advisory segments—would provide insight into relative performance.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments