
1-800-FLOWERS: Strategic Refocus Meets Liquidity Headwinds in a Competitive E-Commerce Landscape
1-800-FLOWERS has divested key personalization subsidiaries to streamline operations, but ongoing net losses, shrinking liquidity, and intensifying digital competition threaten both its turnaround prospects and its standing in the online gifting sector.
1-800-FLOWERS has exited major personalization businesses to concentrate on core floral and gifting e-commerce. The company’s future will hinge on its ability to stabilize revenue, improve margins, and differentiate in a crowded market, with operational execution and working capital management as central tests ahead. [S2] [N4] [N5]
1-800-FLOWERS has reached an inflection point. After divesting its personalization businesses for $45 million in October 2026, the company is now more tightly focused on its core floral and gifting e-commerce platform. Yet this strategic simplification comes amid mounting financial pressures: liquidity ratios have fallen below safe thresholds, net losses have deepened, and revenue trends are negative. The company's ability to regain profitability and financial stability will depend not just on cost management and operational focus, but also on how effectively it can defend its market position in an increasingly competitive digital landscape. [S2] [N4] [N5]
Recent Divestitures and Financial Pressures Redefine the Operating Reality
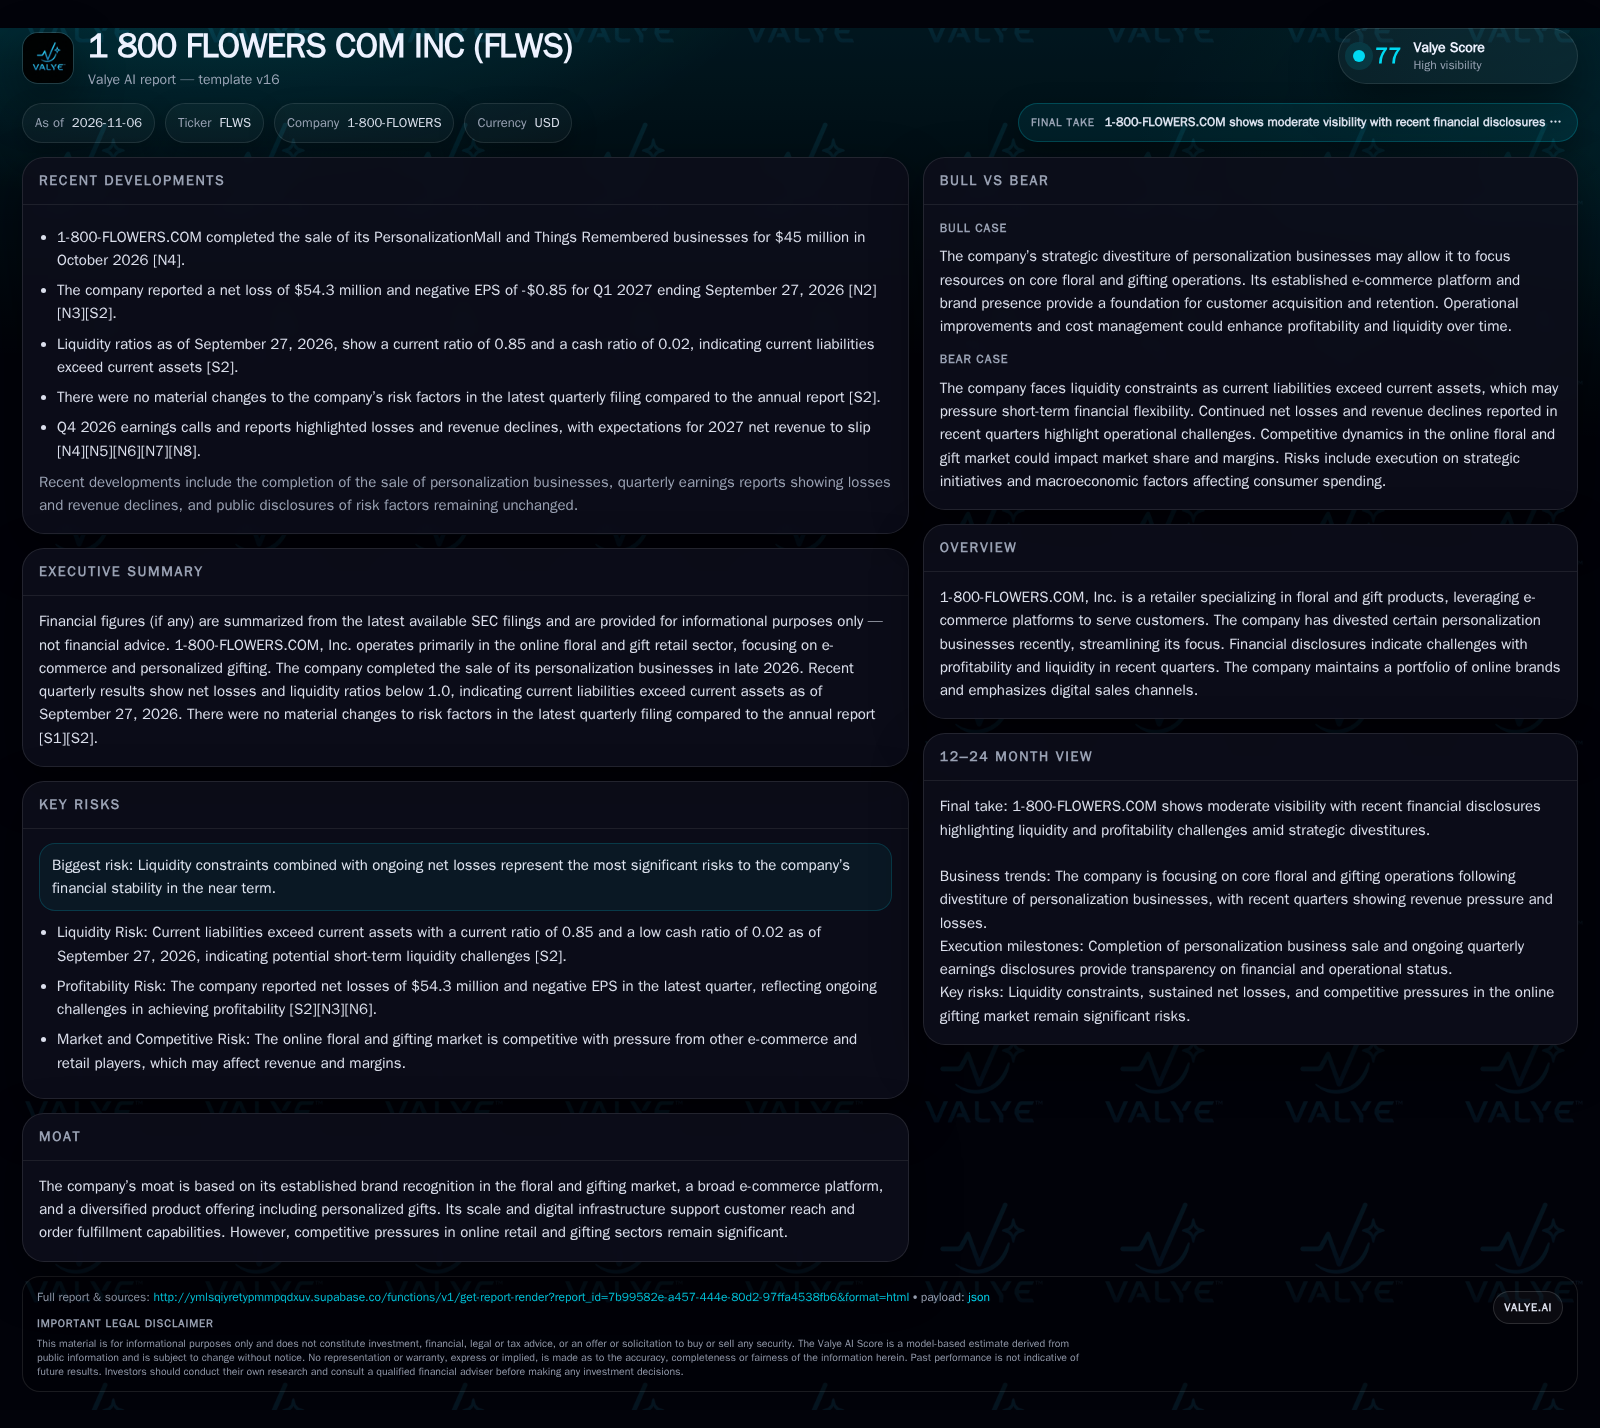
The most material recent development for 1-800-FLOWERS is the sale of its PersonalizationMall and Things Remembered businesses for $45 million in October 2026. This strategic divestiture signals a return to core floral and gifting operations, potentially freeing up management attention and resources for the legacy e-commerce platform [N4] [N5]. However, this comes as financial pressures intensify: as of September 27, 2026, the company reported a net loss of $54.3 million for the quarter, with EPS at -$0.85 [S2] [N2] [N3]. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S2] Revenue has also declined, and management has guided for continued softness in 2027 [N4] [N7]. These facts together underscore a business in transition, but one with little margin for operational misstep.
How the Core E-Commerce Model Drives (and Constrains) Profitability
1-800-FLOWERS’s business model centers on the online sale of floral arrangements and gift items, leveraging digital channels for both customer acquisition and transaction fulfillment. Revenues are driven by seasonal demand (notably Valentine’s Day, Mother’s Day, and major holidays) as well as everyday gifting occasions. The divestiture of PersonalizationMall and Things Remembered likely reduces operational complexity and capital requirements, but also removes higher-margin, customizable product lines that could have contributed to basket size and differentiation.
The economics of online gifting are challenging: customer acquisition costs can be high, especially in competitive digital ad markets, and fulfillment logistics (including perishability for flowers) create meaningful variable and fixed costs. Gross margins are typically pressured by promotional activity and the need to compete with both large e-commerce platforms and specialized direct-to-consumer brands. The company’s recent net losses suggest that either fixed costs remain too high for current volumes, or that variable margins are under pressure from discounting or inefficient fulfillment.
Operating leverage can be substantial if the company can restore volume growth and improve order economics, but with current revenue declines and reported liquidity position, the risk is that fixed costs cannot be adequately absorbed. The recent cash ratio of 0.02 highlights very reported liquidity metrics that do not by themselves establish financial flexibility, technology, or customer experience upgrades without external financing or rapid margin improvement [S2].
Brand Strength vs. Digital Disruption: The Shifting Competitive Landscape
1-800-FLOWERS benefits from longstanding brand recognition and a history of e-commerce capability in the gifting sector. Its brand portfolio and digital infrastructure provide scale and reach that many smaller competitors lack. However, the competitive environment has intensified as large horizontal e-commerce players (such as Amazon), vertically integrated floral startups, and nimble DTC brands have eroded traditional customer loyalty and pricing power.
The company’s ability to differentiate rests on a combination of brand trust, breadth of selection, nationwide fulfillment capacity, and personalized gifting options. The recent divestiture narrows the personalization offering, which could weaken differentiation versus competitors that are leaning into customization and experiential gifting. Meanwhile, the pressure to match delivery speed and convenience set by larger platforms raises the bar for operational execution.
Switching costs for customers are low, as gifting is often occasion-driven and not deeply habitual. Retention hinges on convenience, perceived value, and past positive experiences. If 1-800-FLOWERS is unable to invest in digital experience, marketing, or product innovation due to liquidity constraints, its competitive position could deteriorate further.
A Turnaround Built on Core Focus and Margin Recovery
The favorable scenario for 1-800-FLOWERS is that the strategic refocus on core floral and gifting operations yields operational efficiencies, clearer brand messaging, and better cost discipline. Freed from the management distraction and capital needs of the divested personalization subsidiaries, the company could prioritize improving order economics, optimizing fulfillment, and tightening expense controls.
Upside would be confirmed by stabilization or modest growth in core floral/gifting revenue, a noticeable reduction in operating losses, and improvement in gross and operating margins. Evidence would include positive year-over-year revenue comps in major gifting quarters, improved cash flow from operations, and a reported liquidity-ratio trends (toward or above 1.0) without reliance on external capital. Early indications might also include customer retention metrics or higher average order values if disclosed.
This scenario could be further supported by successful new product launches, digital marketing campaigns that drive incremental traffic at lower acquisition costs, or strategic partnerships that expand customer reach without significant capital outlay.
Core Operations Under Strain: Stabilization but No Quick Recovery
The most plausible near-term outcome is that 1-800-FLOWERS remains under profit and liquidity pressure as it works through the transition period following its divestitures. Revenue may continue to decline or remain flat given competitive headwinds and cautious consumer spending, especially if discretionary gifting is soft. Margins could improve modestly as cost structures are reset post-divestiture, but fixed costs and fulfillment challenges may limit the pace of recovery.
In this scenario, the company avoids a liquidity crisis through incremental cost reductions, working capital discipline, or potentially modest asset sales, but does not generate enough free cash flow to materially reinvest in growth or regain pricing power. Confirming evidence would include continued negative but narrowing EPS, a stable or slowly reported liquidity-ratio trends (remaining below 1.0), and lackluster revenue trends. Falsifying evidence would be either a sharp revenue rebound or a further acceleration of losses and liquidity deterioration.
Liquidity Erosion and Competitive Attrition Accelerate
The adverse scenario is that revenue declines persist or accelerate, operational cost reductions fail to keep pace, and liquidity deteriorates further. With a current ratio of 0.85 and a cash ratio of 0.02, the company could face pressure to secure external financing, which may be costly or dilutive given recent losses [S2]. Inability to invest in customer experience, marketing, or fulfillment could result in further market share loss to better-capitalized or more innovative competitors.
Downside confirmation would come from continued widening of net losses, further erosion in liquidity ratios, negative operating cash flow, and potentially adverse credit or vendor terms. Early warning signs would include missed or delayed supplier payments, increased customer complaints about service levels, or management signaling ‘strategic alternatives’ such as asset sales, equity raises, or restructuring.
Operational and Financial Milestones That Will Shape 1-800-FLOWERS’s Next Chapter
Quarterly trends in revenue for core floral and gifting segments, especially during peak holiday periods, will be critical to assessing demand stabilization or further slippage.
Gross and operating margin progression, as these will indicate whether cost control and operational focus are offsetting top-line pressures.
Current and cash ratios in future filings, as these are direct indicators of short-term potential financial flexibility and potential liquidity risk.
Customer retention rates and repeat order frequency, if disclosed, to gauge brand loyalty and the effectiveness of digital engagement strategies.
Average order value and customer acquisition cost, which would clarify the company’s unit economics and marketing efficiency (if disclosed).
Evidence of any external financing, asset sales, or restructuring announcements, as these may signal acute liquidity stress or strategic pivots.
Management commentary or disclosure of new digital product features, partnerships, or marketing initiatives that could impact differentiation and growth trajectory.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments