
GlobalTech Corp: Diversification Ambitions Meet Financial and Operational Tension
With a reported cash balance, related-party financing, and recent internal control lapses, the company’s ability to convert cross-sector investments into sustainable value remains uncertain.
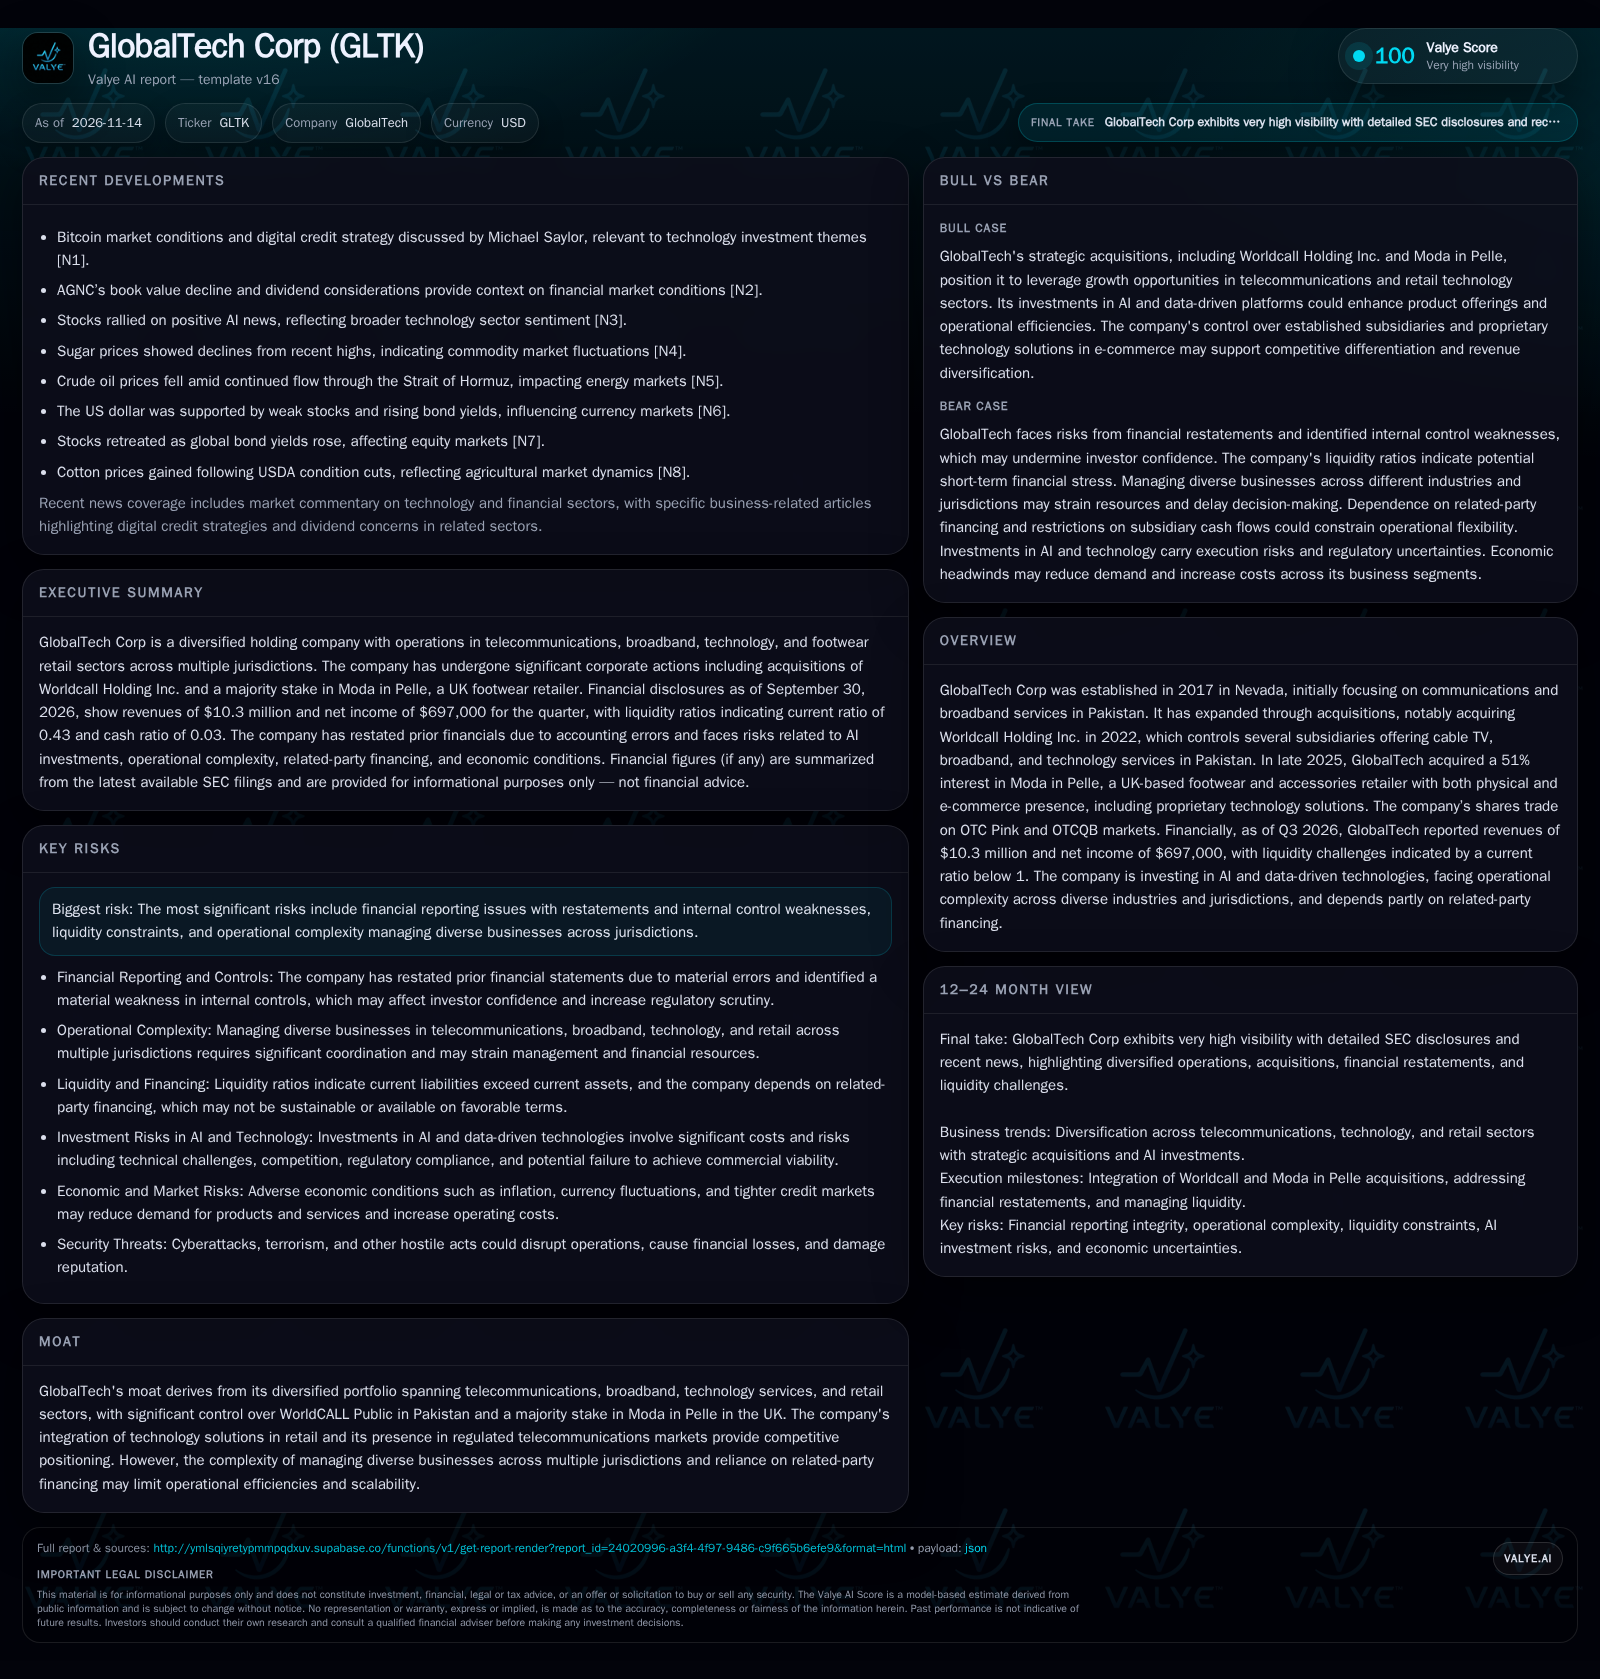
GlobalTech Corp controls telecom and broadband assets in Pakistan and recently acquired a majority stake in a UK footwear retailer, Moda in Pelle. Its AI and technology investments could drive future growth but carry high execution and regulatory risk. The thesis pivots on GlobalTech’s capacity to integrate disparate businesses, manage cash flow, and restore investor confidence after financial restatements. [S2]
GlobalTech Corp illustrates both the promise and peril of rapid business diversification. With roots in Pakistani telecommunications and broadband, the company has expanded its portfolio to include a controlling position in a UK footwear and accessories retailer, Moda in Pelle. While these moves offer exposure to secular growth in digital connectivity and e-commerce, they also create acute management, integration, and financial challenges. Whether GlobalTech can successfully transform its acquisitions and technology bets into sustainable value will hinge on disciplined execution and restoring confidence after financial restatements. [S2]
Recent Acquisitions and Financial Strain Define Current Reality
As of September 30, 2026, GlobalTech reported quarterly revenues of $10.3 million and net income of $697,000, signaling ongoing commercial activity but modest profitability relative to its operational complexity. [S2]
The December 2025 acquisition of a 51% interest in Moda in Pelle, a UK women’s footwear and accessories retailer with both brick-and-mortar and e-commerce operations, marks a major expansion beyond its Pakistani telecom roots. This follows the 2022 acquisition of Worldcall Holding Inc., giving GlobalTech effective control over WorldCALL Public and its cable TV, broadband, and tech services in Pakistan. [S2]
A material restatement of financials for 2025 and interim 2026 due to errors in deferred tax accounting, alongside identified material weaknesses in internal controls, has further complicated the company’s standing with investors and regulators. [S2]
The company’s dependence on approximately $3.74 million in outstanding interest-free related-party loans and the fact that a $3 million revolving credit facility for Moda in Pelle has not yet been made available due to cash constraints, highlight GlobalTech’s ongoing funding fragility. [S2]
How GlobalTech’s Diverse Segments Could Shape Cash Flows
GlobalTech’s business model now spans three primary domains: telecommunications/broadband in Pakistan (via WorldCALL), UK-based retail (Moda in Pelle), and technology/AI investments. Each segment operates under distinct economics and capital requirements.
Telecom and broadband services in Pakistan typically rely on a high fixed-cost base (infrastructure, spectrum, regulatory fees) with revenue driven by subscriber volume and service mix (voice, data, enterprise solutions). Margins can be attractive if subscriber growth and ARPU (average revenue per user) increase, but are highly sensitive to price competition, regulatory changes, and currency devaluation. Capital expenditures for network upgrades and service expansion are lumpy and may require external financing.
Moda in Pelle, as a retail and e-commerce operator, faces classic retail economics: gross margins depend on product mix (footwear, accessories) and channel (in-store vs. online), while operating leverage is driven by store footprint, logistics, and digital marketing efficiency. The integration of proprietary technology solutions could, if successful, enhance conversion, basket size, and customer retention, but also requires ongoing investment and adaptation to fast-moving fashion and retail tech trends.
AI and data-driven technology investments are inherently high risk/high reward. Commercial success depends on developing scalable, differentiated products or services that can either augment existing business lines (e.g., retail personalization, telecom analytics) or be licensed to third parties. These endeavors are capital-intensive and may not achieve near-term returns, especially if technical or regulatory hurdles delay commercialization.
Navigating Complexity: Competitive Advantages and Limitations
GlobalTech’s competitive position is built on geographic and sectoral diversification, with strong local presence in Pakistani telecom and an established retail brand in the UK. In theory, this diversification could buffer the company against sector-specific downturns and enable cross-pollination of technology and operational best practices.
In the Pakistani telecom and broadband market, barriers to entry include capital intensity, regulatory licensing, and entrenched customer relationships. However, the sector is highly competitive, with price wars and regulatory interventions common. Currency volatility and inflation add external risk, and public telecom incumbents often have scale advantages.
Moda in Pelle competes in the UK’s mature and crowded footwear/apparel market, facing both large omnichannel brands and digitally native e-commerce players. Its proprietary sales technology could offer some differentiation if it demonstrably improves customer acquisition or retention, but the fast pace of retail tech innovation and consumer fickleness mean any edge is likely to be fleeting unless continually reinvested.
GlobalTech’s reliance on related-party loans and limited access to third-party capital may constrain its ability to scale or respond to competitor moves. Moreover, the company’s operational complexity—spanning regulated telecom, fashion retail, and unproven AI ventures—could dilute management focus and slow execution relative to more specialized rivals.
What a Successful Integration and Tech Upside Could Look Like
If GlobalTech achieves smooth integration of WorldCALL and Moda in Pelle, it could realize synergy benefits such as shared technology platforms, data analytics, and centralized procurement, driving both cost savings and incremental revenue across segments. The deployment of AI and data-driven solutions might improve customer targeting in retail, optimize network performance in telecom, or create new licensing revenue streams.
A positive scenario would involve stabilization (or improvement) in liquidity—perhaps through improved working capital management, renewed access to credit lines, or successful monetization of technology assets. Regulatory and operational hurdles in Pakistan remain manageable, and Moda in Pelle’s proprietary tech delivers measurable uplift in digital sales and customer engagement.
Evidence confirming this scenario would include: reversal of internal control weaknesses, demonstrated improvement in cash flow from operations, successful launch or licensing of AI-driven products, and sustained (or growing) market share in both telecom and retail segments. Announcements of external capital raises on favorable terms, or a step change in Moda in Pelle’s e-commerce metrics, would also support the bullish case.
Cross-Sector Diversification Sustains Operations, But Pressures Remain
The most plausible outcome is that GlobalTech maintains operations across its existing portfolio, with moderate growth in telecom and retail offset by ongoing liquidity constraints and integration complexity. AI and technology investments may show early signs of promise but are unlikely to materially impact group earnings in the near term.
Management’s focus is split between stabilizing cash flow, addressing financial reporting weaknesses, and extracting incremental value from acquisitions. Some operational improvements are made—such as modest cost reductions in telecom or incremental digital growth in Moda in Pelle—but these are largely absorbed by high interest in working capital and ongoing investment needs.
Confirmation of this scenario would be continued modest profitability, persistent (but not worsening) liquidity stress, gradual improvement in internal controls, and steady but unspectacular performance in both core business lines. Lack of major new capital raises or transformative product launches would further support the base case.
Funding Gaps and Control Failures Could Trigger Value Erosion
If liquidity continues to deteriorate, GlobalTech could face payment defaults, forced asset sales, or loss of control over key subsidiaries. The company’s dependence on related-party financing may become unsustainable if lenders withdraw support or require onerous terms. Failure to resolve internal control weaknesses could result in regulatory penalties, auditor resignations, or further restatements, compounding investor mistrust.
Operationally, an inability to integrate Moda in Pelle or realize technology-driven synergies could lead to underperformance and cash burn in the retail segment, while WorldCALL’s exposure to Pakistani macroeconomic volatility could depress telecom earnings. AI and technology investments may prove non-viable, consuming resources without commercial return.
Evidence of this scenario would include: further declines in cash and working capital, inability to access external credit, negative auditor commentary, regulatory investigations, or abrupt turnover in senior management. Material market share loss or store closures at Moda in Pelle, or customer defections in telecom, would also signal a deteriorating outlook.
Milestones and Metrics That Will Decide GlobalTech’s Value Trajectory
Quarterly operating cash flow trends—any sustained improvement or further deterioration would provide early evidence of liquidity trajectory.
Resolution of internal control weaknesses and restatement issues; auditor or regulatory commentary would be especially telling.
Performance of Moda in Pelle’s e-commerce and proprietary technology solution—metrics such as online sales growth, customer retention rates, or conversion uplift (if disclosed) would help test the technology value proposition.
Access to and terms of third-party financing or credit lines, especially the eventual availability of the Moda in Pelle revolving credit facility.
Sustained profitability or margin improvement in the Pakistani telecom segment, particularly in the face of inflation and currency headwinds.
Progress and commercial traction in AI and data-driven technology initiatives—a useful metric would be signed contracts, pilot deployments, or new product launches.
Related-party funding continuity—any change in lender appetite or terms could quickly impact operational flexibility.
Cash repatriation from subsidiaries to the parent company, given regulatory and operational restrictions—actual intercompany transfers (if disclosed) would provide evidence of financial agility.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments