
Greenlit Ventures: Early-Stage Ambition Meets Severe Constraints in Consulting and Encryption
With zero liquidity, a single employee, and mounting losses, Greenlit Ventures’ expansion into digital privacy tools faces steep structural and financial hurdles. The company’s dual focus—consulting for Asian firms and ForceShield-branded encryption—offers theoretical upside, but survival depends on urgent capital infusion and execution against formidable competitors.
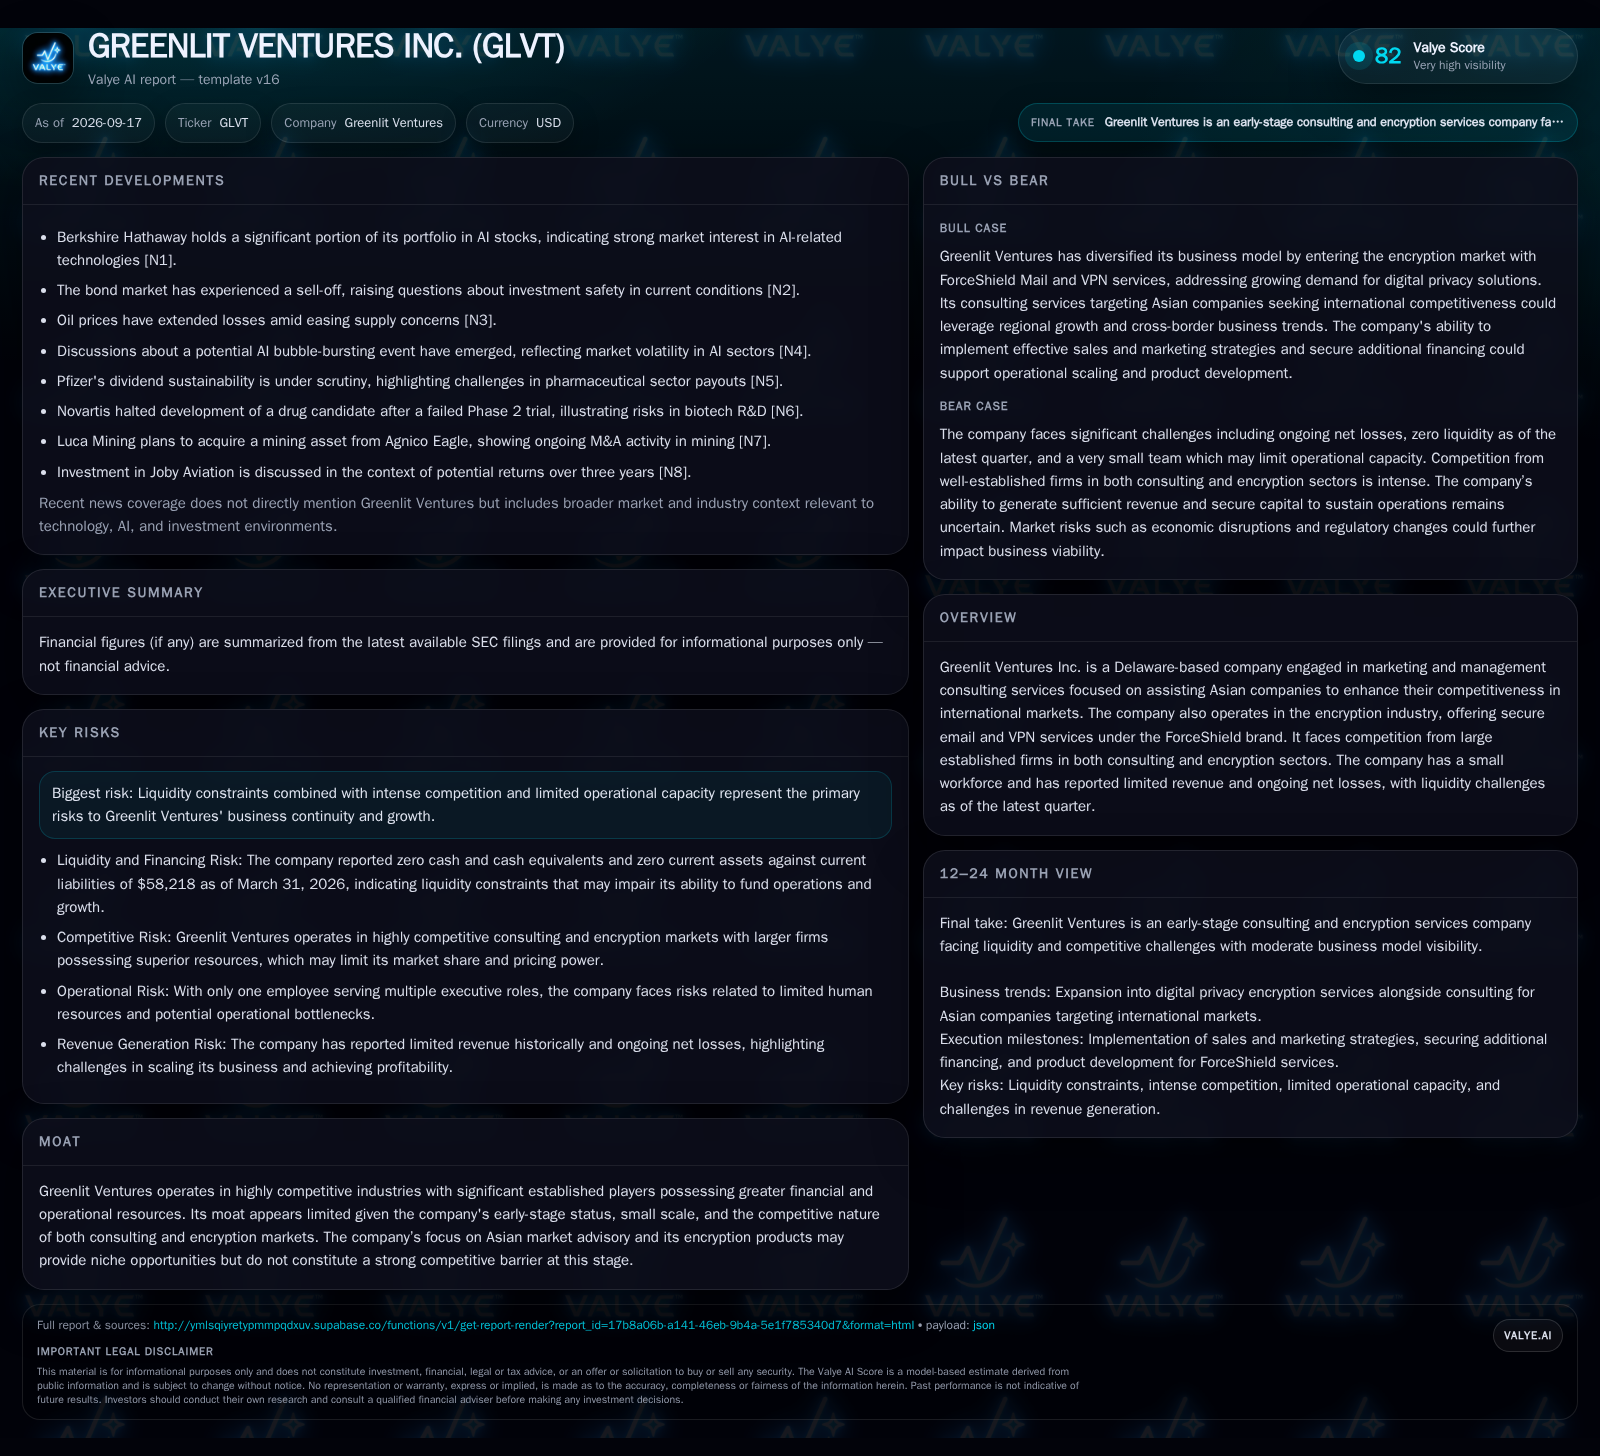
Greenlit Ventures Inc. is a one-employee company providing consulting to Asian businesses and developing ForceShield encryption products. As of March 31, 2026, it reported zero cash, $58,218 in current liabilities, and ongoing losses, raising immediate viability concerns. The company operates in highly competitive sectors, and its continuation hinges on securing financing and demonstrating real market traction in either business line. [S2]
Greenlit Ventures Inc. exemplifies the highest-risk end of the micro-cap spectrum: a Delaware corporation with a single employee, no cash, and a dual business model spanning Asia-focused consulting and nascent encryption products. The company’s immediate future will be determined less by strategy than by its ability to secure funding before operational capacity is exhausted.
Liquidity Collapse and Minimal Staffing Define Immediate Reality
As of March 31, 2026, Greenlit Ventures reported zero cash and current assets against $58,218 in current liabilities, resulting in a current and cash ratio of zero. The company posted a net loss of $18,496 for the quarter and had only one employee—Fu Yong Nan—serving as CEO, CFO, Secretary, and sole Director. These facts underscore acute liquidity stress and expose the company to operational bottlenecks and key-person risk. With no reported cash balance, Greenlit Ventures must either rapidly raise capital or generate revenue to avoid insolvency. [S2]
How Greenlit Ventures Might Monetize Consulting and Encryption
Greenlit Ventures’ business model consists of two disparate lines: management and marketing consulting for Asian companies seeking international expansion, and ForceShield-branded encryption products (secure email and VPN). Consulting economics are typically project-based or retainer-driven, with revenues dependent on client acquisition, pricing power, and repeat engagements. However, the absence of disclosed active contracts or recurring revenue mechanisms leaves scalability and sustainability in doubt.
ForceShield Mail and VPN—both in beta—target the growing digital privacy market. If commercialized, potential revenue models could include subscription fees, usage-based pricing, or enterprise licensing. Each route requires substantial up-front investment in product development, security assurance, infrastructure, and marketing. With only one employee and no liquidity, Greenlit Ventures is unlikely to achieve meaningful operating leverage or benefit from scale economies unless it secures new resources. The company’s capital needs are immediate and acute; even modest user acquisition would require external financing for support, infrastructure, and compliance.
The consulting segment’s revenue potential is inherently tied to its ability to develop trust and credibility within target client bases, which often requires a track record of successful engagements and domain expertise. Given the single-employee constraint, the company’s capacity to simultaneously acquire new clients, deliver quality consulting services, and nurture long-term relationships is severely limited. This bottleneck could result in a slow sales cycle and inconsistent revenue streams, undermining efforts to establish a stable financial footing. Additionally, the consulting market’s competitiveness often pressures firms to offer discounted rates or flexible terms, which may further compress margins and strain cash flow in the absence of scale.
On the encryption product front, monetization strategies must carefully balance user acquisition costs with lifetime customer value. Subscription-based models, while predictable, require sustained engagement and feature differentiation to minimize churn, especially in a market crowded with established providers offering free or low-cost alternatives. Usage-based pricing introduces complexity in billing and forecasting but can align revenue with customer activity. Enterprise licensing demands significant upfront sales efforts and compliance certifications, which are resource-intensive. Without dedicated teams for development, marketing, and customer support, the company’s ability to refine product-market fit and respond to security vulnerabilities or regulatory requirements remains questionable, potentially impeding commercial viability.
Competing Against Giants in Consulting and Cybersecurity
Greenlit Ventures faces formidable competitors in both of its target sectors. In consulting, it contends with global firms such as Morgan Stanley and Bank of America, which possess deep client relationships, established brands, and extensive resources. In encryption, it is up against cybersecurity and privacy stalwarts like Trend Micro, Cisco, Sophos, Zoho Mail, and BAE Systems—companies with advanced technology stacks, trusted reputations, and global distribution.
Given its micro-scale, lack of funding, and absence of a specialized team, Greenlit Ventures has no obvious cost, technology, or relationship advantage. Its only plausible wedge is niche focus: providing tailored consulting for Asian companies seeking internationalization, and possibly targeting under-served privacy segments with ForceShield. However, the lack of a demonstrable moat—such as proprietary technology, network effects, or strong client lock-in—makes its position extremely vulnerable to substitution and competitive displacement.
A Turnaround Hinges on Capital and Niche Customer Traction
The most favorable scenario would see Greenlit Ventures secure external financing—perhaps through equity, debt, or a strategic partnership—allowing it to maintain operations and invest in sales, product development, and customer acquisition. With funding in place, the company could focus on converting ForceShield’s beta users into paying subscribers, targeting privacy-conscious individuals or small businesses in Asia and internationally.
In consulting, establishing a credible track record with a few anchor clients could generate referral business and recurring engagements. Success would be confirmed by a material increase in revenue, positive cash flow, expanded headcount, and customer testimonials. Falsification would be evident if the company fails to close a financing round, continues to report negligible revenue, or loses its only employee.
Stagnation Likely Without Immediate Funding or Revenue Breakthrough
The most plausible near-term scenario is continued operational struggle. Without new capital, Greenlit Ventures will likely remain in a holding pattern—unable to scale ForceShield or land meaningful consulting contracts. The single-employee structure creates execution risk and limits the company’s ability to respond to even minor setbacks.
Indicators confirming this scenario would include continued reporting of minimal or zero revenue, persistent net losses, no growth in cash or assets, and unchanged staffing. Any incremental progress—such as a new customer or financing announcement—could signal a shift, but absent such developments, the company’s prospects remain constrained.
Liquidity Exhaustion and Key-Person Risk Could Trigger Failure
If Greenlit Ventures fails to secure immediate financing or generate revenue, insolvency or business cessation is a real risk. Zero cash and an ongoing burn rate mean that obligations cannot be met, potentially triggering creditor action or forced liquidation. The loss or unavailability of its sole employee would leave the company unable to operate.
Confirmation would come from bankruptcy filings, delisting, or public disclosure of business suspension. Continued absence of financing or customer traction would further corroborate this outcome.
Testing Viability: What Will Determine Greenlit Ventures’ Next Chapter?
Any announcement of new financing, equity or debt issuance, or strategic investment would signal a potential lifeline.
Material revenue growth in either consulting or ForceShield product lines would indicate early market traction.
Expansion of headcount or addition of specialized staff would suggest capacity to execute on multiple fronts.
A commercial launch (not just beta) of ForceShield Mail or VPN, along with disclosed pricing and early customer wins, would test the product’s real-world appeal.
Retention, renewal, or upsell rates for consulting clients—if disclosed—would help assess business sustainability.
Regulatory or legal developments affecting privacy or consulting markets in Asia could materially alter the opportunity set.
Any changes in executive leadership or the departure of the sole employee would have immediate operational consequences.
Evidence of customer testimonials or published case studies would offer external validation of product or service value.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments