
Regulatory Rebuilding and Portfolio Refocus: Radnostix’s Stakes in Theranostics, Compliance, and Capital Scarcity
Radnostix Inc. is navigating a period of operational reset: FDA compliance remediation, voluntary recalls, and a pending asset sale shape its near-term trajectory.
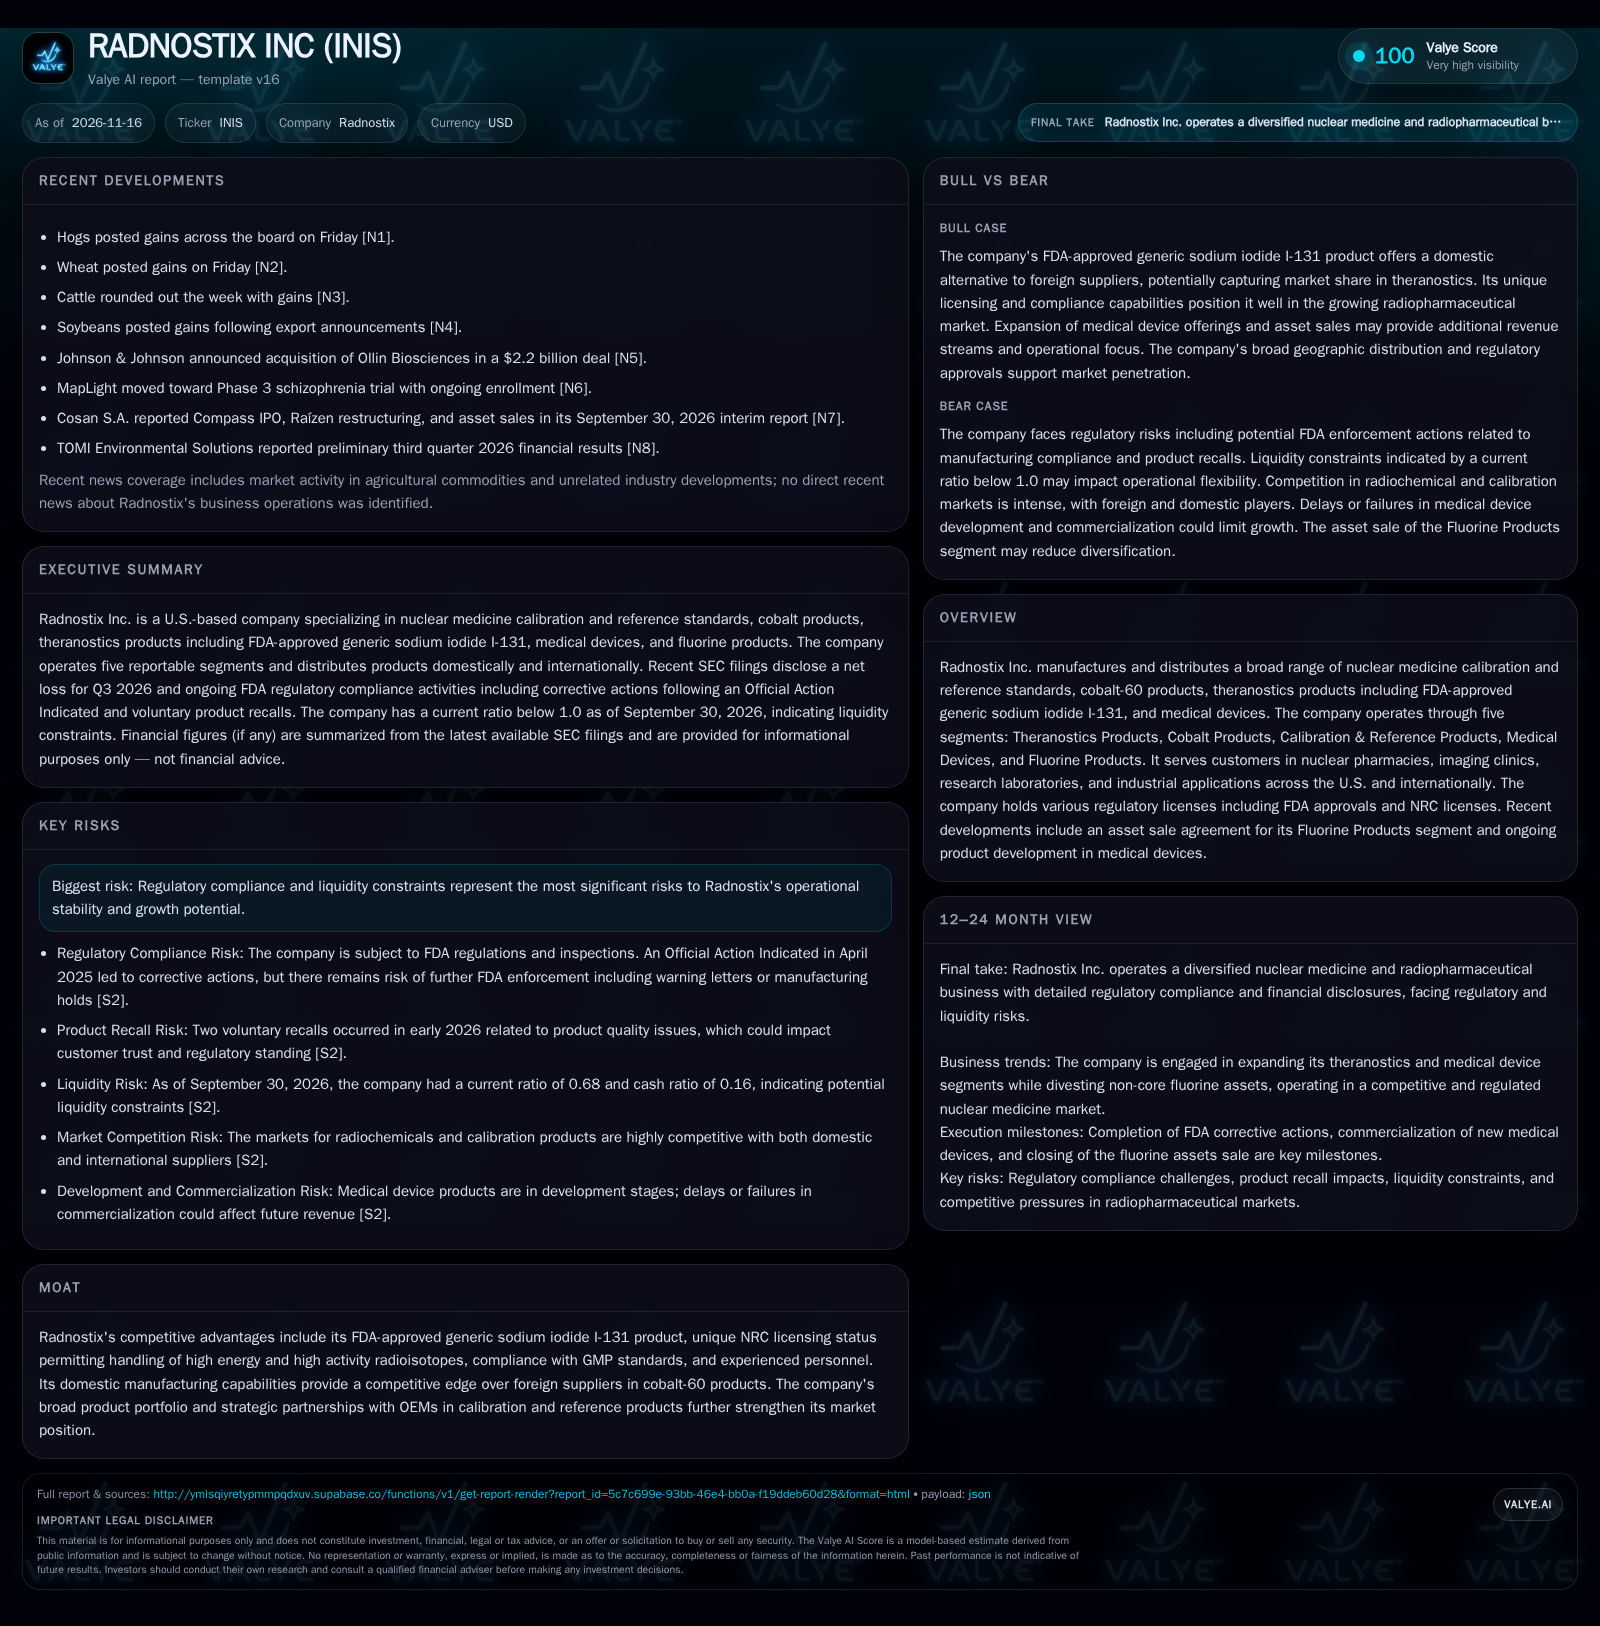
Radnostix Inc. faces a pivotal phase marked by FDA compliance remediation, voluntary recalls, and a pending $13.5M asset sale of its Fluorine Products segment. Success will hinge on operational execution, regulatory closeouts, and the ability to commercialize new medical devices while stabilizing cash flow. [S2]
Radnostix Inc. stands at a critical juncture, where operational recovery and strategic realignment are both urgent and intertwined. With FDA compliance under active remediation, a major asset sale in progress, and potential financial flexibility severely constrained, the company’s ability to regain stability depends on executing corrective actions, closing the Fluorine Products transaction, and successfully commercializing new products.
Regulatory Pressure, Recalls, and an Imminent Asset Sale Define the Present
Radnostix Inc. is currently operating under considerable regulatory and financial duress. The company underwent FDA inspections in April 2025 that resulted in an Official Action Indicated (OAI), followed by two voluntary product recalls in early 2026. While corrective actions are underway and the company is working toward formal FDA closeout, these issues have immediate implications for customer trust and operational continuity. [S2]
Financially, Radnostix reported cash and equivalents of $711,288 against current liabilities of $4,370,330 as of September 30, 2026, resulting in a current ratio of 0.68 and a cash ratio of 0.16. [S2]
A potential near-term catalyst is the pending $13.5 million asset sale of the Fluorine Products segment. If completed, this transaction could ease liquidity pressure and sharpen the company’s focus on its core radiopharmaceutical and medical device segments. Until the sale closes, however, liquidity and diversification remain at risk. [S2]
Revenue Streams, Fixed Costs, and the Leverage of Diversification
Radnostix generates revenue from five distinct segments: Theranostics Products, Cobalt Products, Calibration & Reference Products, Medical Devices, and Fluorine Products. The Theranostics segment, anchored by FDA-approved generic sodium iodide I-131, provides a critical domestic supply in a market where foreign dependency is common. The Cobalt Products segment supplies cobalt-60 for medical, research, and industrial applications, while Calibration & Reference Products serve nuclear pharmacies and imaging clinics with standards and quality control materials. [S2]
These segments differ in their economics. Theranostics and Cobalt Products may offer higher margins due to regulatory barriers and specialized production, but also require significant compliance investment and fixed overhead. Calibration and Medical Devices are likely to be more volume-driven, with pricing pressure from both domestic and international competitors. The asset sale of Fluorine Products, if consummated, will remove a capital-intensive business and potentially reduce fixed cost load, but also narrows diversification.
The company’s current liquidity snapshot highlights the acute importance of cash conversion and working capital discipline. With net losses persisting and medical devices still in development, Radnostix faces a classic biopharma capital stack: high fixed costs, lumpy revenue, and heavy dependence on regulatory milestones and non-dilutive capital events (such as asset sales) to fund operations.
Domestic Supply and Regulatory Credentials as Differentiators—But Not Moats
Radnostix’s core competitive advantages stem from its regulatory infrastructure and domestic manufacturing capabilities. The FDA-approved sodium iodide I-131 product provides a rare U.S.-based supply option, potentially attractive to buyers seeking to de-risk from foreign dependencies. NRC licenses for handling high-energy isotopes further enable service offerings in a market with substantial entry barriers. [S2]
However, these advantages are not insurmountable moats. The radiopharmaceutical and calibration markets feature both established domestic players and well-capitalized international competitors. Pricing pressure is pronounced, especially in commoditized calibration standards. In medical devices, Radnostix competes not only with legacy device manufacturers but also with emerging digital health and radiology device startups. The company’s broad portfolio and licensing position offer optionality, but sustained differentiation will require successful navigation of quality, cost, and regulatory hurdles.
The current regulatory overhang and recalls may also erode trust with key customers—especially hospitals, nuclear pharmacies, and research institutions—potentially shifting business to competitors if remediation is slow or incomplete.
If Regulatory Remediation Succeeds and Device Innovation Delivers, Value Could Be Unlocked
A favorable scenario for Radnostix would see the company securing formal FDA closeout of recent compliance issues, restoring customer confidence and clearing the path for resumed growth in its Theranostics, Cobalt, and Calibration segments. [S2]
If the company can commercialize these devices and gain traction with its FDA-approved sodium iodide I-131, it could capture incremental share from import-dependent competitors and leverage its regulatory credentials to enter new contract relationships. Evidence supporting this scenario would include a formal FDA closeout letter, closing of the asset sale, and new device launch announcements with initial sales or distribution agreements.
This scenario could be falsified by further regulatory setbacks (such as a new warning letter or enforcement action), failure to close the asset sale, or delays in device commercialization.
Stabilization Hinges on Compliance Execution and Asset Sale Timing
The most probable outcome is a period of operational stabilization: the company continues implementing FDA-mandated corrective actions, manages through cash constraints, and closes the Fluorine Products asset sale over the coming quarters. Revenue from legacy Theranostics and Cobalt segments supports baseline operations, but growth is modest as customer caution persists until regulatory issues are fully resolved. [S2]
Medical device development remains a work in progress, with limited near-term contribution to revenue. Liquidity improves incrementally if the asset sale closes and working capital discipline is maintained, but further investment or innovation is constrained by cash availability.
Confirmation of this scenario would be incremental updates on FDA compliance progress, formal asset sale closing, and steady (if unspectacular) revenue from core segments. A deviation—such as regulatory setbacks, a failed asset sale, or sharp customer attrition—would indicate downside risk.
Liquidity Squeeze and Regulatory Drag Could Trigger a Strategic Reset
In a negative outcome, Radnostix fails to secure timely FDA closeout or faces additional compliance challenges, eroding customer trust and triggering further revenue declines. If the Fluorine Products asset sale falls through or is delayed, the company’s reported cash balance (current ratio 0.68) could force cost-cutting, asset liquidation, or even restructuring. [S2]
Medical device commercialization stalls, and the company is unable to generate new sources of revenue quickly enough to offset fixed costs. In this scenario, Radnostix could lose market share to better-capitalized or more compliant competitors, and its ability to invest in innovation or defend its regulatory position would be severely diminished.
Evidence for this scenario would include additional FDA enforcement actions, missed asset sale closing, growing accounts payable, or disclosure of going concern risk.
Milestones That Will Determine Whether Radnostix Rebounds or Retreats
Formal FDA closeout of the Official Action Indicated and voluntary recall events—documentation or public confirmation would signal regulatory stabilization.
Actual closing and cash receipt from the $13.5 million Fluorine Products asset sale; evidence would include SEC filings or management disclosure.
Product launch progress for proprietary medical devices: regulatory submissions, clearances, and initial sales or distribution contracts would help test the thesis.
Quarterly revenue and margin trends in the Theranostics and Cobalt segments—particularly any sign of customer attrition or new contract wins.
Ongoing FDA inspection results or warning letters—future regulatory actions would be highly material.
Customer retention rates and feedback, if disclosed, especially among nuclear pharmacies and top imaging clinic clients.
Progress in integrating and commercializing the Lara and Ellexa systems acquired from Lucerno Dynamics—updates on technical milestones or market entry would provide clarity on future device revenue potential.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments