
Inspire Medical Systems: Neurostimulation for Sleep Apnea—Growth Drivers and Long-Term Implications
Inspire Medical Systems has established significant clinical, regulatory, and reimbursement milestones in neurostimulation-based sleep apnea therapy. The next phase depends on scaling adoption, sustaining payer support, and demonstrating durable economics versus both traditional CPAP and emerging alternatives.
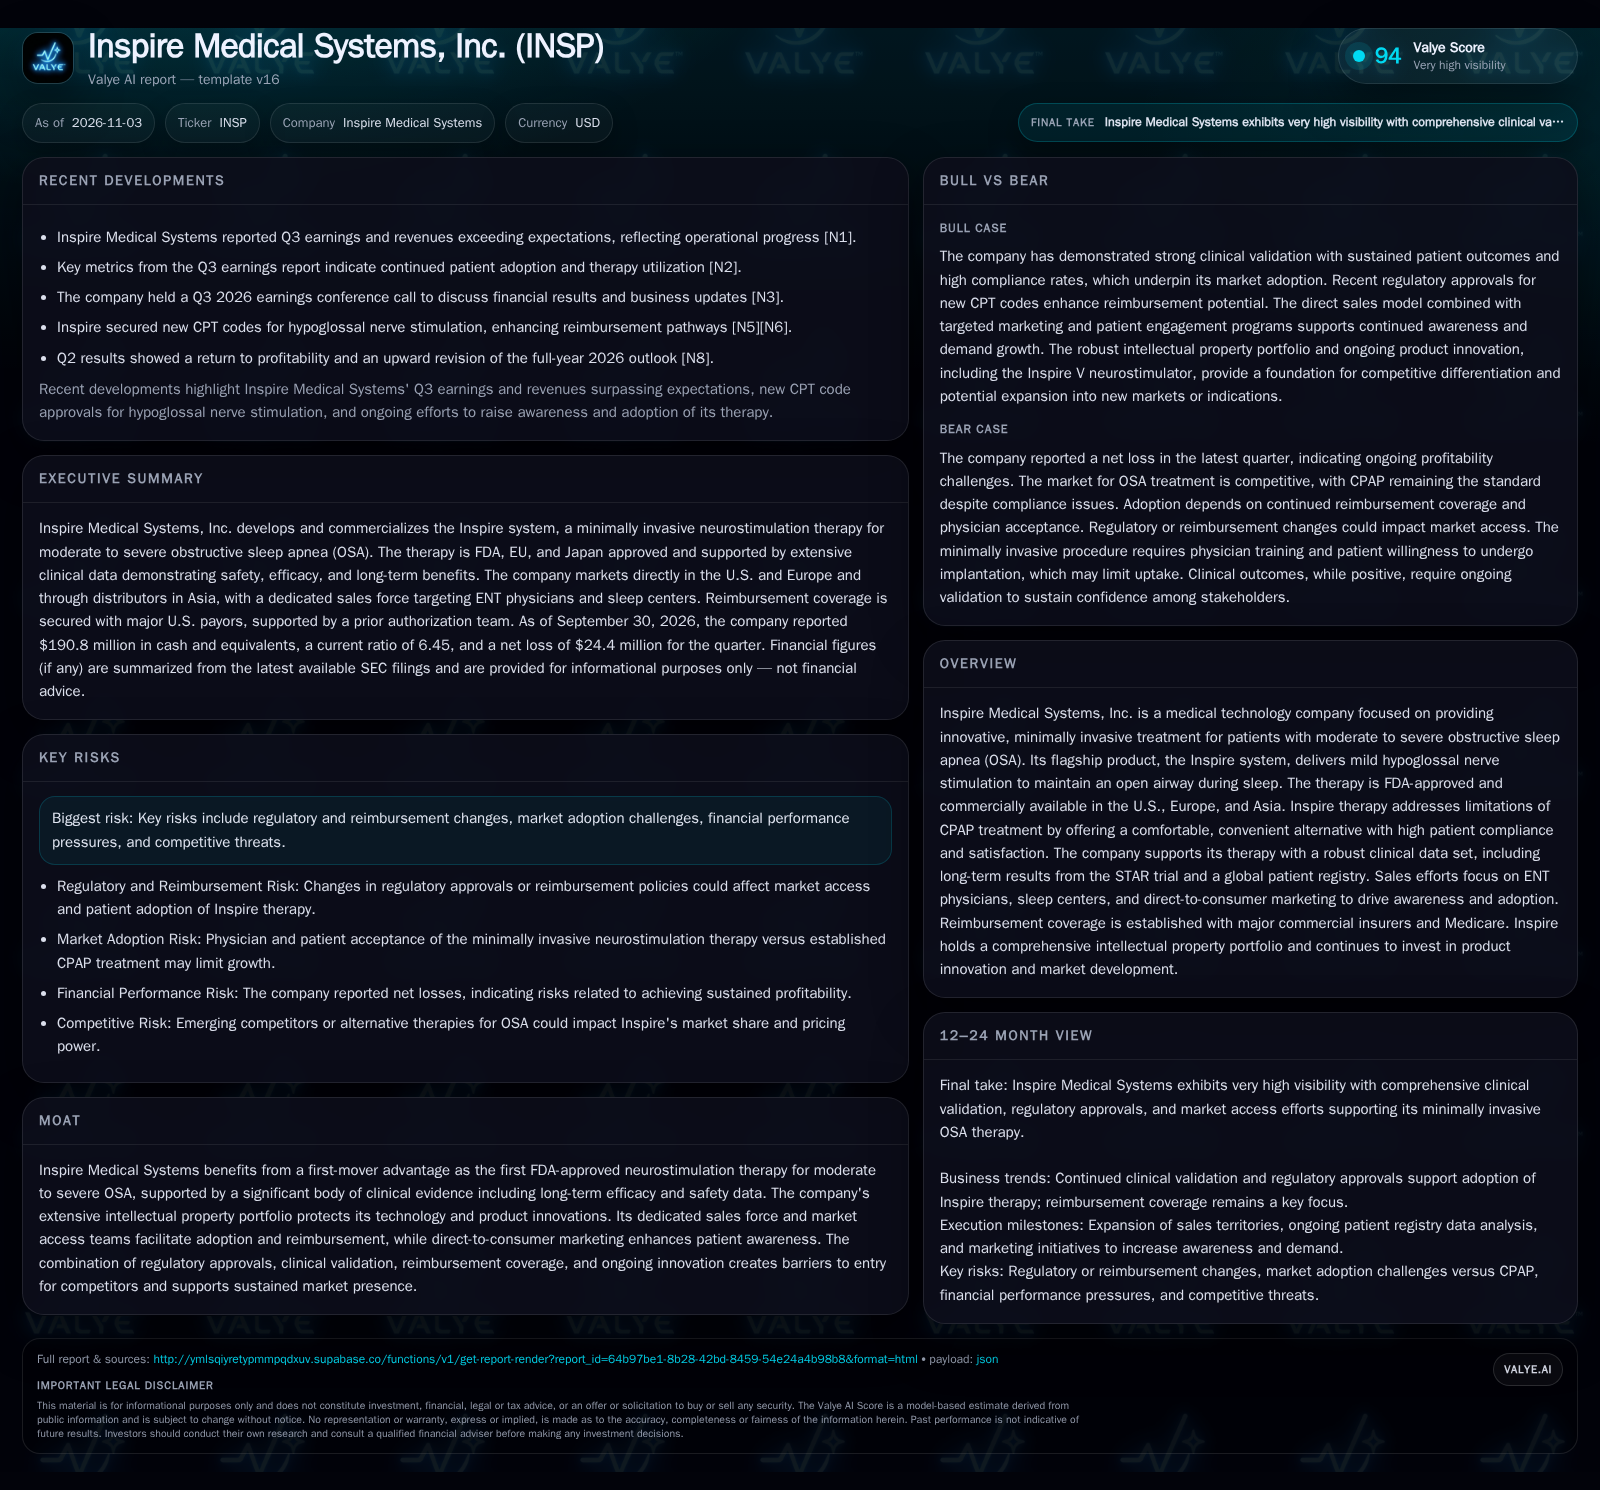
Inspire Medical Systems leads the neurostimulation segment for obstructive sleep apnea (OSA), backed by robust clinical validation and broad regulatory approval. Recent wins include new CPT codes and Q3 revenues ahead of expectations, but sustained net losses signal the challenge of scaling profitability. The company’s future hinges on further market penetration, payer dynamics, and maintaining its first-mover advantage amid intensifying competition and evolving treatment paradigms. [S1] [S2] [N1] [N2] [N5] [N6] [N8]
Inspire Medical Systems has carved out a prominent niche as the first and most clinically validated neurostimulation therapy for moderate to severe obstructive sleep apnea—a market historically dominated by CPAP devices with chronic compliance issues. With over 125,000 patients treated and recent regulatory and reimbursement wins, Inspire now faces the commercial challenge of scaling adoption, sustaining payer support, and demonstrating durable profitability in a competitive and evolving landscape. The next phase will test whether robust clinical data and a first-mover advantage can translate into sustained financial performance and deeper market penetration. [S1] [S2] [N1] [N2] [N5] [N6] [N8]
Regulatory, Commercial, and Financial Trends Influencing Investment Perspectives
Inspire Medical Systems has achieved several notable milestones as of November 2026. The company’s Inspire system is now FDA, EU MDR, and Japan PMDA-approved, and more than 125,000 patients have been treated globally—a scale that reinforces clinical and commercial leadership in neurostimulation for OSA. [S1] The Q3 2026 results showed revenue and earnings ahead of expectations, signaling operational momentum, but Inspire reported a net loss of $24.4 million for the quarter, reflecting continued investment in growth and ongoing profitability challenges. [S2] [N1] [N2] On the reimbursement front, Inspire secured new CPT codes for hypoglossal nerve stimulation, a development that clarifies and strengthens reimbursement pathways for its core procedure in the U.S. [N5] [N6] These milestones collectively advance Inspire’s market position but raise the stakes for translating clinical and regulatory achievements into sustainable economic returns.
The Impact of Inspire’s Commercial Strategy and Cost Structure on Profit Potential
Inspire generates revenue by selling its neurostimulation system directly to hospitals and ambulatory surgery centers in the U.S. and Europe, and through distributors in select Asian markets. [S1] The procedure-based business model depends on a combination of device sales, physician training, and ongoing patient support, with reimbursement from both commercial insurers and Medicare. Variable costs are driven by device manufacturing, salesforce expansion (with 295 U.S. territories and 21 international as of end-2025), and patient-support infrastructure. [S1]
Operating leverage is theoretically achievable as fixed costs—sales, marketing, and R&D—are spread over a growing base of procedures. However, Inspire’s persistent net losses suggest that the current scale is insufficient to cover high commercial and clinical investment requirements. [S2] Capital needs remain focused on salesforce expansion, product innovation (e.g., the Inspire V neurostimulator), and ongoing clinical evidence generation. The direct-to-consumer marketing and prior authorization teams represent added overhead but are essential for driving both patient demand and payer approvals in a relatively new therapy category.
Pricing power is partially supported by strong clinical validation and exclusive reimbursement codes, but future margin structure could be pressured if competitors enter with lower-cost or less-invasive alternatives, or if payers seek to negotiate discounts as procedure volume rises. The company’s extensive intellectual property portfolio (119 U.S. patents, 83 foreign) provides some defense but does not guarantee insulation from pricing or adoption headwinds. [S1]
Maintaining Market Position Versus CPAP and Emerging Alternatives
Inspire’s first-mover status in implantable neurostimulation for OSA is a significant competitive advantage, underpinned by regulatory approvals, long-term clinical data, and a growing real-world evidence base. [S1] The market, however, remains dominated by CPAP (continuous positive airway pressure), which is non-invasive and widely reimbursed, albeit with well-documented compliance issues. Inspire’s therapy targets the subset of moderate to severe OSA patients who are unable or unwilling to use CPAP—a segment with meaningful unmet need.
Barriers to entry for new implantable competitors include the need for robust clinical validation, regulatory approvals, and payer acceptance. However, several categories of competition could erode Inspire’s position over time: (1) Improved or more comfortable CPAP devices; (2) Alternative minimally invasive or non-implantable therapies; (3) Other neurostimulation or surgical approaches; (4) Pharmaceutical interventions that may address OSA mechanisms.
Inspire’s direct salesforce and DTC marketing are designed to build physician and patient loyalty, while the prior authorization team helps maintain payer access. Still, the company’s long-term moat will be tested as the therapy category matures, competitors emerge, and payers scrutinize cost-effectiveness relative to traditional and new alternatives.
Conditions Under Which Rapid Adoption Could Enhance Margins
The favorable scenario for Inspire involves continued rapid adoption driven by: (1) expanding physician comfort with the procedure, (2) increased patient demand as awareness grows, and (3) sustained, broad reimbursement coverage underpinned by the new CPT codes. If the company leverages its clinical leadership to achieve higher procedure volumes and operating leverage, fixed commercial and R&D investments could scale more efficiently, leading to margin expansion and eventual profitability.
Confirmation of this scenario would require evidence of accelerating year-over-year procedure growth, improved gross and operating margins, and a sustained track record of positive payer decisions with minimal reimbursement disputes. Additional validation would come from expansion into new geographies or patient segments (e.g., milder OSA, pediatric), and further product innovation extending the IP moat. Notably, if real-world data from the ADHERE registry continues to corroborate long-term efficacy and safety, Inspire’s clinical advantage could remain durable. [S1]
Growth Prospects Despite Competitive and Reimbursement Challenges
A plausible trajectory for Inspire is one of steady but moderating growth as the core addressable market expands but competitive and payer pressures mount. Adoption continues among CPAP-intolerant patients, aided by clinical evidence and reimbursement, but incremental growth slows as the company penetrates more challenging patient segments or faces increased scrutiny from payers over cost-effectiveness.
The company reported profitability for the period. Evidence supporting this path would include stable or moderately rising procedure volumes, gradual improvement in operating margins, and continued payer coverage with occasional challenges or delays. Conversely, signs of stagnating volume growth, increased procedure denials, or negative registry data would undermine the thesis.
Potential Effects of Reimbursement Changes or Clinical Issues on Growth
The adverse scenario is triggered if reimbursement dynamics shift unfavorably—such as payers narrowing coverage criteria, reducing payment rates, or introducing new hurdles for prior authorization. Any such moves could slow or reverse adoption momentum and compress margins. Alternatively, if new clinical data (from ongoing registry studies or independent research) raise questions about long-term efficacy, safety, or patient selection, physician and patient enthusiasm could wane, damaging procedure volume and payer support.
This scenario would be confirmed by a material drop in procedure growth rates, rising patient or physician attrition, increased prior authorization denials, or negative updates from the ADHERE registry or peer-reviewed studies. Additional risks include a rapid escalation of competition—whether from new device entrants, disruptive non-invasive therapies, or pharmaceutical approaches that shift the treatment paradigm.
Factors Influencing Inspire’s Prospects for Market Leadership
Quarterly procedure volume growth rates and changes in average revenue per procedure (if disclosed) will indicate the pace and quality of adoption.
Gross margin and operating margin trends: Improvement would signal better scale and cost discipline, while stagnation or deterioration would raise concerns about fixed-cost absorption.
Prior authorization approval rates and payer mix: Shifts in these metrics could reveal brewing reimbursement headwinds or tailwinds.
Updates from the ADHERE patient registry and new peer-reviewed clinical studies: Watch for evidence on long-term efficacy, safety, and patient satisfaction.
Expansion or contraction of sales territories, especially internationally: This would reveal management’s confidence in addressable market expansion.
Competitor pipeline disclosures, regulatory filings, or launches—especially for minimally invasive or non-implantable therapies.
Any changes in CPT code reimbursement rates or payer coverage policies that could impact per-procedure economics.
Ongoing product innovation milestones, such as the commercial uptake of the Inspire V neurostimulator or new device iterations.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments