
Innovex International: Profitability, Global Exposure, and the Realities of Currency and Competitive Uncertainty
The company’s international reach and disciplined internal controls support operational stability, but the lack of detail on business lines and industry structure leaves open questions about long-term moat and margin resilience.
However, the company’s international operations expose it to currency risks, and disclosures offer little insight into its competitive positioning or specific growth drivers. The near-term outlook is stable, but durable value creation depends on clarifying business economics, margin structure, and the real sources of competitive advantage. [S2]
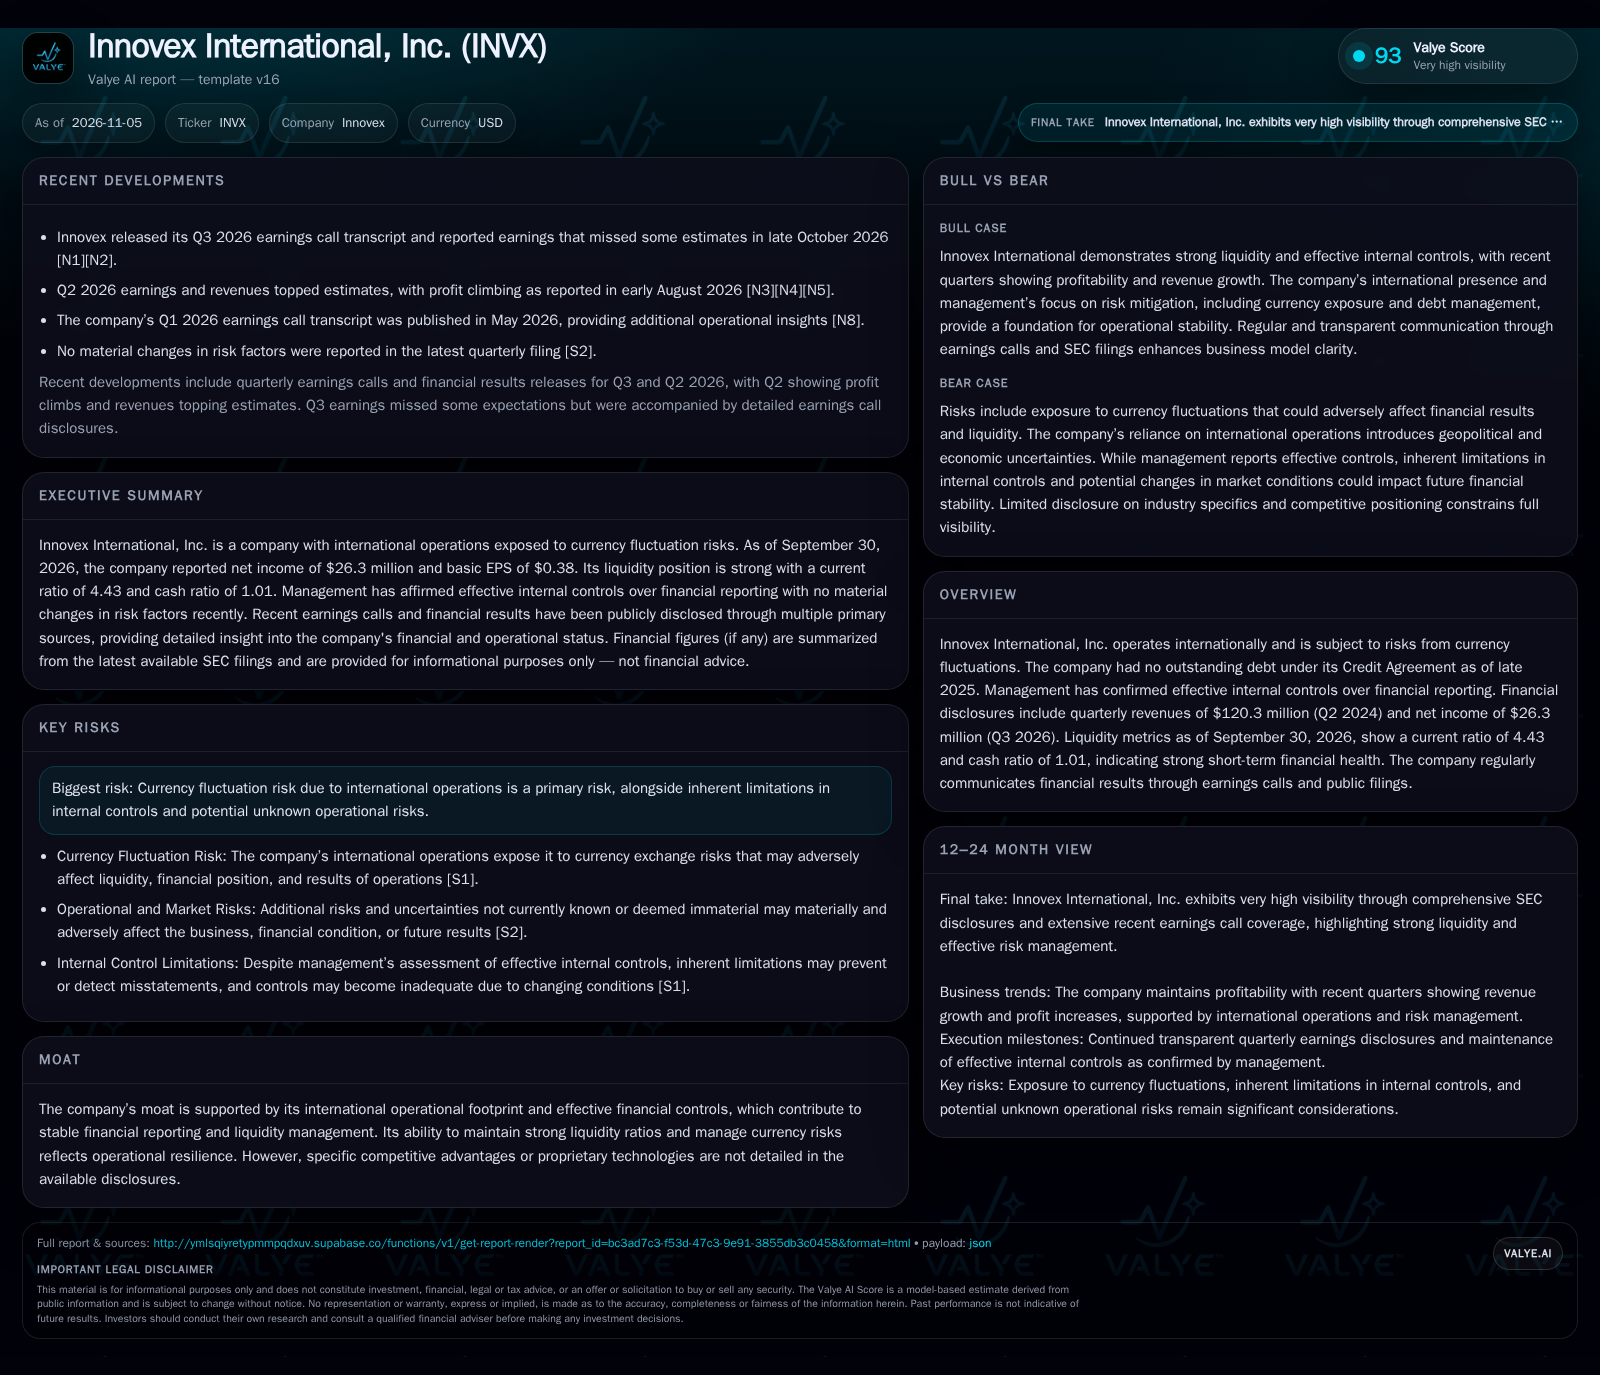
Innovex International stands out for its reported liquidity position, zero debt, and continued profitability as of Q3 2026. The company’s international presence offers opportunity but also exposes it to material currency risks, a factor management openly acknowledges. Despite transparent financial reporting and affirmed internal controls, Innovex’s limited public disclosure of its business model, unit economics, and competitive context makes it difficult to assess the durability of its margin profile or the sustainability of recent earnings momentum. Investors are left to weigh strong current metrics against the uncertainty of how—and where—Innovex creates lasting value in a competitive global landscape.
Recent Profitability and Financial Strength Define the Operating Backdrop
Innovex International reported net income of $26.3 million for the quarter ended September 30, 2026, with basic earnings per share of $0.38. The company’s balance sheet as of that date showed cash and equivalents of $185.6 million, current assets of $815.0 million, and current liabilities of $184.1 million, resulting in a current ratio of 4.43 and a cash ratio of 1.01. Notably, there was no debt outstanding under its Credit Agreement at year-end 2025. However, the company’s international exposure brings persistent currency risks that can impact both reported results and the real purchasing power of cash flows. [S1] [S2]
However, this conservative stance might also indicate limited aggressive investment in growth initiatives or innovation, which could impact the company's ability to capitalize on emerging market opportunities. Furthermore, persistent currency risks inherent in international operations necessitate robust hedging strategies or natural offsets in revenue and costs to protect margins. The effectiveness of such risk management practices would critically influence reported earnings volatility and the real economic value generated across different currency zones.
What We Know—and Don’t—About Innovex’s Core Economics
While Innovex discloses headline revenue ($120.3 million for Q2 2024) and net income, the specific commercial mechanics—such as the nature of its revenue streams, pricing models, or the mix of recurring versus transactional revenue—are not detailed in the available filings. The international scope suggests exposure to multiple end-markets and possibly diverse product or service lines, each with distinct margin profiles and capital requirements. High liquidity and zero debt indicate a conservative capital structure, but without detail on working capital cycles, gross margins, or customer concentration, it is unclear if recent profitability is sustainable or driven by one-off factors.
In the absence of explicit product or service details, several scenarios are plausible. Innovex could operate in a capital-light, service-oriented segment with moderate fixed costs, enabling operating leverage as revenue scales. Alternatively, if the business is more asset-intensive or exposed to commodity pricing, earnings could be volatile and margins thin. The current reported liquidity position may reflect prudent cash management but could also signal underinvestment or a lack of attractive reinvestment opportunities. Currency fluctuations further complicate margin visibility, as even stable local operations may see significant swings in reported USD results.
Understanding the capital intensity and working capital dynamics of Innovex’s operations would be crucial to assessing the sustainability of its profitability. For instance, a business with long receivables cycles or inventory build-up may face liquidity strains despite apparent cash reserves. Additionally, the mix between recurring and transactional revenues can significantly affect revenue predictability and valuation multiples. If Innovex operates with a high proportion of recurring revenue, it may benefit from more stable cash flows and customer relationships, enhancing its resilience against market fluctuations. Conversely, a predominance of transactional sales could expose the company to demand cyclicality and competitive pricing pressures.
Competitive Differentiation Remains Opaque Amid International Risks
Innovex’s filings do not specify its industry, product set, or direct competitors, making it difficult to pinpoint its competitive position or the durability of its business model. The international footprint and effective internal controls may provide some resilience, but without evidence of proprietary technology, network effects, or regulatory barriers, the company’s moat appears limited to operational discipline and risk management. In global markets, this leaves Innovex vulnerable to pricing pressure from larger incumbents, low-cost entrants, or disruptive substitutes, particularly if its offerings are commoditized.
Currency exposure, while managed, can also erode competitive advantage if Innovex cannot pass cost swings through to customers or if local competitors with native currency cost bases undercut pricing. Without explicit disclosure of recurring revenue, long-term contracts, or customer retention metrics, it is not possible to assess the company's pricing power or revenue durability. The lack of detail on market share or customer mix further complicates assessment of the company’s ability to defend margins or grow profitably in the face of shifting global demand.
The absence of clear competitive moats raises questions about Innovex’s ability to sustain pricing power and margin stability in a potentially commoditized market. Operational discipline and internal controls, while valuable, may not suffice to fend off competitors with superior scale, technology, or cost structures. Moreover, geographic diversification can be a double-edged sword: while it spreads risk, it also requires managing heterogeneous regulatory environments, customer preferences, and competitive landscapes. The company’s capacity to tailor offerings and leverage local market insights could be a critical determinant of competitive success, especially if global competitors are less agile or face higher operational complexity.
Visibility Improves and Margin Expansion Drives Sustainable Value
The most favorable scenario for Innovex would see the company clarify its business model, demonstrating a portfolio of high-margin, recurring-revenue offerings and resilient customer relationships across diverse international markets. If future disclosures reveal that recent profitability is underpinned by operating leverage, differentiated solutions, and strong retention—rather than one-off cost control—investors could gain confidence in the durability of earnings.
Upside would be confirmed by the emergence of explicit customer wins, multi-year contracts, or recurring revenue metrics, alongside stable or improving gross and operating margins even as currency headwinds persist. Evidence of new product launches, geographic expansion with limited incremental capital, or pricing power would further support the case. A falsification would be new disclosures showing high customer churn, margin compression, or dependence on non-repeat business.
Sustained Profitability Amid Operational Uncertainty
Revenue and earnings may fluctuate quarter-to-quarter due to currency swings and variable demand across geographies, but the absence of debt and effective internal controls provide ballast against major shocks. In this scenario, Innovex’s performance tracks broader macro trends and FX movements, with no clear evidence of either outsized competitive advantage or structural vulnerability.
If, however, future filings reveal rising costs, deteriorating margins, or new operational risks not previously disclosed, the base case could shift toward downside.
Currency Volatility and Margin Pressure Erode Earnings Quality
A negative scenario would see Innovex’s international exposure become a liability, with adverse currency movements directly reducing USD-reported revenues and profits. If the company is unable to offset FX risk through price adjustments or hedging, and if local competitors gain share, Innovex could see margin compression and shrinking net income.
Downside would be confirmed by a string of earnings misses, declining net income, or a sharp drop in liquidity metrics. New risk disclosures or evidence of customer attrition, contract losses, or rising bad debt expense would also signal a deteriorating outlook.
Testing the Innovex Thesis: What to Track in the Next Four Quarters
Quarterly revenue growth and net income progression, especially in the context of currency-adjusted performance and margin trends. [S2]
Any new disclosures of segment-level financials, product lines, or geographic revenue mix that clarify the company’s true economic drivers.
Gross and operating margin trends over time, which would illuminate pricing power and cost control in the face of FX volatility.
Customer concentration and retention metrics, if disclosed, to assess revenue durability and competitive stickiness.
Updates on risk factors in SEC filings—new operational, market, or compliance risks could signal emerging headwinds.
Disclosure of any new debt, major capital expenditures, or shifts in capital allocation policy that might alter the risk profile.
Explicit commentary on competitive landscape, proprietary capabilities, or strategic partnerships in future earnings calls or filings.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments