
Jaguar Health’s Licensing Moves and Financial Pressures Shape Its GI Biopharma Outlook
Jaguar Health’s recent U.S. licensing deal and ongoing clinical pipeline efforts are set against a backdrop of persistent operating losses, dilution, and urgent capital needs. The company’s focus on niche gastrointestinal indications in both human and animal health offers targeted opportunity, but execution risk remains high as dependency on partners and the need for new funding intensify.
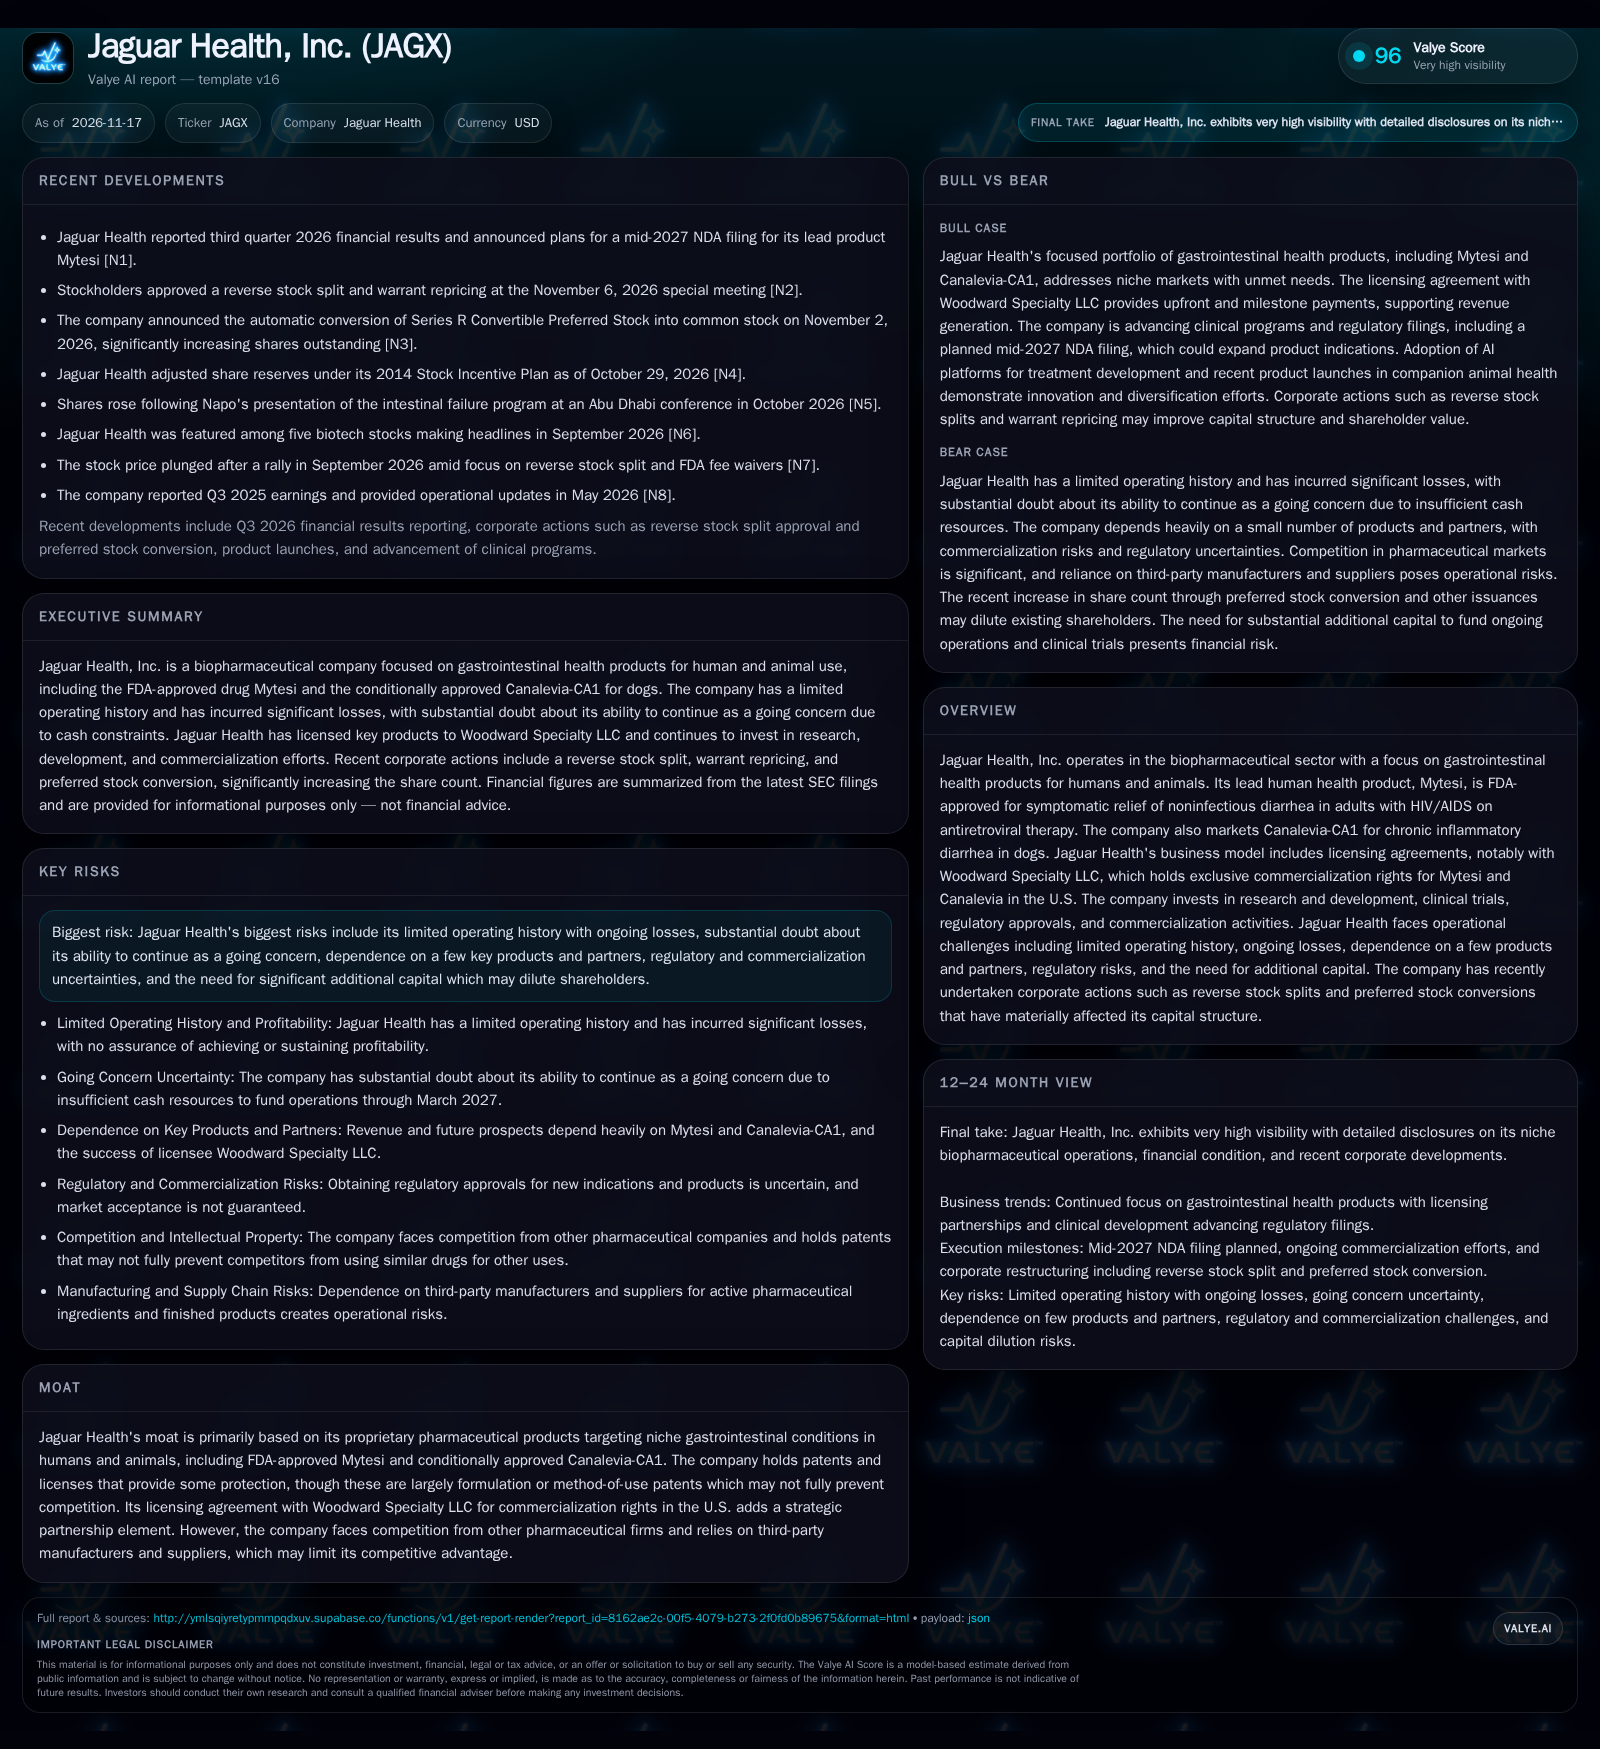
Jaguar Health has licensed its core GI health products, Mytesi and Canalevia-CA1, to Woodward Specialty LLC for U.S. commercialization, aiming to secure upfront and milestone payments. Despite this, the company continues to post significant losses and faces substantial doubt about its ability to continue as a going concern. A planned mid-2027 NDA filing for its lead product could be a catalyst, but ongoing capital requirements and dilution risks weigh heavily on the outlook. Execution on clinical, regulatory, and partnership milestones is critical to any recovery or upside from current levels. [S2] [N1] [N3]
Jaguar Health, Inc. stands at a pivotal moment, leveraging licensing deals and a targeted GI health focus to offset persistent financial strain and operational uncertainty. The company’s exclusive U.S. licensing agreement for its core products, Mytesi and Canalevia-CA1, aims to generate non-dilutive capital and shift commercialization risk to its partner. Yet, with mounting losses, a history of dilution, and an explicit going concern warning, the business faces a narrow runway. The next 12-18 months will test whether new clinical filings and partnership execution can stabilize the company or if capital constraints will overwhelm its ambitions. [S2] [N1] [N3]
Licensing Deals and Cash Flow Challenges Redefine Jaguar Health’s Current Position
Jaguar Health’s most material recent development is its January 2026 licensing agreement granting Woodward Specialty LLC exclusive U.S. commercialization rights for Mytesi and Canalevia-CA1, with Jaguar receiving upfront and potential milestone payments. This move is designed to offload commercial execution risk, secure non-dilutive capital, and potentially stabilize revenue streams. However, the company reported a net comprehensive loss of $54.4 million in 2025, with Q3 2026 revenue at $2.343 million and EPS at -$9.23, underscoring ongoing operating challenges. As of September 30, 2026, cash stood at $5.53 million, with a current ratio of 1.28 and a cash ratio of 0.43. Critically, management has stated there is substantial doubt about the company’s ability to continue as a going concern through March 2027, highlighting urgent capital needs. The automatic conversion of Series R Preferred Stock into common stock in November 2026 materially increased share count to 13.3 million, diluting existing holders and reflecting the company’s reliance on equity-based funding to navigate liquidity shortfalls. [S2] [N1] [N3]
The Financial Framework Behind Jaguar Health’s Licensing and Pipeline Milestones
Jaguar Health’s core revenue model is a mix of direct product sales and licensing, with the recent Woodward Specialty LLC deal providing a pathway to upfront and milestone payments. In principle, such arrangements can reduce fixed commercial overhead and improve cash flow visibility—if milestones are met and partners execute. However, the company’s revenue base remains modest, and the bulk of value creation is likely tied to future milestones and royalties, which depend on Woodward’s commercial performance and market uptake. The company’s operating leverage remains negative: R&D and SG&A costs outstrip gross profit, and the fixed costs of ongoing clinical development (including a planned mid-2027 NDA filing) demand substantial new capital. The capital structure has been heavily diluted via preferred stock conversion and reverse splits, with additional funding needs likely to result in further dilution or expensive financing. Manufacturing is outsourced, so gross margins may be structurally constrained, and dependency on third parties introduces supply chain and cost risks. Without a step-change in product uptake or a major pipeline success, Jaguar’s business economics are trapped in a cycle of negative cash flow and recurring capital raises.
Jaguar Health’s Targeted GI Market Position and Strategic Collaborations
Jaguar Health targets niche gastrointestinal indications in both human and animal health, relying on proprietary formulations such as Crofelemer (Mytesi) and Canalevia-CA1. The company’s competitive position is partially protected by FDA approval and method-of-use patents, but these barriers are modest relative to the broader pharmaceutical landscape, where larger incumbents and generics can quickly erode pricing and share in attractive markets. The company’s licensing strategy, especially the Woodward Specialty LLC deal, is a key defensive move—outsourcing commercialization to a partner with potentially greater reach and resources. However, this also means Jaguar is now more dependent on its partner’s execution and less able to directly influence sales outcomes. In animal health, Canalevia-CA1 faces competition from established veterinary pharmaceutical companies and over-the-counter products. The risk of substitution is significant if competitors launch alternative therapies or if payers resist reimbursement for niche indications. The planned adoption of AI platforms for Crofelemer development could provide a technical edge but is unlikely to be a near-term differentiator without clear evidence of improved trial efficiency or clinical outcomes.
Potential Gains from NDA Approval and Effective Commercial Rollout
The most favorable scenario for Jaguar Health involves a successful mid-2027 NDA filing and subsequent approval for its intestinal failure program, which could expand the addressable market for Crofelemer and establish a second major revenue stream. If Woodward Specialty LLC executes effectively, achieving key milestones and ramping sales of Mytesi and Canalevia-CA1, Jaguar could realize significant milestone and royalty payments, easing its capital constraints and reducing dilution risk. Evidence that would confirm this scenario includes: (1) timely NDA submission and acceptance by the FDA; (2) public disclosure of received milestone payments; (3) a material increase in reported royalty revenue; and (4) positive updates on U.S. sales trends from Woodward. If Jaguar is able to supplement this with successful clinical data or new licensing deals in animal health or ex-U.S. markets, the company’s risk profile would improve materially. The question is whether these catalysts can occur before liquidity pressures force another dilutive raise or operational retrenchment.
Expected Developments: Steady Pipeline Advances Amid Funding Challenges
The most plausible path for Jaguar Health is one of incremental pipeline progress and continued efforts to extract value from existing assets, but with ongoing capital constraints and repeated shareholder dilution. The company may advance its NDA filing on schedule and see modest revenue from licensing, but milestone and royalty receipts are likely to be back-weighted or uncertain, given dependence on Woodward’s commercial execution. Expenses for R&D, regulatory, and G&A are expected to outpace revenue, necessitating new capital raises—likely at unfavorable terms given the company’s going concern warning and history of losses. Confirmation of this scenario would include further equity offerings or financing events, continued negative EPS and cash burn, and only gradual improvement in reported revenue or pipeline milestones. A base case does not assume a step-change in product adoption or a near-term commercial breakthrough.
Risks from Funding Shortfalls and Partner Performance Issues
The downside scenario centers on Jaguar Health exhausting its limited cash before any major milestone or commercial inflection, resulting in forced asset sales, severe dilution, or potential insolvency. If Woodward Specialty LLC fails to generate meaningful sales or misses milestones, Jaguar could see little to no royalty or milestone income, leaving it wholly reliant on external capital. Regulatory setbacks—such as delays or rejections of the planned NDA—would further erode value and could undermine any remaining investor confidence. Negative evidence would include missed clinical or regulatory timelines, further going concern warnings, inability to complete a needed financing, or signs that partners are deprioritizing Jaguar’s products. In this scenario, value for current shareholders could be heavily impaired or wiped out.
Critical Milestones Influencing Jaguar Health’s Future Direction
Progress and timing of the planned mid-2027 NDA filing for the intestinal failure program. Delays or regulatory feedback would materially affect sentiment and timelines.
Disclosure of milestone and royalty payments from Woodward Specialty LLC, and whether these are sufficient to offset cash burn.
Updates on U.S. sales performance for Mytesi and Canalevia-CA1 under Woodward’s stewardship, if disclosed.
Jaguar’s quarterly cash burn rate and any changes to its stated going concern outlook.
Announced financing events, including terms and dilution impact, as a proxy for capital market access and balance sheet durability.
Clinical and regulatory progress for pipeline products (e.g., NP-300, Gelclair), including trial initiations, data, or filings.
Adoption or efficacy data for AI-enabled drug development or new companion animal products, if disclosed.
Any changes in partner relationships, such as expanded licensing, renegotiation, or evidence of deprioritization by Woodward.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments