
Johnson & Johnson: Innovation Momentum Meets Legal and Regulatory Crosscurrents
Johnson & Johnson’s recent product launches and raised sales outlook suggest ongoing innovation traction, but persistent legal and regulatory headwinds, modest quarterly earnings, and exposure to global market volatility complicate the forward view.
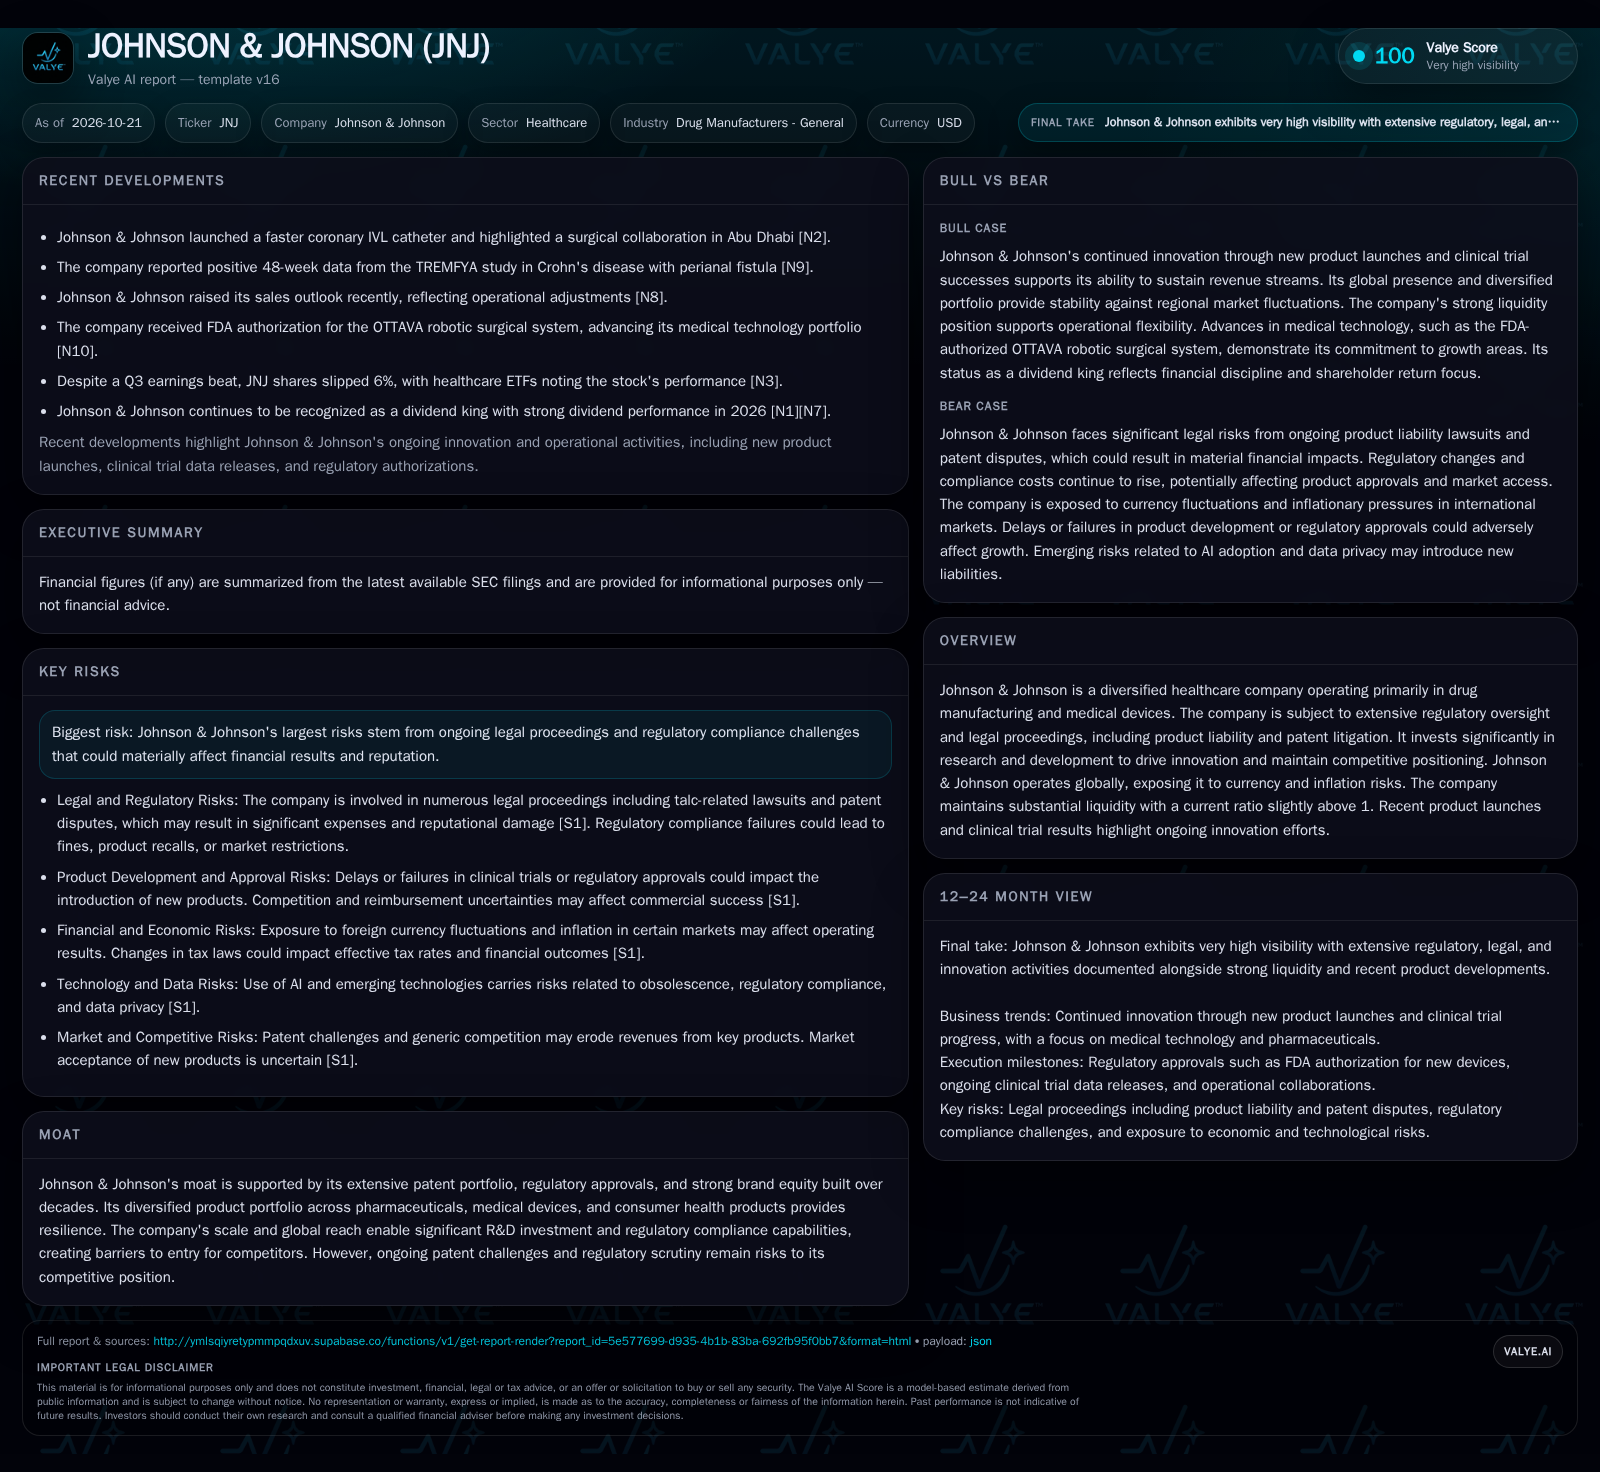
Johnson & Johnson has recently raised its sales outlook and posted positive clinical results in immunology, reflecting continued innovation and operational resilience. However, material legal proceedings, modest Q3 net income, and global market exposures are key factors shaping the risk-reward profile. The durability of new product contributions and the outcome of major legal liabilities remain central to the investment case. [S2] [N8]
Johnson & Johnson stands at a pivotal juncture where its innovation engine—evidenced by a raised sales outlook and new product launches—must contend with persistent legal, regulatory, and global market challenges. With a significant share of future sales riding on recently developed pharmaceuticals and devices, the company’s ability to translate R&D productivity into sustainable profit growth is under scrutiny. Meanwhile, legal liabilities and modest recent earnings underscore the need for operational discipline and careful management of external risks.
Recent Sales Outlook Upgrade and R&D Milestones Reshape the Narrative
Johnson & Johnson has raised its sales outlook, indicating operational momentum and confidence in near-term business trends. This adjustment comes alongside positive clinical data from the TREMFYA study in Crohn’s disease and new product launches in medical devices, such as a faster coronary IVL catheter. These developments suggest that innovation remains a central growth lever, with approximately 25% of 2025 sales expected to come from products launched in recent years. However, Q3 2026 net income was a modest $210 million, and shares declined 6% despite an earnings beat, reflecting market skepticism around near-term profitability and risk. [S2] [N8] [N3]
The interplay between innovation momentum and legal/regulatory challenges creates a nuanced operational environment for Johnson & Johnson. While new product launches drive optimism, the timing and scale of their market adoption remain critical variables. The company must navigate not only the inherent uncertainties of clinical trial outcomes and regulatory approvals but also the competitive landscape that may influence pricing power and reimbursement levels. Furthermore, the global macroeconomic context—including supply chain constraints and geopolitical tensions—can affect manufacturing costs and market access, thereby influencing the realization of forecasted sales growth from recent innovations.
How J&J’s Diversification and Product Mix Drive Economic Outcomes
Johnson & Johnson’s business model hinges on a diversified portfolio spanning pharmaceuticals, medical devices, and consumer health. This structure provides resilience against single-product shocks and regional volatility, but also introduces complexity in managing R&D allocation and regulatory compliance across therapeutic areas. The company’s ability to generate outsized returns depends on successfully bringing new, high-margin drugs and devices to market—especially as patent cliffs and generic competition erode mature product lines.
The economics of J&J’s pharmaceuticals segment are characterized by high upfront R&D and regulatory costs, offset by potentially strong operating leverage if new drugs achieve blockbuster status. Medical devices offer steadier, but often lower-margin, revenue streams with recurring consumables and service opportunities. The capital intensity of R&D and legal expenses—particularly from ongoing litigation—raises the bar for incremental returns, making the conversion of innovation into profitable sales a central challenge. With a current ratio near 1, the company’s reported liquidity position but not excessive, underscoring the importance of disciplined capital allocation and cost management. [S2]
A key economic consideration is how Johnson & Johnson balances investment across its diversified portfolio to maximize returns. Allocating capital effectively between pharmaceuticals, devices, and consumer health requires assessing the marginal benefit of R&D spend in each segment, especially as some areas may offer faster payback or lower regulatory risk. Additionally, the company’s capacity to leverage scale in manufacturing and distribution can create cost advantages, but only if innovation leads to sufficient volume growth. The impact of legal expenses on cash flow and earnings volatility also complicates capital planning, making scenario-based financial modeling essential to maintain operational flexibility while pursuing growth opportunities.
Scale, Pipeline Breadth, and Regulatory Savvy: J&J’s Defenses and Vulnerabilities
Johnson & Johnson’s competitive position is anchored by its scale, global reach, and ability to invest heavily in R&D, regulatory infrastructure, and compliance. This creates barriers to entry that smaller or single-line peers may struggle to match. The breadth of its product portfolio allows J&J to weather setbacks in individual franchises and respond to shifting market dynamics.
However, these advantages are countered by persistent patent challenges, ongoing product liability lawsuits, and the risk of regulatory tightening—especially in high-profile areas such as AI-driven healthcare, data privacy, and drug pricing. In pharmaceuticals, competition from generics and biosimilars is relentless once exclusivity expires. In devices, the company faces both established multinationals and nimble medtech disruptors. J&J’s ability to defend its intellectual property, maintain regulatory compliance, and sustain R&D productivity will determine whether it can preserve premium margins and market share.
Johnson & Johnson’s scale and regulatory expertise provide a buffer against competitive threats, yet agility in responding to emerging industry trends is equally important. For example, the rise of digital therapeutics and AI-enabled diagnostics introduces both opportunities and regulatory complexities that require adaptive strategies. The company’s ability to integrate digital innovation within existing product lines or develop new offerings could be a differentiator, but this depends on navigating evolving data privacy regulations and securing stakeholder trust. Moreover, sustaining a robust patent portfolio and defending intellectual property rights will be increasingly critical as biosimilars and generic entrants intensify competition in established therapeutic areas.
When Pipeline Conversion and Legal Resolutions Unlock Value
A favorable scenario for Johnson & Johnson would see sustained clinical and regulatory success in its late-stage pipeline, translating into multiple high-growth product launches across pharmaceuticals and devices. If positive TREMFYA data leads to expanded Crohn’s disease indications and accelerated uptake, and if new medical device launches gain rapid market traction, the company could see a step-change in revenue mix toward higher-margin, patent-protected assets. This would reinforce the company’s ability to absorb legal costs while expanding operating leverage.
Legal headwinds could also abate if major product liability cases (such as talc litigation) are resolved within currently reserved amounts, reducing uncertainty and freeing capital for reinvestment or shareholder returns. Confirmation of this scenario would require evidence of accelerating new product sales (especially those launched since 2023), a clear decline in legal reserves or settlement outflows, and margin expansion in quarterly results.
Innovation Offsets Headwinds, but Margin Expansion Remains Elusive
The most plausible near-term trajectory is that Johnson & Johnson continues to generate moderate growth through ongoing innovation—supported by recent product launches and positive clinical results—while legal, regulatory, and global economic headwinds persist. The company is likely to see a gradual shift in revenue mix toward newer products, but ongoing litigation expenses and pricing pressures may cap margin expansion.
In this scenario, J&J maintains its investment grade profile and operational flexibility, but significant EPS growth remains challenging unless legal liabilities are resolved more favorably or new product launches outperform expectations. Evidence for this base case would include stable or slightly rising sales, a continued but measured pace of product introductions, and legal expenses remaining a consistent drag on profitability.
Legal Escalation and Global Shocks Erode Stability
The adverse scenario would be triggered by an unfavorable escalation in legal liabilities—such as unexpected adverse judgments in talc or patent cases—or regulatory setbacks that delay or block key product launches. In this case, J&J could face substantial cash outflows, forced asset sales, or constraints on capital allocation, putting dividends and R&D investment at risk.
External shocks such as accelerated currency devaluation in key international markets or inflation-driven cost spikes could further compress margins, especially if new product launches fail to offset lost revenue from maturing franchises. Confirmation of this downside would come from large upward revisions in legal reserves, significant product delays or recalls, or a sharp deterioration in operating margins and free cash flow.
What Will Validate J&J’s Innovation-Led Resilience or Expose Its Legal Risks?
Progression and commercial impact of new product launches, particularly those contributing to the 25% of sales projected for 2025—if disclosed, quarterly revenue breakdown by launch cohort would clarify momentum.
Legal settlement amounts and changes in litigation reserves related to talc and patent disputes—any material revisions would signal risk or relief.
Gross and operating margin trends in the context of innovation-driven sales versus legal and compliance costs.
International sales performance and currency impact, given 43% of revenue is generated outside the U.S.—management commentary on hedging or pricing adjustments would be informative.
R&D expense as a percentage of sales and pipeline productivity metrics (e.g., late-stage trial progression, regulatory approvals).
Updates on AI, data privacy, and regulatory compliance costs—especially as J&J scales digital health initiatives.
Cash flow from operations and capital allocation priorities, particularly in the context of ongoing legal and R&D commitments.
Evidence of market share shifts in core therapeutic or device categories in response to competitor launches or pricing moves.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments