
JPMorgan Chase in Late 2026: Diversification, Regulatory Complexity, and the Shifting Sands of Banking Profitability
With $4.4 trillion in assets and a footprint spanning consumer, corporate, and wealth management, JPMorgan Chase faces a landscape shaped by regulatory rigor, technology adoption, and intensifying competition. Recent expansion into Dubai’s wealth market and diverging revenue trends versus peers underscore both opportunity and complexity as macro, credit, and compliance risks loom.
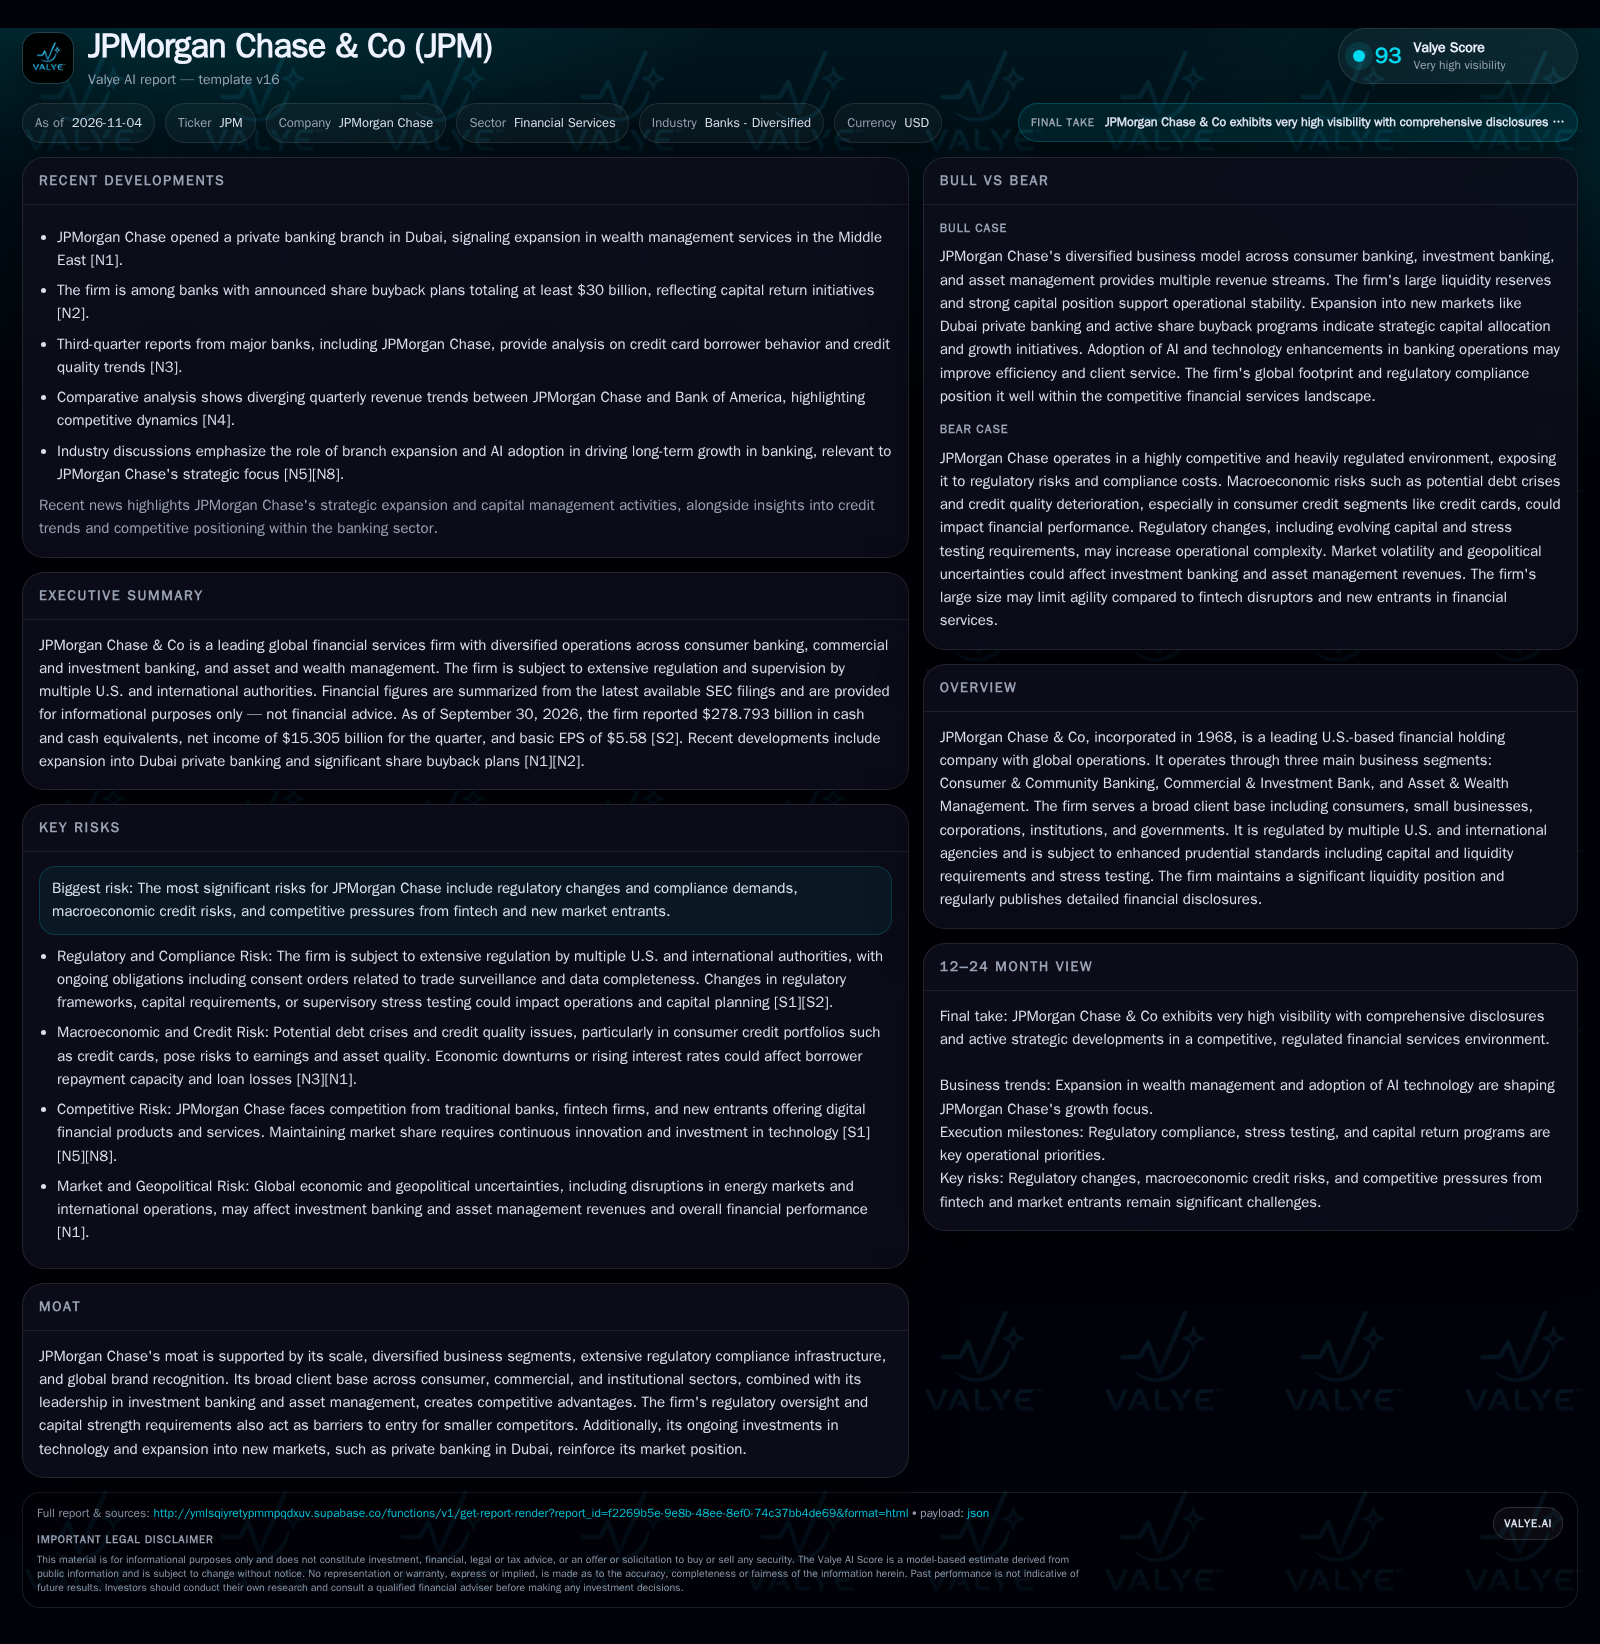
JPMorgan Chase remains a dominant, diversified force in global banking, with $4.4 trillion in assets and robust quarterly earnings. Recent moves—like private banking expansion in Dubai—highlight a strategic push into new markets, even as diverging revenue trends versus major peers and ongoing regulatory scrutiny frame a complex outlook. The interplay between scale-driven advantages, evolving credit quality, and disruptive fintech competition will be decisive in the coming years. [S1] [S2] [N1] [N4]
JPMorgan Chase’s scale, diversification, and global reach anchor its status as a pivotal player in the financial sector. Reporting $15.3 billion in net income for Q3 2026 and holding $4.4 trillion in assets, the bank’s operational model spans retail, corporate, and wealth management. Recent expansion into Dubai’s private banking scene signals intent to deepen international wealth revenue streams. Yet, as revenue trends diverge from major peers and regulatory oversight intensifies, the firm faces an environment where technology adoption, credit quality vigilance, and competitive dynamics could reshape profitability and strategic flexibility. [S1] [S2] [N1] [N4]
Recent Expansion and Performance Markers Signal Strategic Priorities
As of September 30, 2026, JPMorgan Chase reported $4.4 trillion in assets and $362.4 billion in stockholders' equity, underscoring its position as the largest U.S. bank by assets. Net income for the third quarter reached $15.305 billion, with basic earnings per share of $5.58. These results reflect continued operational resilience and scale, even as the broader banking sector faces margin and growth pressures. [S1] [S2]
Strategically, the firm has expanded its private banking presence with a new branch in Dubai, targeting growth in international wealth management and signaling confidence in the Middle East’s affluent client base. This move may help diversify revenue and reduce reliance on U.S.-centric income streams. [N1]
Meanwhile, recent comparative reports highlight diverging quarterly revenue trends between JPMorgan Chase and Bank of America, suggesting competitive positioning and business mix are actively shaping performance outcomes. [N4]
How JPMorgan Chase Generates Profits Across Its Diversified Platform
JPMorgan Chase’s business model leverages three core segments: Consumer & Community Banking (CCB), Commercial & Investment Bank (CIB), and Asset & Wealth Management (AWM). Each segment operates with distinct revenue drivers and cost structures. In CCB, net interest income from deposits and lending forms the backbone, with credit cards and retail banking providing substantial fee and interest streams. The CIB segment depends on trading, investment banking, and treasury services; these lines tend to be cyclical but offer high returns on equity in favorable markets. AWM generates recurring management fees, bolstered by scale and cross-selling to existing clients. [S1]
Scale enables significant fixed-cost absorption, particularly in technology, compliance, and branch infrastructure. However, variable costs—including credit losses and compensation—remain sensitive to economic cycles and risk appetite. Operating leverage can be positive in periods of rising rates and loan growth, but margin compression can arise if deposit betas increase or credit quality erodes.
Capital and funding needs are dictated by regulatory requirements, with enhanced prudential standards mandating high levels of liquidity and capital buffers. This creates resilience but can constrain return on equity relative to less regulated or more nimble competitors. The economics of new initiatives, such as the Dubai private banking branch, will hinge on local client acquisition costs, fee rates, and the ability to leverage global platforms for efficiency.
Scale, Brand, and Technology: Barriers and Threats in a Crowded Market
JPMorgan Chase’s competitive advantages stem from its massive scale, global brand recognition, and diversified business mix, which collectively provide resilience against shocks and enable cross-segment synergies. Its regulatory infrastructure and capital strength pose significant barriers for new entrants, especially in areas like wholesale banking and cross-border asset management. [S1]
However, the competitive landscape is mutating. Traditional peers (large U.S. and global banks) remain formidable, but fintech firms, digital banks, and specialized wealth managers are attacking high-margin niches—particularly in payments, lending, and advisory. These disruptors often operate with lighter regulatory burdens and can iterate products more quickly.
Technology adoption is a double-edged sword: while JPMorgan’s investment in AI and digital channels may enhance efficiency and client experience, it also raises the stakes for continued innovation. The question is whether scale and legacy IT systems will be a drag or an enabler as the industry digitizes further. Meanwhile, the Dubai expansion puts the firm in direct competition with established European and regional private banks, where local relationships and regulatory nuances matter.
Unlocking Global Wealth and Digital Efficiencies Could Drive Outperformance
The most favorable scenario for JPMorgan Chase is one where international wealth management expansion—such as the Dubai branch—proves highly accretive, capturing affluent clients seeking global platforms and sophisticated advisory. If client inflows in new markets outpace expectations and cross-selling opportunities materialize, AWM fee revenue could accelerate, providing a stable, high-margin growth engine.
Simultaneously, successful AI and automation adoption across retail and institutional channels could drive down marginal costs, improve risk analytics, and reduce credit losses, enhancing profitability. If U.S. consumer credit quality remains robust and rate environments support net interest margins, the core retail bank may continue to deliver outsized returns.
Confirmation of this scenario would come from disclosure of above-peer AWM inflows, improving efficiency ratios, and evidence of market share gains in both domestic and international wealth segments. Conversely, sluggish client growth in new markets or failure to translate technology investments into margin expansion would challenge the upside thesis.
Diversified Model Sustains Returns Amid Mixed Growth and Margin Headwinds
The most plausible outcome is that JPMorgan Chase’s diversified business model continues to deliver stable, if unspectacular, returns. Retail banking performance is likely to be moderated by consumer credit normalization and margin pressures as deposit costs rise, even as loan growth remains steady. CIB revenues could fluctuate with market conditions and capital markets activity, while AWM grows incrementally through organic and targeted international expansion.
Technology investments may incrementally improve efficiency, but legacy systems and compliance costs will absorb some gains. The firm’s scale and client breadth support stability, but growth rates may lag more nimble or tech-focused peers.
Evidence supporting this scenario would include sustained profitability, stable efficiency ratios, and maintenance of top-tier market position in core segments. A shift away from this base case would be signaled by rapid shifts in credit quality, unexpected regulatory actions, or material underperformance in newly targeted growth markets.
Credit Deterioration or Regulatory Shocks Could Undermine Profitability
A negative scenario would unfold if macroeconomic weakness or shocks lead to significant credit deterioration, particularly in consumer lending and credit cards—a segment identified as a watchpoint. Rising charge-offs could erode net income and force higher loan-loss provisions, while regulatory scrutiny may intensify, potentially resulting in new capital or compliance requirements. [S1]
Simultaneously, if technology-driven competitors accelerate client attrition or compress fees in core franchises, JPMorgan could face margin erosion without offsetting cost reductions. Expansion efforts in new geographies like Dubai may fail to gain traction, leading to sunk costs and strategic distraction.
Downside confirmation would come from rising non-performing loans, deteriorating efficiency ratios, or regulatory enforcement actions resulting in increased capital buffers or operational restrictions. A sharp divergence from peer performance and negative trends in core revenue lines would further validate the risk case.
Testing JPMorgan Chase’s Strategic Flexibility and Resilience in Real Time
Net inflows and client growth in international wealth management, especially in new markets like Dubai, would help gauge the success of expansion efforts (if disclosed).
Quarterly trends in consumer credit quality—delinquency and charge-off rates in credit card and retail portfolios—will be critical for assessing credit risk exposure.
Efficiency ratio movements, especially as technology investments scale, would indicate whether cost initiatives are translating into improved profitability.
Market share in key U.S. retail and global institutional banking segments, relative to both traditional and fintech competitors, would help test competitive positioning.
Regulatory developments, including any new consent orders, capital requirements, or stress test results, could materially impact operational flexibility.
Fee growth and asset levels in Asset & Wealth Management, particularly from new regions, would provide early signals on the effectiveness of global expansion.
Disclosure of AI and digital adoption metrics—such as digital account openings, automated loan approvals, or cost savings from automation—would show whether technology is delivering on promised efficiencies.
Comparative revenue and margin trends versus major peers, especially Bank of America, may signal shifts in competitive dynamics and franchise strength.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments