
Jasper Therapeutics: Clinical Progress, Pipeline Expansion, and the Realities of Biotech Scale-Up
Jasper Therapeutics has pivoted to focus exclusively on mast cell driven diseases, reporting promising early clinical results for its lead antibody briquilimab and expanding its pipeline via the Kira Pharmaceuticals merger.
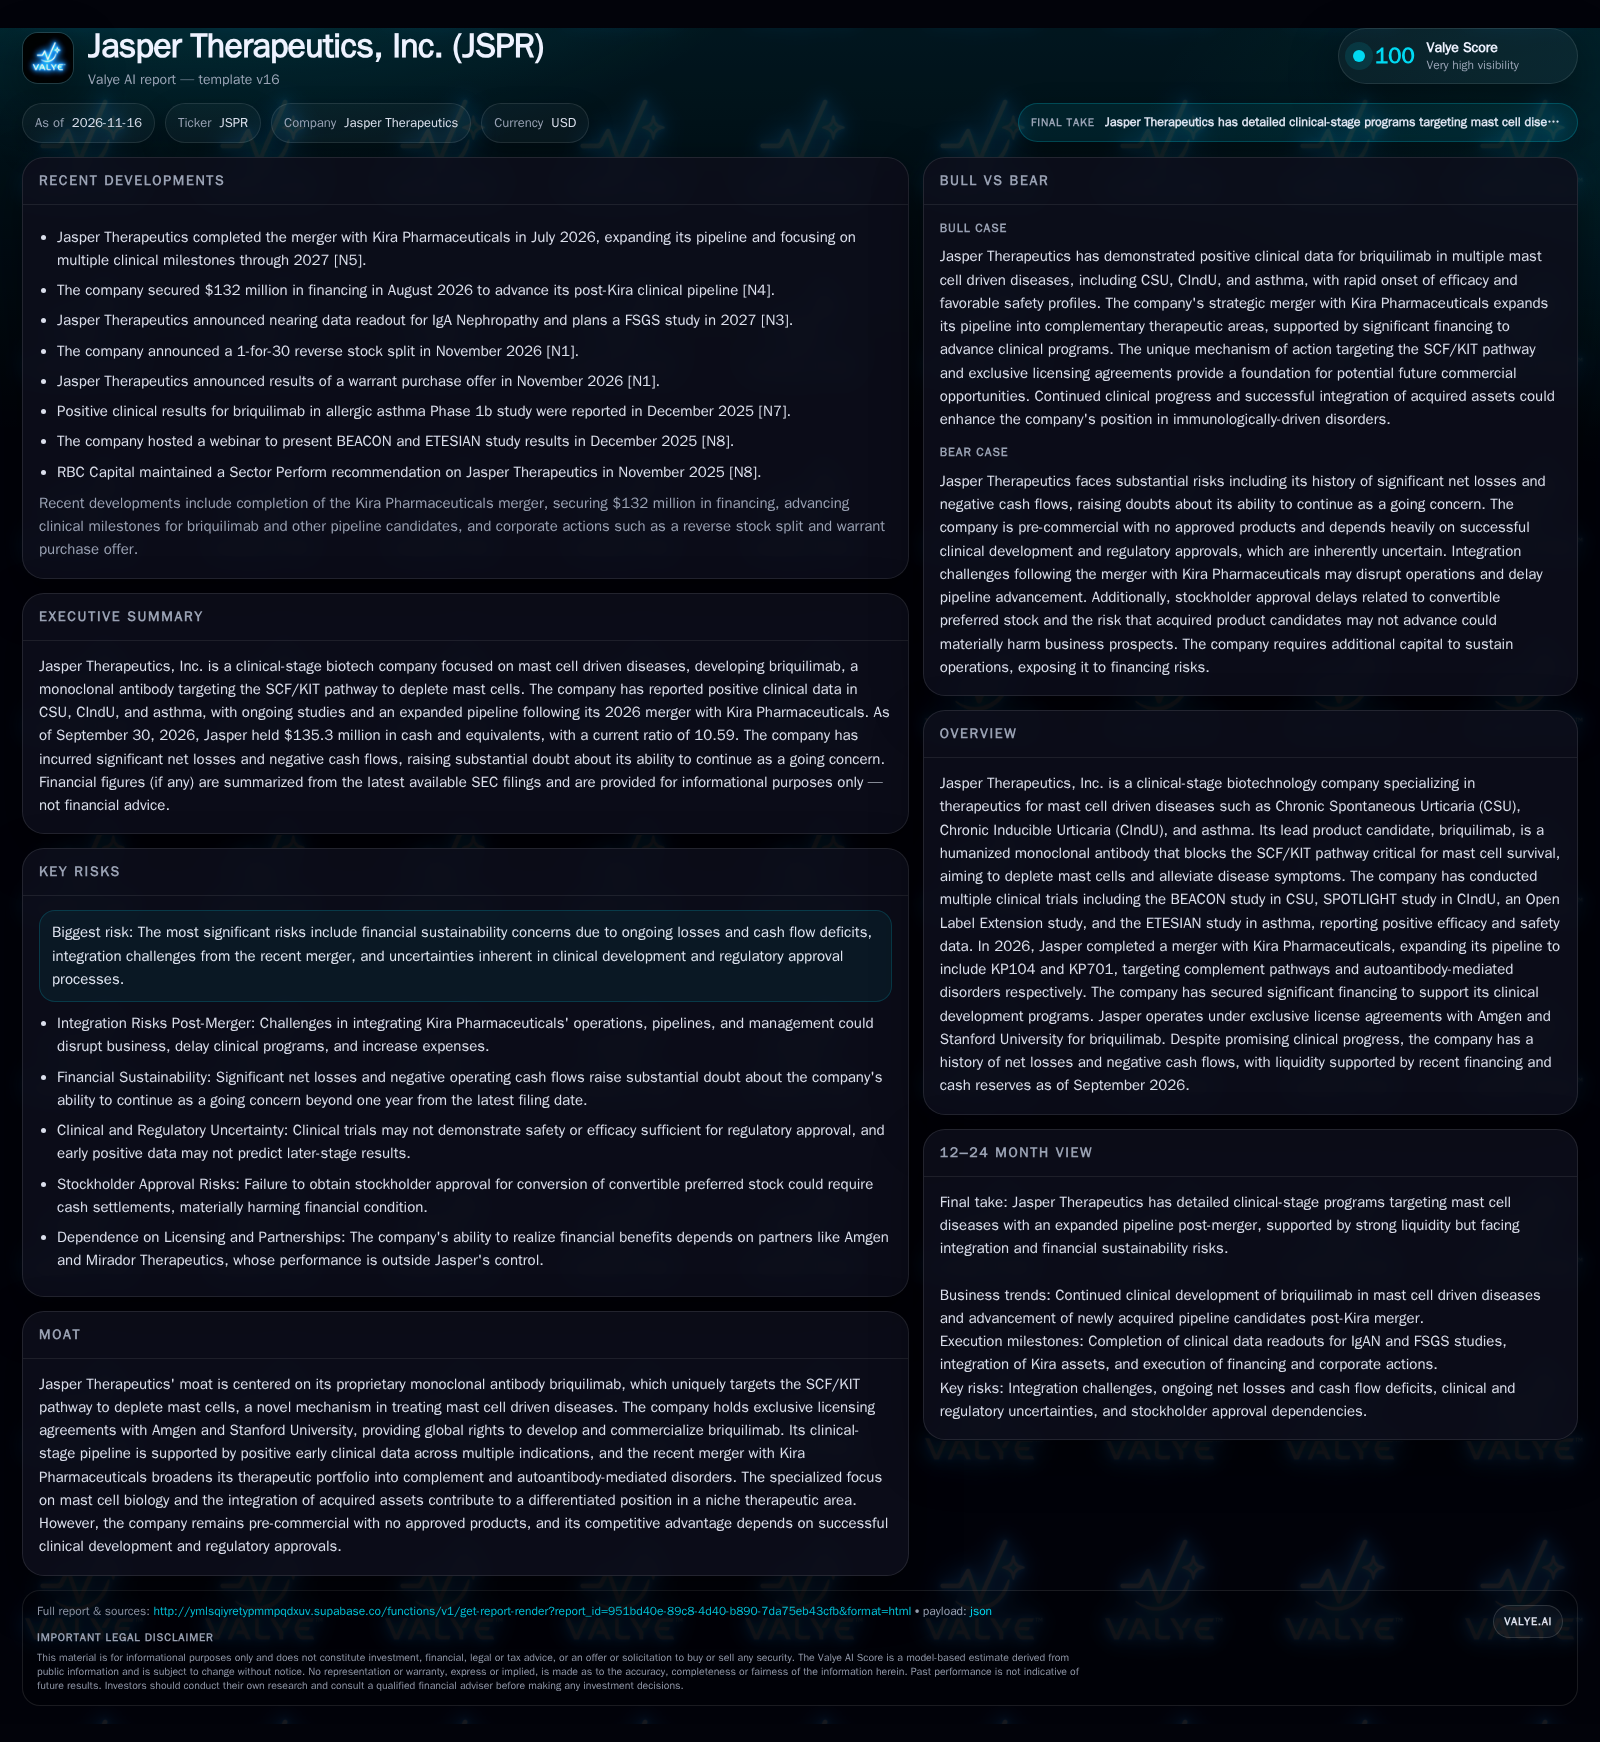
Jasper Therapeutics is a clinical-stage biotech developing therapies for mast cell driven diseases, with positive early data for briquilimab and a broadened pipeline after its 2026 Kira Pharmaceuticals merger.Despite $135M in cash post-financing and reported current ratio, substantial net losses and ongoing negative cash flows raise doubts about its ability to continue as a going concern. The company faces integration, regulatory, and capital-raising risks as it advances multiple programs toward critical 2027 milestones. [S2] [N4] [N5]
Jasper Therapeutics stands at a pivotal moment after pivoting fully to mast cell-driven diseases, reporting compelling early-stage clinical data for briquilimab and broadening its ambitions via the acquisition of Kira Pharmaceuticals. This strategic evolution gives Jasper a more diversified pipeline targeting immunologically driven disorders, but it also magnifies the company’s operational and financial challenges. With $135 million in cash following a major financing and a current ratio over 10, Jasper appears well-resourced in the near term. However, persistent net losses, integration hurdles, and the unpredictability of clinical and regulatory outcomes mean that the next 12–24 months will be critical in determining whether Jasper can convert promise into sustainable value—or become another cautionary tale of biotech scale-up.
Recent Financing and Pipeline Expansion Set the Stage—But Raise the Stakes
Jasper Therapeutics has undergone significant transformation in 2026. The company completed its acquisition of Kira Pharmaceuticals in July, adding KP104 (in Phase 2 for renal and hematologic indications) and KP701 (preclinical, autoantibody-mediated disorders) to its existing focus on mast cell diseases through briquilimab. This broadened scope brings both opportunity and complexity, as Jasper must now integrate new assets, teams, and regulatory pathways. To support these ambitions, the company raised $132 million in August, pushing its cash and equivalents to $135.3 million as of September 30, 2026, and resulting in a current ratio above 10. However, Jasper reported a net loss of $144.5 million for the first nine months of 2026, and its auditors have raised substantial doubt about its ability to continue as a going concern beyond one year from the 10-Q date. The stakes for successful execution have never been higher. [S2] [N4] [N5]
The Economics of a Pre-Revenue Biotech: Cash Burn, Clinical Milestones, and the Funding Treadmill
Jasper’s current business model is typical for clinical-stage biotech: the company invests heavily in R&D, regulatory filings, and organizational build-out while reporting minimal revenue—in this case, $8 million for the first nine months of 2026, likely from licensing or milestone payments rather than product sales. The cost base is dominated by clinical trial expenses, payroll for specialized talent, and costs associated with expanding the pipeline post-Kira merger. Jasper’s negative operating cash flows and cumulative net losses reflect the capital-intensive nature of late-stage clinical development. The $135 million reported cash balance, while significant, is designed to fund multiple ongoing and planned trials through key data readouts in 2027, but it will not support commercial launch or large Phase 3 programs. Biotech economics at this stage are defined by the timing of value-inflection points (such as pivotal data or partnership deals) versus the rate of cash burn. The ability to raise additional capital on acceptable terms, or to secure a lucrative partnership or licensing deal, is often the difference between success and a forced strategic reset.
Can Jasper Carve Out a Defensible Niche in Mast Cell and Complement-Driven Diseases?
Jasper’s competitive position hinges on two axes: scientific differentiation and execution speed. Briquilimab targets the SCF/KIT pathway, aiming to deplete mast cells—a novel approach in diseases like CSU and CIndU, where existing therapies (antihistamines, omalizumab, and other biologics) offer incomplete control for many patients. Jasper’s early clinical data show rapid onset and high rates of complete response at higher doses, suggesting a potential efficacy and convenience edge if results hold in larger trials. However, the market for mast cell-driven diseases is becoming more crowded, with established pharma and other biotech companies exploring new mechanisms (e.g., anti-IgE, anti-Siglec-8, and other mast cell inhibitors). The Kira pipeline brings exposure to complement and autoantibody-mediated disorders, where competition includes large-cap players and next-generation therapies. Jasper’s advantage may lie in first-mover status for certain indications and the breadth of its pipeline, but commercial success will depend on demonstrating clear clinical and health-economic benefits over incumbents and pipeline rivals, as well as navigating payer adoption and pricing dynamics.
What Would It Take for Jasper to Become a Breakout Clinical-Stage Success?
The most favorable scenario for Jasper involves several reinforcing developments: (1) pivotal trials for briquilimab in CSU and CIndU confirm the rapid, durable efficacy and safety observed in early-phase studies, supporting regulatory submissions; (2) KP104 delivers positive Phase 2 data in IgAN or PNH, attracting interest from partners or acquirers; (3) integration of Kira’s team and pipeline proceeds smoothly, and Jasper’s expanded organizational footprint enhances development capabilities; (4) Jasper leverages its clinical data to secure non-dilutive funding or a lucrative licensing deal, reducing dependence on equity markets. Confirmation would require clear, positive top-line data from ongoing and planned studies, external validation (such as major partnership announcements), and evidence that the company can manage operational and regulatory complexity without major setbacks. Falsification would come from clinical failures, safety signals, or inability to secure further funding on reasonable terms.
The Most Likely Path: Incremental Progress, More Dilution, and Ongoing Execution Risk
For most clinical-stage biotechs, the base case is neither breakout success nor outright failure, but a series of incremental steps punctuated by financing events and periodic setbacks. Jasper is likely to advance briquilimab and KP104 through additional mid-stage trials, with some positive signals but also delays, protocol changes, or less-than-transformative results. Integration of Kira’s assets may stretch management bandwidth, leading to prioritization decisions and possible pipeline pruning. As the company approaches key data readouts in 2027, it will almost certainly need to raise additional capital, likely through equity or structured deals, given ongoing negative cash flows. If disclosed, progress would be measured by trial enrollment rates, interim data, and the ability to secure bridge financing without punitive dilution. Falsification could come from missed milestones, stockholder approval delays, or a deteriorating cash position before new funding is secured.
How Execution or Clinical Failures Could Force Strategic Retreat
The primary downside scenarios for Jasper involve either clinical setbacks or acute financial stress. If pivotal or mid-stage data for briquilimab or KP104 fail to confirm prior efficacy or safety findings, Jasper could lose its lead asset(s) and see its strategic rationale undermined. Integration missteps post-Kira merger—such as cultural clashes, regulatory delays, or loss of key personnel—could compound execution risk. Should the company face delays in stockholder approvals (as required for preferred stock conversion) or encounter a risk-averse funding environment, it could be forced to curtail R&D, seek a distressed sale, or liquidate non-core assets. Confirmation of this scenario would come from negative trial results, missed clinical or corporate milestones, lack of progress on integration, or public warnings about liquidity shortfall before the next major inflection point.
Milestones That Will Determine Whether Jasper Can Deliver on Its Ambitions
Enrollment progress and timeline updates for pivotal or registration-enabling briquilimab trials in CSU and CIndU—delays or low enrollment would signal execution risk.
Top-line and interim data for KP104 in IgAN and PNH, and any disclosed progress for KP701—positive results would validate the expanded pipeline strategy.
Updates on integration of Kira Pharmaceuticals, including retention of key personnel and clear R&D prioritization.
Cash burn rate and quarterly cash position—if disclosed, the duration of runway versus planned milestones will be critical.
Announcements of partnership, out-licensing, or non-dilutive funding deals that could extend runway or validate asset value.
Regulatory feedback (FDA/EMA) on briquilimab or KP104—positive or negative feedback could shift timelines and perceived risk.
Progress with stockholder approvals for preferred stock conversion and any related governance or capital structure concerns.
Any safety signals or adverse events in ongoing trials that could challenge the risk/benefit profile of lead assets.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments