
Virginia National Bankshares: Community Banking Scale, Earnings Momentum, and the Boundaries of Regional Focus
Virginia National Bankshares has delivered improved profitability and rising tangible book value in 2026, leveraging a diversified loan book and disciplined investment portfolio. The challenge ahead: translating local market strength and prudent risk management into sustainable growth while navigating interest rate cycles, credit risk, and intensifying competition from larger banks and digital entrants.
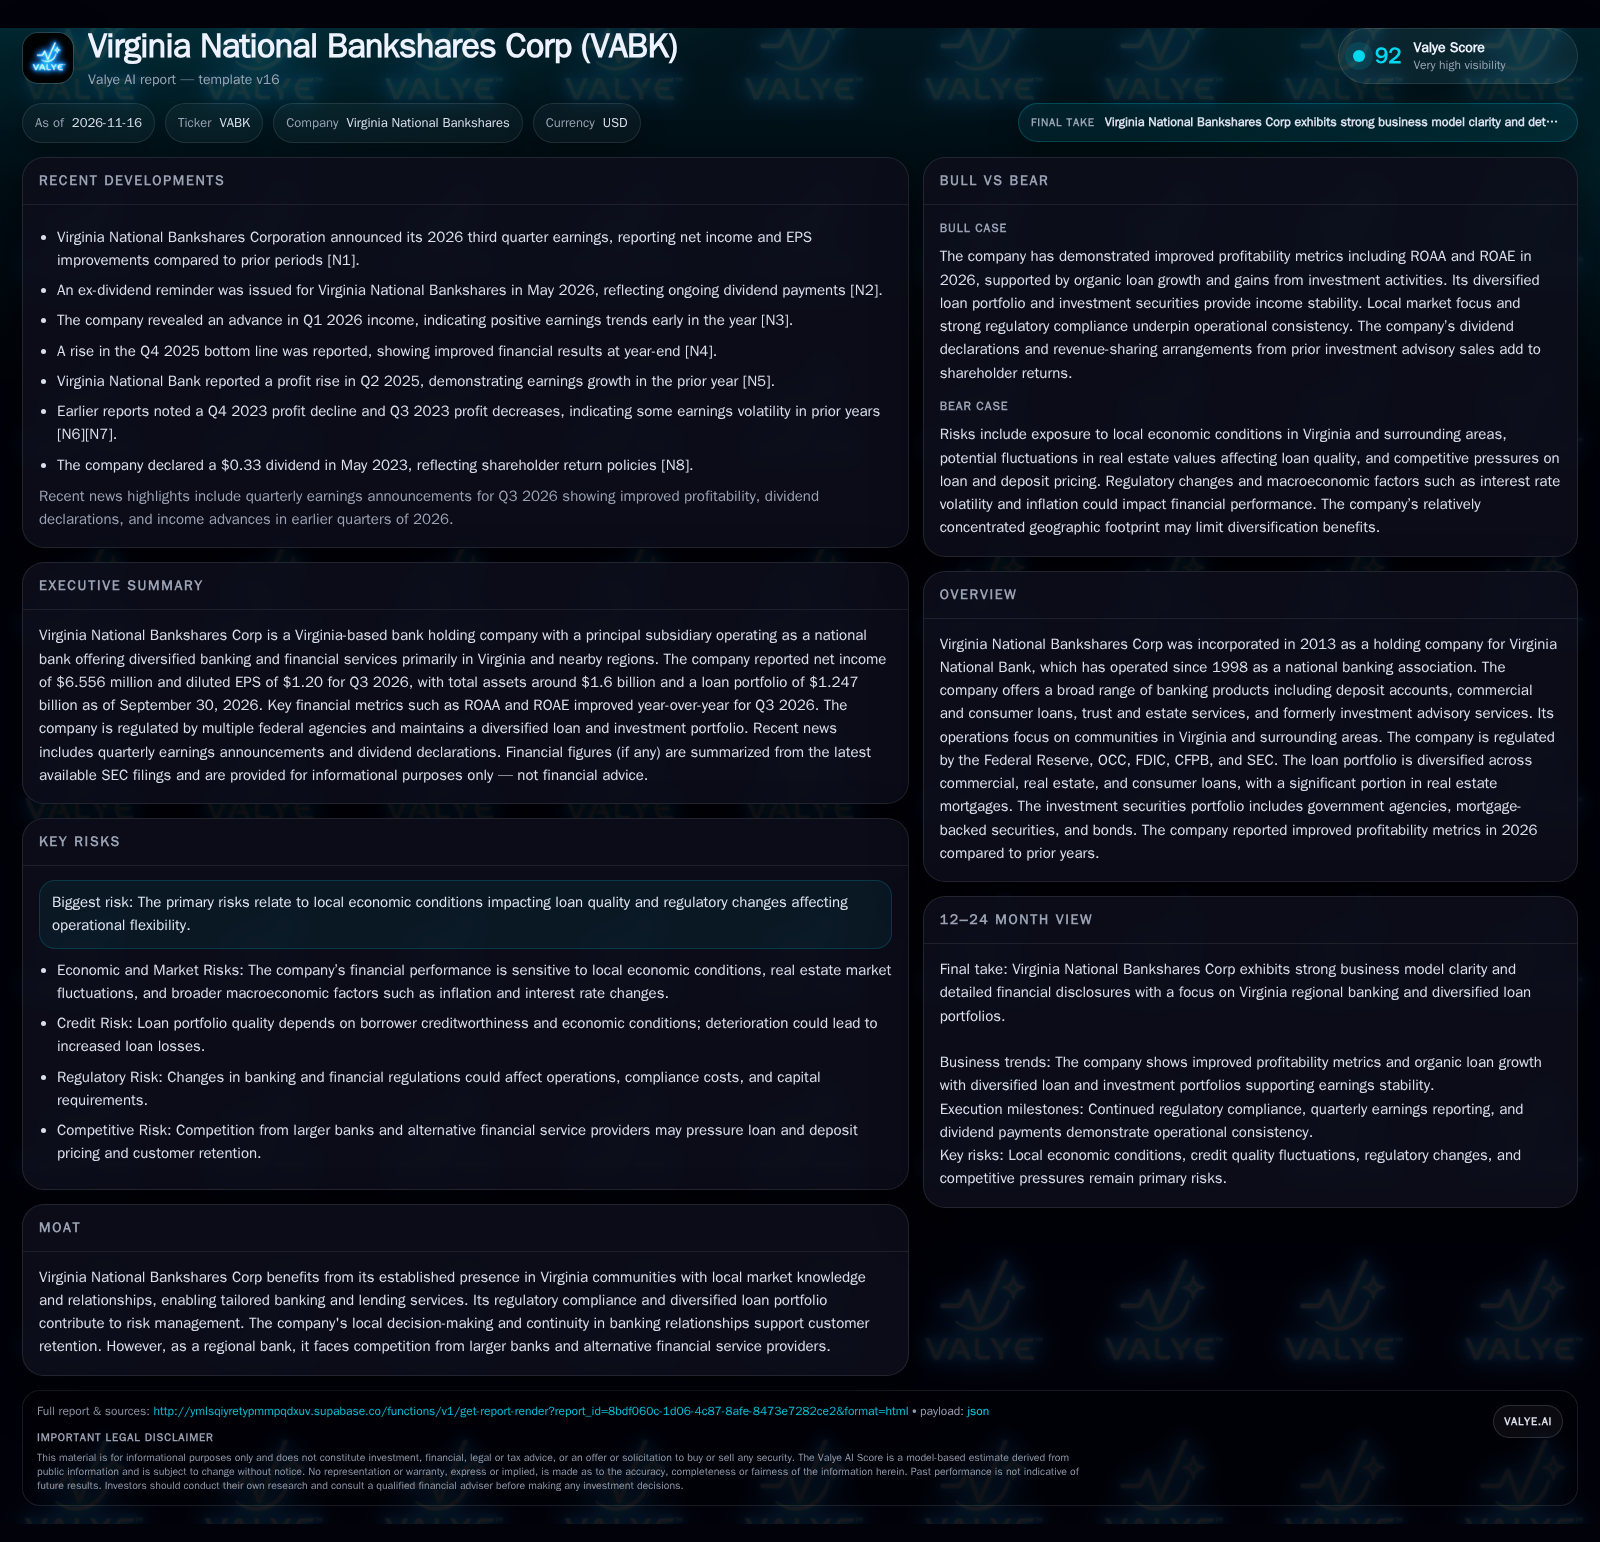
Virginia National Bankshares reported stronger Q3 2026 results, with net income of $6.556 million and improved profitability metrics. A diversified loan portfolio and selective investment securities underpin earnings, but local economic exposure and competition remain central challenges. The real question is whether the company’s community banking model can continue to deliver attractive returns and defend its market position as macro and regulatory headwinds evolve. [S2]
Virginia National Bankshares Corp, the holding entity for Virginia National Bank, is delivering on its promise of community-focused banking with tangible improvements in profitability and book value in 2026. With a $1.6 billion asset base and a loan book that is both sizable and diversified, the company’s operating model remains rooted in serving Virginia’s local economies. However, as interest rate cycles and digital disruption reshape the competitive landscape, the company’s ability to sustain above-average returns will hinge on disciplined risk management, prudent capital deployment, and the ongoing evolution of its product and geographic footprint. The next chapters for this regional bank will be written not just by local lending trends, but by its capacity to adapt to broader financial sector headwinds and opportunities.
Recent Performance: Asset Growth, Loan Diversification, and Profitability Gains
As of September 30, 2026, Virginia National Bankshares reported total assets of approximately $1.6 billion, with loans representing 76.6% of assets at $1.247 billion. The company’s loan book is diversified across commercial, real estate (including construction, residential, and commercial mortgages), and consumer segments, mitigating concentration risk and supporting risk-adjusted yield management. Investment securities totaled $219.9 million, primarily in U.S. government agencies, mortgage-backed securities, and high-quality bonds, providing liquidity and interest income stability. The company delivered net income of $6.556 million and diluted EPS of $1.20 for Q3 2026, with ROAA of 1.58% and ROAE of 13.34%, both reflecting improvement over prior periods. These results indicate a period of earnings momentum and disciplined asset allocation, with tangible book value per share climbing to $33.21. [S2]
How Virginia National Earns: Core Revenue Streams and Margin Dynamics
Virginia National Bankshares generates revenue primarily through the spread between interest earned on loans and investment securities and interest paid on deposits and borrowings. The loan portfolio’s composition—diversified across commercial, real estate, and consumer lending—enables the bank to balance risk and yield, with commercial and real estate loans typically offering higher spreads but also higher credit and collateral risk. Non-interest income, including trust, estate, and investment advisory fees, has historically contributed to revenue diversification, though the 2024 sale of its investment advisory business means future non-interest income will depend on ongoing revenue-sharing arrangements rather than direct management. [S1] [S2]
Operating leverage arises from the bank’s ability to grow assets and deposits faster than fixed costs, such as branch operations and compliance. However, as a regional bank, scale is inherently limited by geographic focus, and further efficiency gains may depend on digital channel adoption or selective expansion. Funding costs are sensitive to regional competition and Federal Reserve policy, with deposit pricing pressure likely to persist as larger and online banks compete aggressively for retail and commercial balances. The cited source reports dividend-related activity; that disclosure alone does not establish dividend-policy continuity, management confidence, or a material constraint on capital flexibility.
Defending Market Share: Local Relationships vs. Big Bank and Digital Encroachment
Virginia National’s core competitive advantage lies in its established presence and relationships within Virginia communities, enabling tailored lending and deposit solutions that may be less accessible to national or digital-first competitors. Local decision-making, knowledge of borrower circumstances, and continuity in relationship management support customer retention and may help attract small business and high-net-worth clientele seeking personalized service.
However, regional banks increasingly face margin and share pressure from both larger national banks—who can outcompete on technology, product breadth, and pricing—and from digital banks and fintechs targeting the same deposit and lending pools with lower operating costs and more scalable platforms. The risk is that larger players leverage superior resources for marketing, risk analytics, and compliance automation, while digital entrants erode fee and interest margins for commoditized products. The company’s future competitive position will likely depend on its ability to deepen customer relationships, offer differentiated products, and selectively invest in technology without losing the local touch.
Earnings Momentum Compounds if Credit Quality Holds and Local Expansion Accelerates
The favorable scenario for Virginia National Bankshares sees continued organic growth in loans and deposits, supported by resilient local economies and stable credit quality. If the company can maintain or improve its ROAA and ROAE through disciplined underwriting and proactive risk management—while leveraging revenue-sharing from past investment advisory operations—earnings could compound and support further tangible book value accretion.
Additional upside could materialize if the bank successfully expands its geographic footprint into high-growth adjacent markets or leverages technology to attract new customer segments without materially increasing fixed costs. Confirmation of this scenario would include sustained low non-performing asset ratios (if disclosed), above-peer loan growth in core segments, and stable or improving net interest margins even amid competitive deposit pricing. Evidence of successful digital adoption, cross-selling, or new business line launches would further bolster the thesis.
Sustainable Returns Amid Cyclical Fluctuations and Measured Asset Growth
The most plausible outcome is that Virginia National Bankshares continues to deliver solid, if unspectacular, returns anchored in its core markets, with periodic volatility tied to local economic cycles and interest rate movements. Loan and deposit growth are likely to track regional GDP and population trends, with credit quality remaining generally strong but subject to periodic stress from real estate or commercial downturns.
Net interest margins may compress modestly as deposit competition intensifies and asset yields adjust to macro conditions, but prudent underwriting and a diversified loan book should limit outsized losses. Non-interest income is likely to be steady but not a major growth driver, given the divestiture of direct investment advisory operations. Confirmation would come from continued incremental growth in tangible book value per share, stable ROAA and ROAE in the low-to-mid teens, and absence of material regulatory or credit shocks.
Localized Downturn or Credit Event Erodes Earnings and Capital Buffers
In a negative scenario, Virginia National Bankshares could face a localized economic downturn, sharp real estate correction, or a sector-specific credit event that leads to rising non-performing loans and charge-offs. Given the bank’s asset concentration in Virginia and surrounding areas, exposure to a regional recession or sectoral distress—such as commercial real estate—could quickly translate into higher loan losses, lower earnings, and pressure on capital ratios.
Additionally, rapid shifts in deposit pricing, triggered by aggressive competition or monetary tightening, could squeeze net interest margins and force the bank to pay up for funding or lose market share. A regulatory change increasing capital requirements or compliance costs would further constrain profitability. Confirmation of downside risk would include a meaningful uptick in non-performing assets, declining ROAA/ROAE, negative tangible book value growth, or the need for capital raises or dividend cuts in response to stress.
What Will Determine Virginia National Bankshares’ Staying Power in Community Banking?
Quarterly and annual trends in ROAA and ROAE—continued improvement or sudden deterioration will signal management’s ability to sustain profitability through cycles. [S2]
Loan growth by segment, particularly commercial and real estate—above-market gains would suggest competitive strength; sharp declines or concentration increases would raise risk flags. [S2]
Net interest margin evolution—compression could indicate intensifying competition or funding cost pressure; stability suggests pricing discipline.
Non-performing asset ratio and charge-off rates (if disclosed)—rising credit costs would challenge the earnings thesis and test risk controls.
Deposit growth and mix—ability to attract and retain low-cost core deposits will be crucial as funding competition intensifies.
Tangible book value per share—sustained growth would confirm ongoing capital generation and prudent asset management. [S2]
Regulatory capital ratios (if disclosed)—declines could signal emerging risk or constrain future dividend and lending capacity.
Progress on digital banking initiatives or new business lines—a useful metric would be customer adoption or fee income growth from these channels, if disclosed.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments