
Kulicke and Soffa: Strategic Refocus, Leadership Transition, and the Stakes of Semiconductor Assembly Cyclicality
Kulicke and Soffa’s 2026 results highlight the company’s ability to deliver strong financials while executing a significant business wind down and navigating a major CEO transition. The shift away from Electronics Assembly sharpens its focus on core semiconductor capital equipment and consumables, but cyclical end markets and evolving customer needs remain central to future performance.
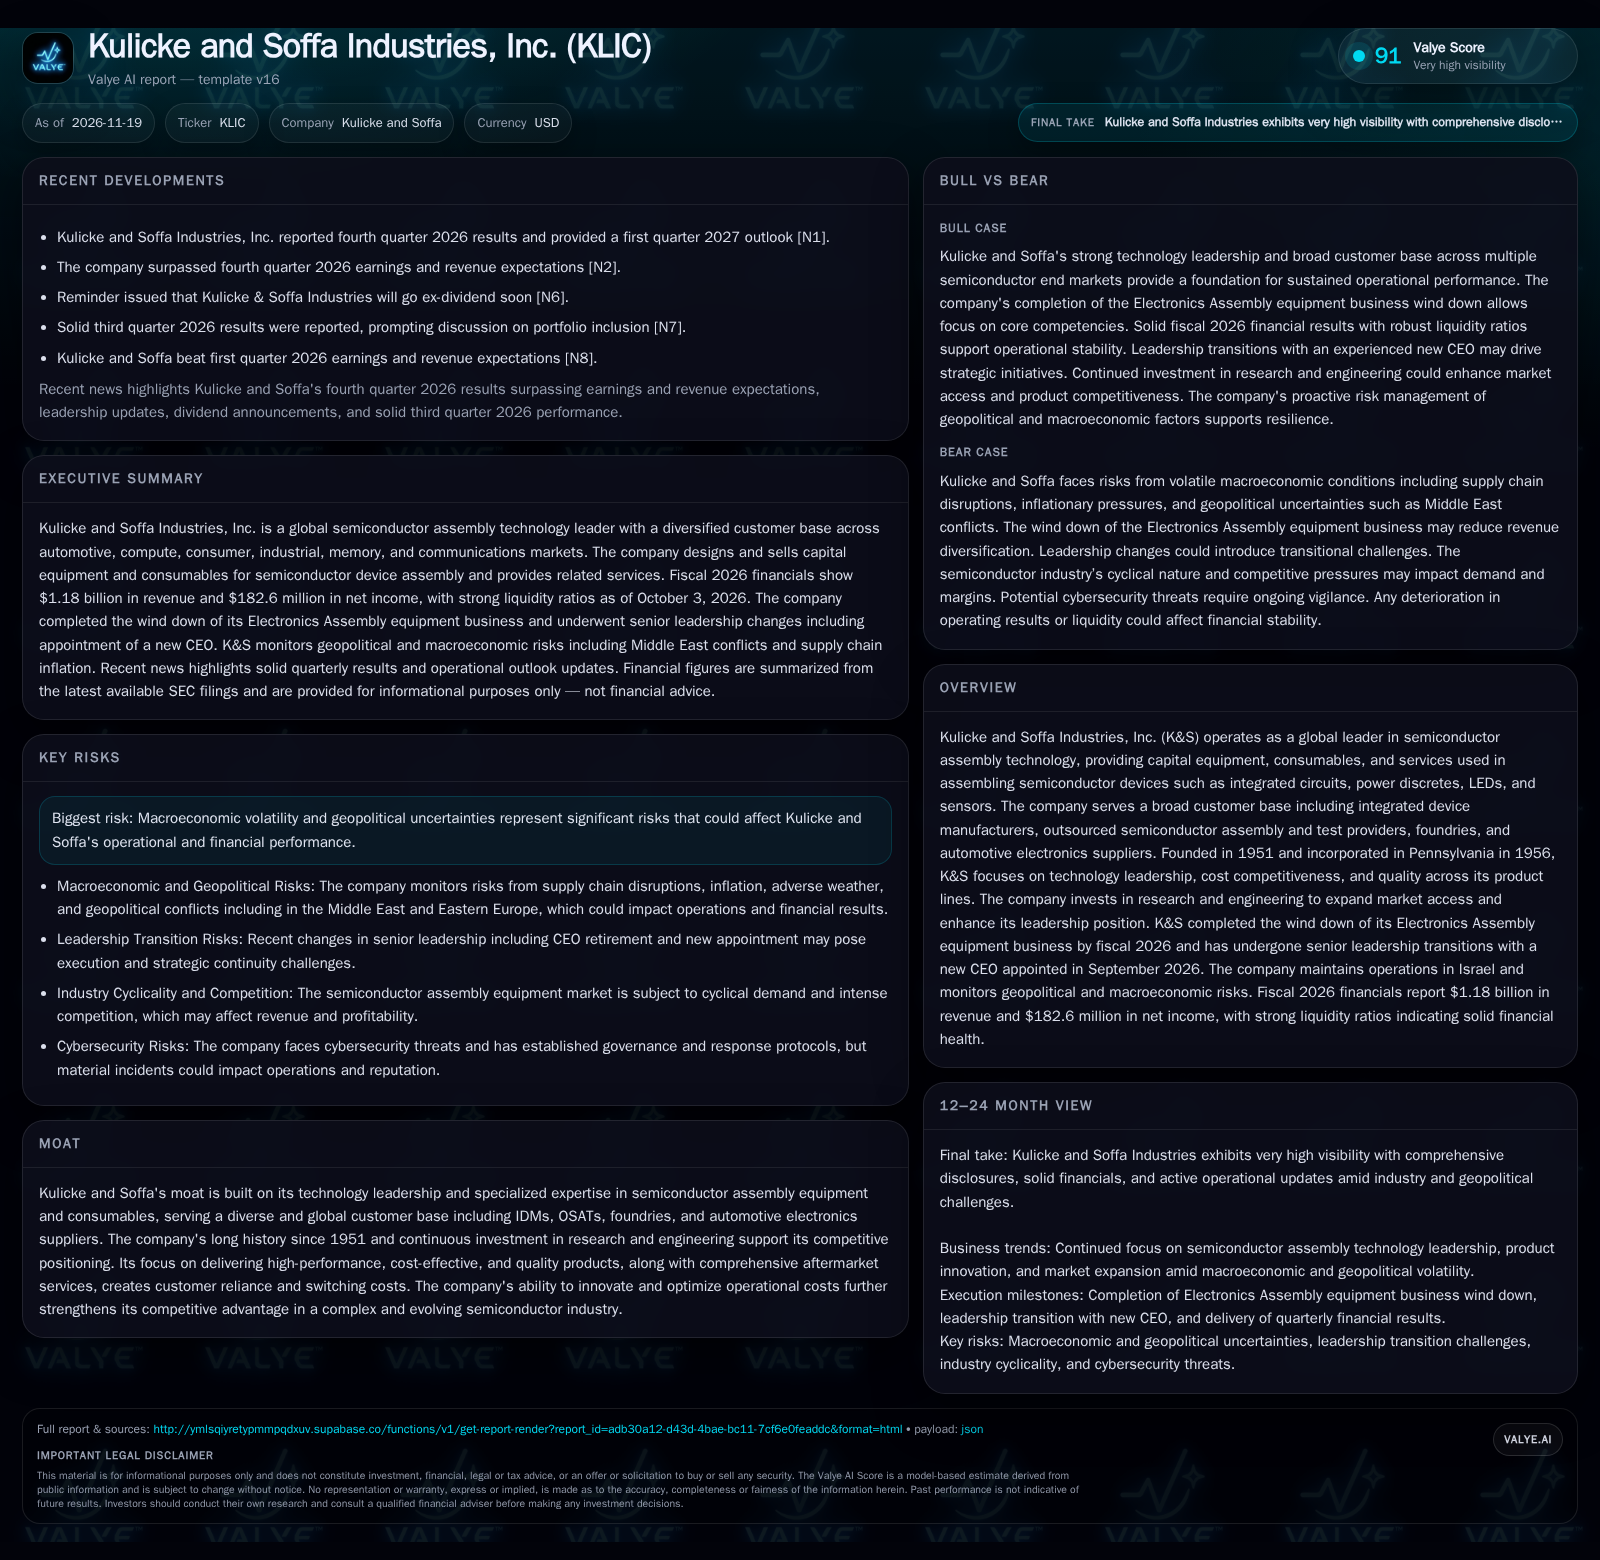
Kulicke and Soffa Industries posted $1.18 billion in fiscal 2026 revenue and $182.6 million in net income, completing the wind down of its Electronics Assembly business and installing a new CEO. [S1] [N1]
Kulicke and Soffa Industries, long recognized for its semiconductor assembly technology, enters 2027 having navigated a complex year of strategic and leadership change. The company’s fiscal 2026 performance underscores its operational strength and financial discipline: $1.18 billion in revenue, $182.6 million in net income, and a completed exit from the Electronics Assembly equipment business. With new CEO Dr. Raj Talluri at the helm, K&S is positioned to double down on its core capital equipment and consumables for semiconductor manufacturing. However, the cyclical nature of semiconductor demand, evolving customer requirements, and global supply chain dynamics will test the durability of its recent gains. [S1] [N1]
2026: A Year of Strategic Refocus and Leadership Change
Kulicke and Soffa Industries reported $1.18 billion in fiscal 2026 revenue and $182.6 million in net income, demonstrating operational resilience in a volatile macroeconomic environment. The company completed the wind down of its Electronics Assembly (EA) equipment business, fulfilling last-time orders and continuing service support for remaining obligations. This strategic move narrows the company’s focus to its core semiconductor assembly solutions for IDMs, OSATs, foundries, and automotive electronics suppliers. Leadership transitioned from Dr. Fusen Chen to Dr. Raj Talluri as CEO in September 2026, with an interim period under Lester Wong. K&S also reported liquidity position with $329.0 million in cash and a current ratio of 3.37 as of October 3, 2026. The company’s quarterly results continue to surpass expectations, but management remains vigilant regarding geopolitical, supply chain, and inflationary risks. [S1] [N1] [N2]
How K&S Earns: Capital Equipment, Consumables, and Service Economics
Kulicke and Soffa’s primary revenue streams come from the sale of semiconductor assembly capital equipment, consumables (such as bonding wires and tools), and aftermarket services. Capital equipment sales are typically high-value, cyclical transactions, with demand driven by semiconductor manufacturers’ capacity expansions, technology upgrades, and process migrations. Consumables and aftermarket services—delivered to both K&S and peer equipment users—offer more recurring, higher-margin revenue streams, smoothing some of the cyclicality inherent in capital equipment sales.
Gross margins in this industry are influenced by product mix (advanced vs. legacy systems), volume leverage, and the ability to maintain pricing power amid customer concentration. The company’s focus on higher-productivity systems and autonomous capabilities is intended to drive customer value, potentially supporting premium pricing and retention. However, fixed costs for R&D and global support functions mean that operating leverage can swing both ways: robust upcycles boost profitability, but downturns expose margin vulnerability.
The completion of the EA equipment business wind down may reduce revenue diversification but could also improve focus and margin profile if core offerings command higher returns. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S1]
Technology Leadership Versus Industry Cyclicality and Competitive Pressure
K&S’s competitive positioning rests on technology leadership in semiconductor assembly equipment and consumables, which are critical for integrated device manufacturers and outsourced assembly providers. The company’s ability to innovate—through higher-throughput, more autonomous, and cost-effective systems—creates switching frictions and supports long-term customer relationships. Its comprehensive aftermarket services and global support infrastructure further reinforce customer reliance.
However, the semiconductor equipment industry is structurally competitive and highly cyclical. Large capital projects are often lumpy, and customers can switch to alternative suppliers during downturns or when new technologies emerge. Competitor categories include other global capital equipment manufacturers specializing in wire bonding, advanced packaging, and related assembly processes. Margin pressure can intensify during downcycles, especially if customers delay capital expenditures or negotiate aggressively on pricing and service packages.
Geopolitical and trade risks—such as export controls and regional supply chain disruptions—can also affect K&S’s ability to serve key markets or source critical components. The company’s continued investment in R&D and operational cost optimization is essential to defend its technology edge and maintain cost competitiveness.
If Semiconductor Capex Recovers and K&S Captures Share
A plausible upside scenario involves a rebound in semiconductor capital expenditures, driven by new technology nodes, expansion in automotive and AI-related end markets, or easing of supply chain bottlenecks. If K&S’s focus on autonomous capabilities and operational cost optimization resonates with customers, it could capture incremental share from competitors or accelerate upgrades among existing clients.
Confirmation of this scenario would require evidence of sustained order growth, particularly for advanced packaging and high-throughput equipment, as well as rising consumables and service attachment rates. Gross margin expansion—driven by product mix and scale—would reinforce the thesis that K&S’s portfolio is aligned with customer needs. Additional indicators would include new design wins, expansion of long-term service contracts, and commentary from management about outpacing industry growth rates.
This scenario is more likely if the company leverages its post-EA business focus to deepen core customer relationships and accelerate product cycles.
Core Strengths Persist, but Cyclical Volatility Remains
The most plausible trajectory is for K&S to maintain its position as a leading supplier to a broad set of semiconductor assembly customers, with financial performance tracking the industry’s underlying cycles. The company’s technology leadership, global reach, and aftermarket capabilities should support resilience, but revenue and margin swings are likely to mirror broader semiconductor capital spending trends.
In this scenario, K&S continues to invest in R&D and customer support, offsetting some cyclicality with recurring consumable and service revenues. The wind down of the EA business streamlines operations but slightly reduces diversification. Leadership transition risks are managed effectively, with the new CEO sustaining strategic continuity and operational discipline.
Evidence of this scenario includes quarterly results in line with industry peers, stable or gradually improving margins, and continued investments in innovation. Deterioration would be signaled by pronounced underperformance versus sector benchmarks, loss of key customers, or delays in responding to technology shifts.
Adverse Cycle, Execution Missteps, or Strategic Disruption
A negative outcome could result from a sharp downturn in semiconductor capital spending, potentially triggered by global economic weakness, inventory corrections, or trade/regulatory shocks. Under such conditions, K&S’s capital equipment revenues could fall precipitously, and fixed R&D and support costs would pressure margins.
Execution missteps in the wake of the CEO transition—such as loss of strategic focus, delays in new product launches, or customer defections—could exacerbate the impact of a cyclical downturn. The completed EA business wind down reduces diversification, potentially making the company more sensitive to weak demand in its remaining core markets.
Evidence for this scenario would include significant revenue declines outpacing industry averages, gross margin contraction, loss of major customers, or indications that the company is lagging in technology upgrades. Unanticipated supply chain or geopolitical disruptions could also accelerate downside risks.
Measures That Will Reveal the Durability of K&S’s Strategic Refocus
Order intake and backlog trends for core semiconductor assembly equipment, particularly advanced packaging and high-throughput systems, if disclosed.
Consumables and aftermarket service revenue growth rates, which would indicate the stability and quality of recurring revenue streams.
Gross margin evolution, especially as the company exits the EA business and reorients toward its core portfolio.
Customer concentration metrics and new customer wins, as signs of either vulnerability or competitive gains.
Evidence of successful integration and execution under the new CEO, including product launch cadence and strategic continuity.
Quarterly comparisons to peer capital equipment suppliers to benchmark relative performance and market share shifts.
Disclosure of material impacts from geopolitical events or supply chain disruptions, as these could affect both revenue and cost structure.
R&D investment levels and product innovation pipeline disclosures, which would help assess the company’s ability to sustain its technology moat.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments