
LifeMD’s Subscription Telehealth Model: Integration, Scale Ambitions, and the Realities of Healthcare Economics
LifeMD’s vertically integrated telehealth platform—anchored by subscription-based care, proprietary pharmacy operations, and a broad specialty offering—has demonstrated growth in patient subscribers and ecosystem control. Yet persistent net losses, thin liquidity, and a highly competitive virtual care market underscore the tension between scaling ambitions and the economic realities of digital healthcare delivery.
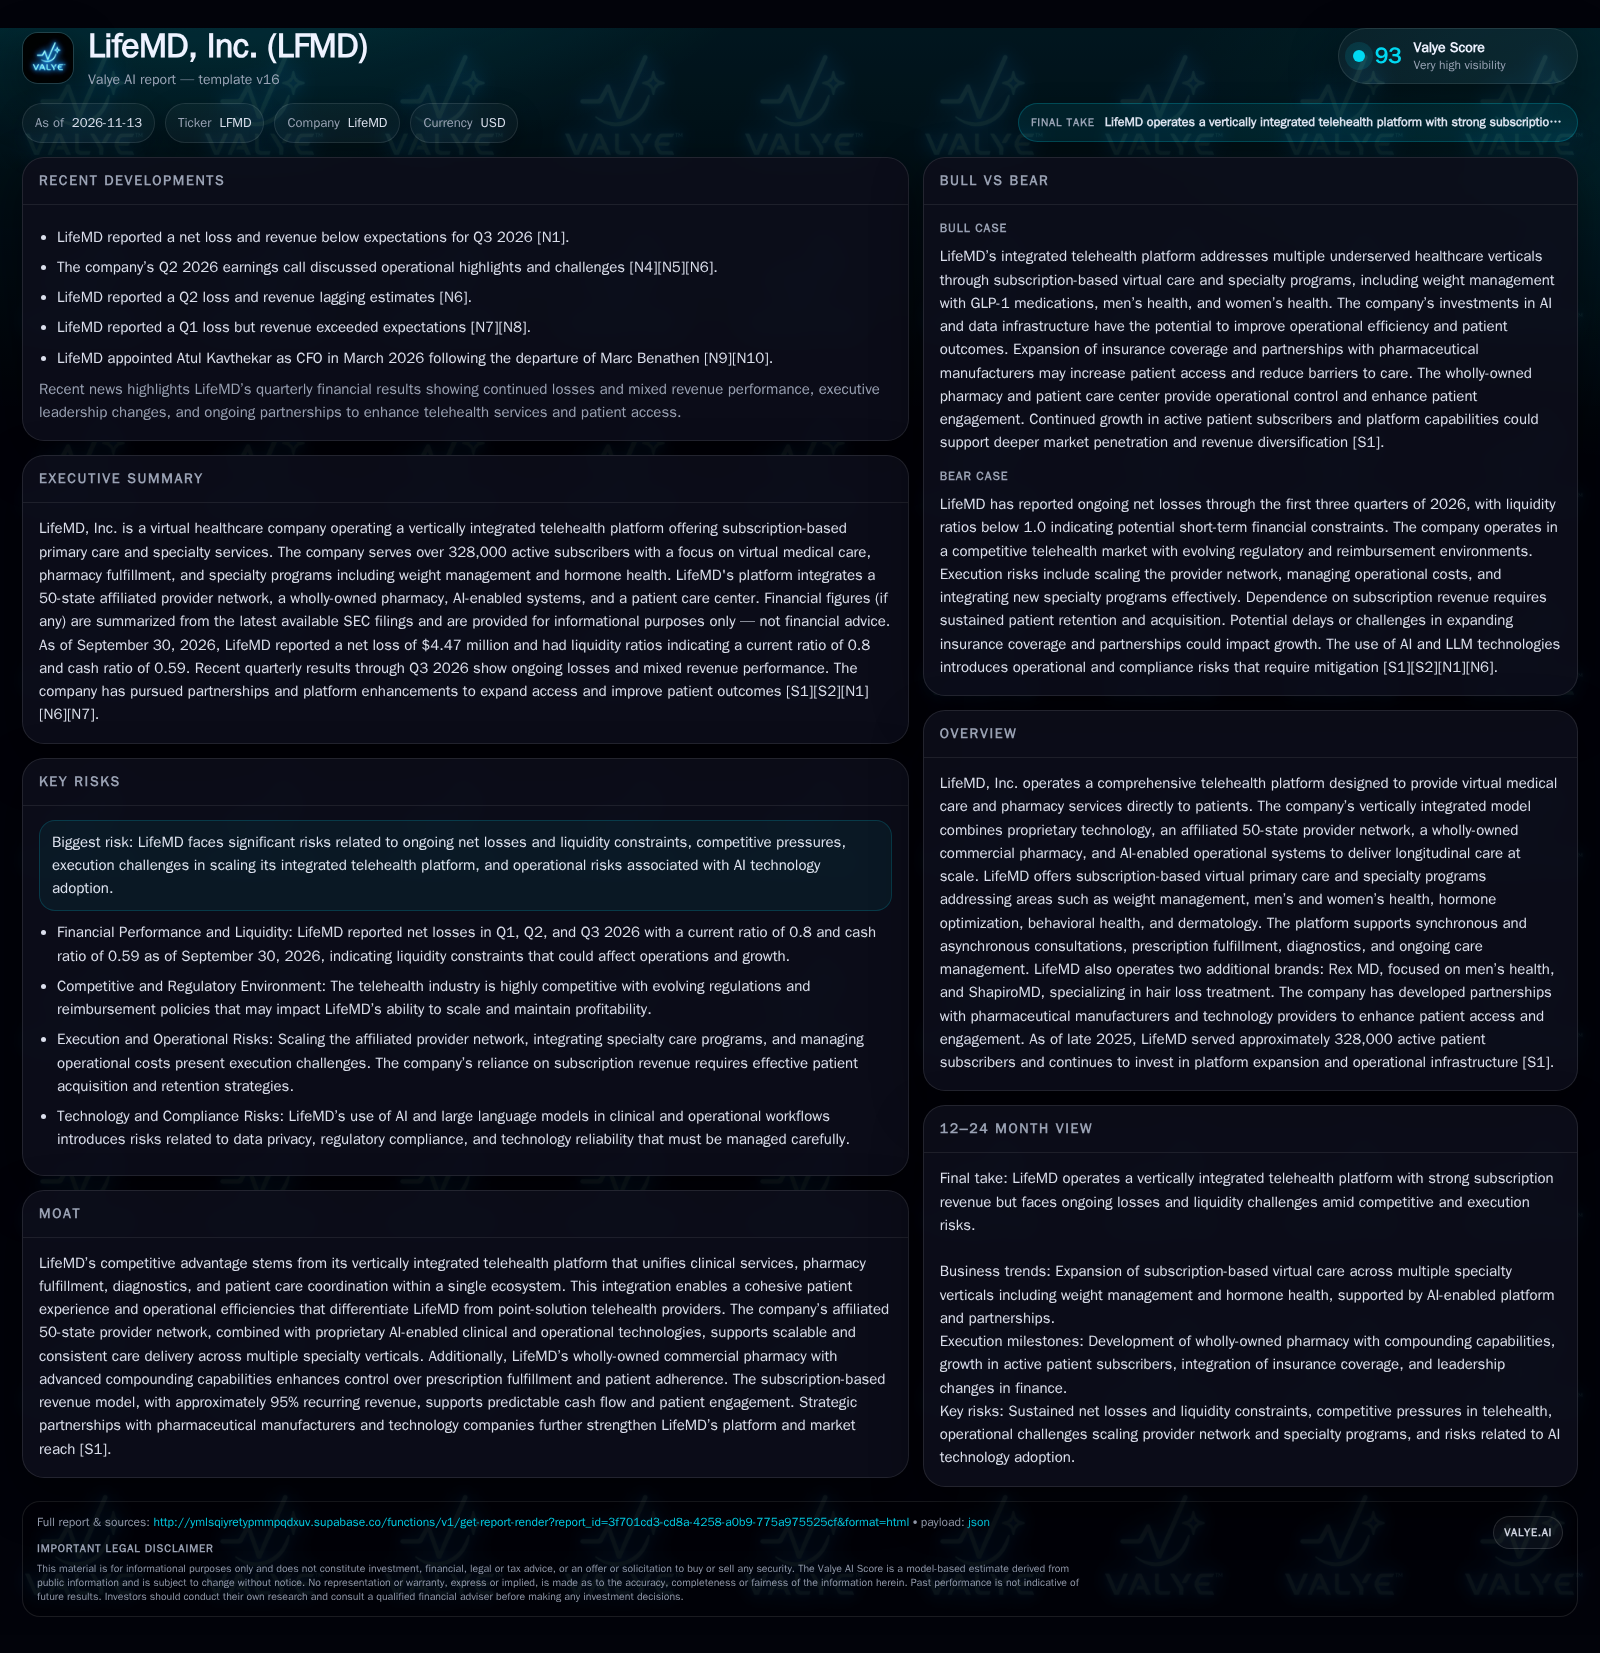
LifeMD, Inc. operates a comprehensive telehealth platform with a focus on recurring subscription revenue, serving over 328,000 active patient subscribers as of late 2025. The company’s integrated approach spans virtual care, pharmacy fulfillment, and specialty programs such as weight management and hormone health. Future performance will hinge on patient retention, cost discipline, and the ability to leverage AI and partnerships for operational efficiency and patient engagement [S1] [S2] [N1] [N6] [N7].
LifeMD, Inc. has positioned itself as a patient-centric, vertically integrated telehealth provider, operating at the intersection of virtual care, pharmacy services, and digital health innovation. With over 328,000 active patient subscribers and a robust specialty offering—including a rapidly expanding weight management program—LifeMD seeks to differentiate through ecosystem control and operational integration. The next phase for LifeMD will test whether its integrated model can deliver sustainable growth or if sector headwinds will force a strategic reset.
Recent Financial Results and Platform Scale: What’s Changed for LifeMD
As of September 30, 2026, LifeMD reported a net loss of $4.47 million, with cash and equivalents at $36.2 million and a current ratio of 0.8 [S2]. These figures reflect continued operational losses and below-1.0 liquidity, signaling potential short-term financial constraints. The company’s active patient subscriber base stood at approximately 328,000 as of December 31, 2025, spanning primary care and specialty verticals, including 81,000 enrolled in weight management programs focused on GLP-1 medications [S1]. Quarterly results in 2026 consistently showed losses and mixed revenue outcomes versus expectations [N1] [N6] [N7]. LifeMD’s ongoing investments in a wholly-owned pharmacy, advanced compounding, and AI-enabled operations have not yet translated into sustained profitability, but do reflect a commitment to platform expansion and operational control.
How LifeMD’s Integrated Model Seeks Profitability—and Where the Leverage Lies
LifeMD generates the vast majority of its revenue—approximately 95%—from recurring patient subscriptions, covering virtual primary care and specialty programs [S1]. This model theoretically provides revenue predictability and supports lifetime value through retention, but also exposes the company to churn and acquisition-cost pressures. The vertically integrated approach, including a nationwide provider network and a wholly-owned commercial pharmacy with compounding capabilities, may offer margin benefits over pure-play telehealth platforms reliant on third-party fulfillment. However, the fixed costs of maintaining a 50-state provider footprint, the patient care center with 119 employees, and ongoing investments in AI and operational infrastructure create substantial operating leverage, amplifying the impact of both subscriber growth and attrition.
The addition of advanced compounding at the Lancaster, PA pharmacy could improve gross margins on certain specialty medications, but likely requires scale to offset investment and regulatory compliance costs. Partnerships with pharmaceutical manufacturers and technology firms may unlock volume-based purchasing power and improve medication access, but the economics of these arrangements are not fully disclosed. Overall, LifeMD’s path to profitability hinges on balancing subscriber growth, cost discipline, and extracting greater margin from its integrated care ecosystem.
Integration as Differentiation: LifeMD’s Competitive Standing in Virtual Care
LifeMD competes in a fragmented and rapidly evolving telehealth market, facing pressure from large virtual care platforms, retail health entrants, and specialized digital health brands. Its primary differentiator is the integration of clinical services, pharmacy fulfillment, diagnostics, and AI-enabled operations within a unified platform, which may enhance patient experience and enable operational efficiencies. The company’s 50-state provider network and wholly-owned pharmacy provide control over care delivery and fulfillment, potentially reducing leakage to outside providers and supporting adherence.
However, competitors with greater scale or established payer relationships may offer broader service access or lower pricing, challenging LifeMD’s ability to maintain margins and subscriber growth. The subscription model can drive stickiness if supported by strong patient engagement, but switching costs for virtual care remain modest unless differentiated by outcomes, convenience, or cost. Regulatory risk is also material, as telehealth reimbursement and licensing rules continue to evolve. LifeMD’s ability to leverage AI and data for superior patient outcomes and operational efficiency could create an advantage, but only if investments yield tangible improvements in retention and cost structure.
A Virtuous Cycle: When Scale, Integration, and AI Unlock Margin Expansion
In a favorable scenario, LifeMD’s continued investment in platform integration and AI-enabled operations yields improved patient retention, higher engagement, and reduced operating costs. The wholly-owned pharmacy and compounding capabilities support better medication adherence and higher-margin specialty offerings, particularly in weight management and hormone health. As the company grows its active subscriber base, fixed costs are leveraged, driving operating margins higher and moving the business toward profitability. Partnerships with pharmaceutical manufacturers and technology providers deepen, enabling improved medication access and potentially expanding into insurance-covered segments.
Evidence that would confirm this scenario includes: sustained and accelerating growth in active subscribers (especially in high-margin specialty programs), improving gross and operating margins, positive cash flow from operations, and reduction in net losses over sequential quarters. Additionally, successful integration of AI that demonstrably lowers cost per encounter or improves patient outcomes would further validate the upside thesis.
Sustained Growth Meets Cost Gravity: The Most Likely Trajectory for LifeMD
The most plausible scenario is that LifeMD continues to grow its subscriber base at a moderate pace, driven by demand for virtual primary care and specialty programs, but faces ongoing cost pressures from provider network maintenance, pharmacy operations, and compliance obligations. The recurring subscription model provides some revenue stability, but churn and acquisition costs offset much of the scale benefit, keeping margins thin. Investments in AI and operational infrastructure may yield incremental efficiencies, but not enough to fully close the profitability gap in the near term.
In this scenario, LifeMD remains a sub-scale but growing telehealth platform, periodically raising external capital to fund operations and expansion. Evidence supporting this path would be sequential growth in subscribers and revenue, persistent but narrowing net losses, and stable or improving retention metrics. On the other hand, evidence of deteriorating liquidity, flat subscriber growth, or rising operating expenses would challenge even this moderate outlook.
When Growth Can’t Outrun Costs: How Execution or Market Shocks Could Derail LifeMD
A negative scenario would see LifeMD’s subscriber growth stall or decline due to increased competition, regulatory headwinds, or failure to deliver differentiated outcomes. Fixed costs related to its provider network, pharmacy, and operational overhead become unsustainable relative to revenue, driving widening losses and further liquidity erosion. The company may be forced to curtail investment, lay off staff, or seek dilutive financing under unfavorable terms. Regulatory or reimbursement changes could further squeeze margins or restrict access to key medications in its weight management program.
Confirmation of this scenario would come from sequential declines in subscriber numbers, escalating net losses, negative operating cash flow, and further deterioration in liquidity ratios. Announcements of cost-cutting, workforce reductions, or distressed capital raises would be additional warning signs. Conversely, stabilization in cost structure or a sudden uptick in subscriber growth would argue against this outcome.
Milestones That Will Shape LifeMD’s Economic Sustainability
Active patient subscriber growth, especially within high-value specialty programs such as weight management and hormone health, will be a critical indicator of demand and revenue stability.
Gross and operating margin trends, if disclosed, will reveal whether LifeMD’s integration strategy is translating into real economic leverage.
Churn and retention rates—particularly across core and specialty verticals—would help test the stickiness of the subscription model and long-term patient value.
Cash flow from operations and changes in net loss over sequential quarters will signal whether the company is moving toward or away from financial sustainability.
The pace of adoption and operational impact of AI-enabled tools, as measured by cost per encounter or patient engagement metrics (if disclosed), will indicate the ROI on technology investments.
Progress in expanding partnerships with pharmaceutical manufacturers, technology firms, and insurance providers could either unlock new revenue streams or expose integration risk.
Regulatory or reimbursement developments—especially those affecting telehealth licensure, prescription fulfillment, or GLP-1 medication coverage—could materially alter the addressable market and economics for LifeMD.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments