
LIXTE Biotechnology: Clinical Ambition, Capital Constraints, and Strategic Uncertainty Post-Acquisition
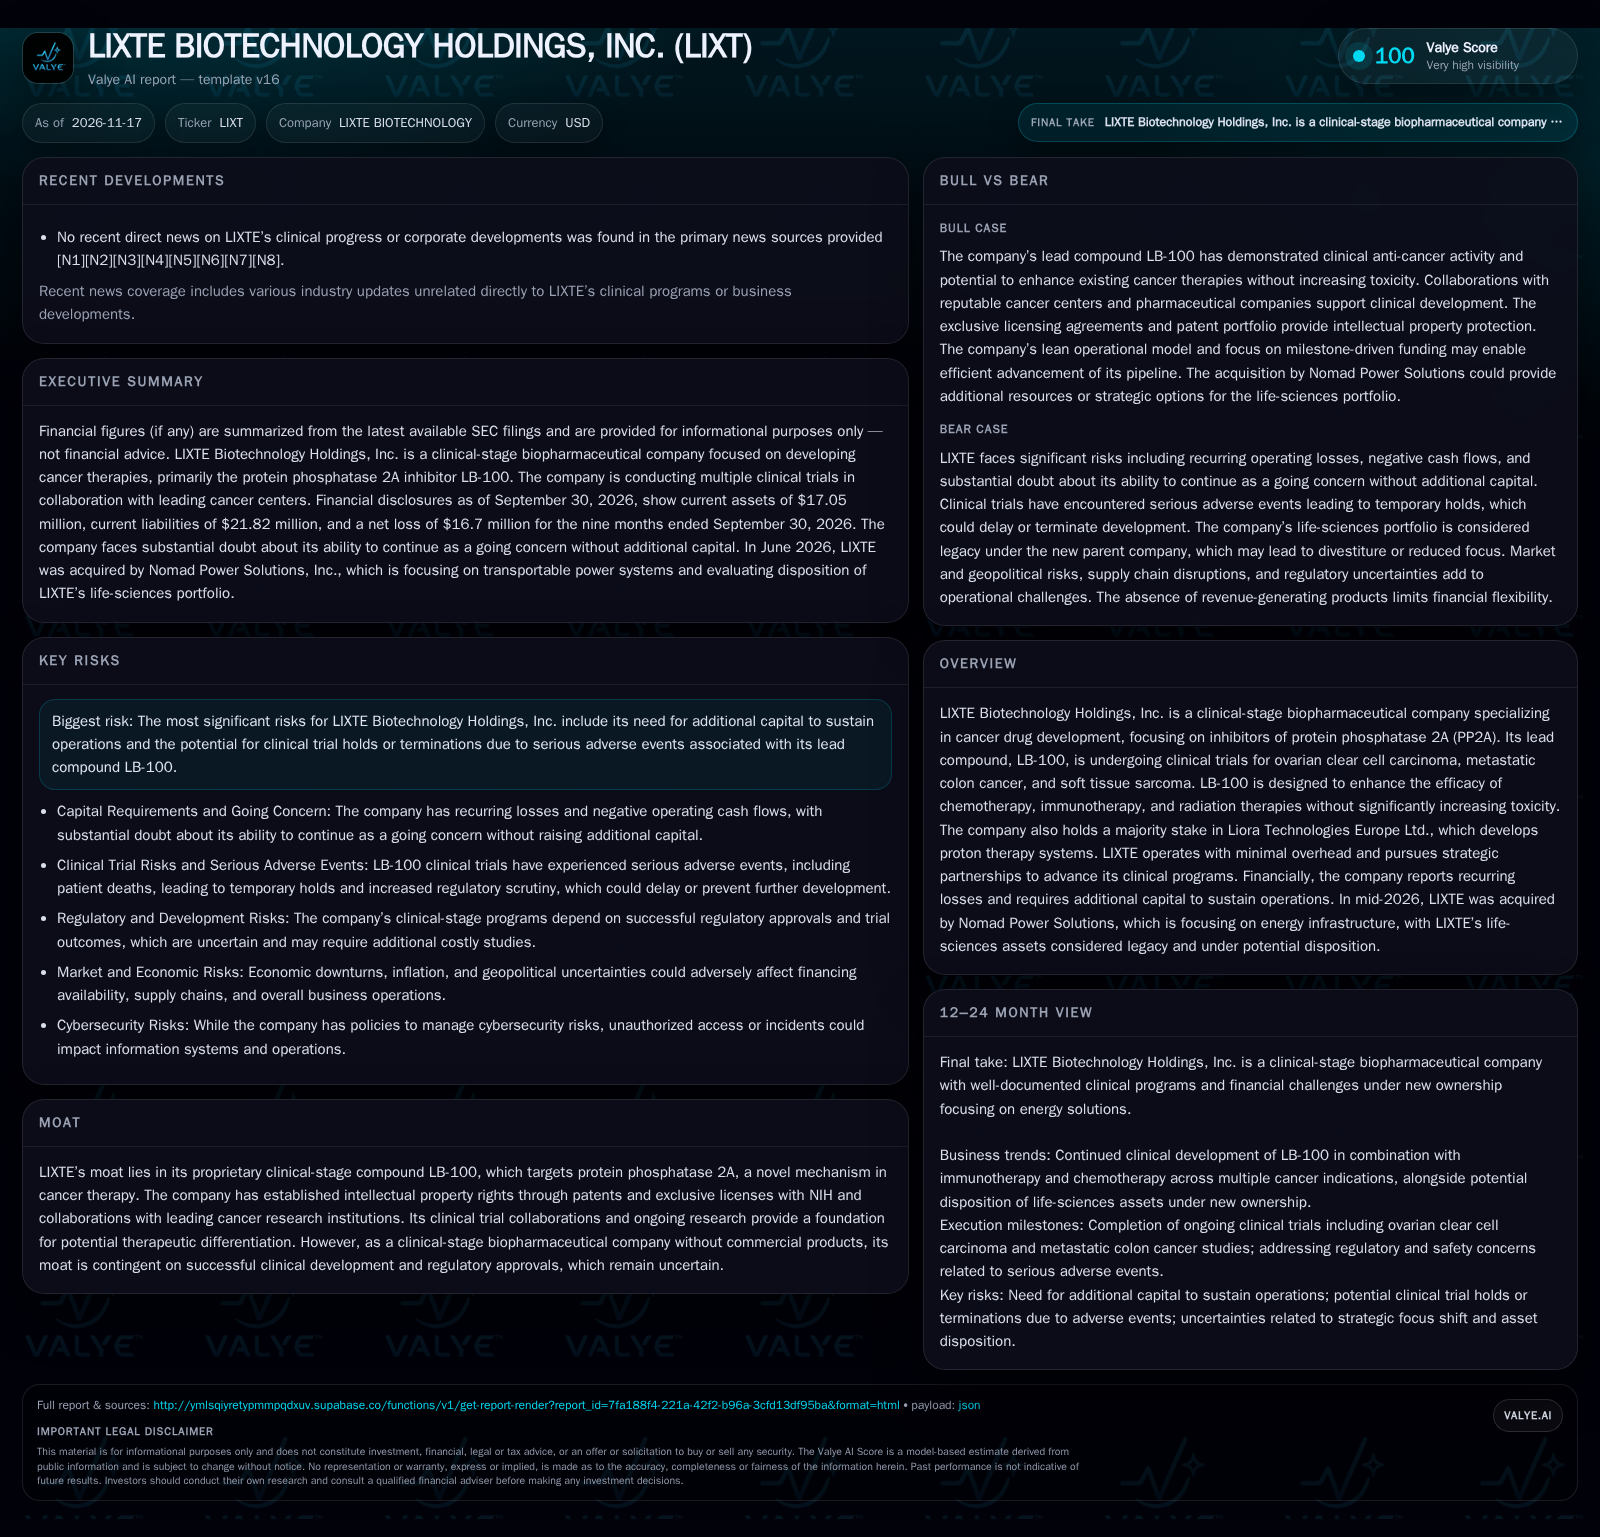
LIXTE Biotechnology Holdings’ lead cancer therapy, LB-100, advances through clinical trials with a differentiated mechanism of action and major institutional partnerships. However, persistent operating losses, acute capital needs, and a strategic pivot by its new parent company place the future of its life sciences assets in question.
LIXTE Biotechnology’s LB-100 continues clinical development in multiple cancer indications, supported by strong institutional collaborations and novel intellectual property. [S2]
LIXTE Biotechnology Holdings stands at a critical inflection point. Its lead drug candidate, LB-100, targets a novel cancer mechanism and is being tested in combination with established therapies across several difficult-to-treat tumor types. Despite scientific momentum and institutional support, the company is beset by chronic losses, a deteriorating cash position, and a parent company with a fundamentally different strategic focus. Whether LIXTE’s pipeline will advance toward commercialization or be divested as a legacy asset now depends on near-term funding, successful clinical outcomes, and the willingness of external partners to carry the science forward. [S2]
Clinical Pipeline Progresses, but Capital Shortfall and Strategic Shift Dominate Outlook
LIXTE Biotechnology’s most material developments center on its lead asset, LB-100, which remains in active clinical testing for ovarian clear cell carcinoma, metastatic colon cancer, and soft tissue sarcoma, with ongoing collaborations at major cancer centers. These trials are underpinned by LB-100’s differentiated mechanism—PP2A inhibition—which may sensitize tumors to chemotherapy, immunotherapy, and radiation without substantial added toxicity. However, as of September 30, 2026, LIXTE’s balance sheet reflects $17.05 million in current assets against $21.82 million in current liabilities and a cash balance of $3.41 million, with a net loss of $16.7 million for the first nine months of the year. The company’s 10-Q explicitly raises substantial doubt about its ability to continue as a going concern without additional financing. [S2]
Strategically, the June 2026 acquisition by Nomad Power Solutions has reclassified LIXTE’s life-sciences business as a legacy portfolio, with Nomad signaling its intention to evaluate options for divestiture or discontinuation. This introduces a new level of uncertainty for stakeholders, as the ongoing development of LB-100 may now depend less on internal execution and more on the outcome of external strategic or financial transactions. [S2]
Pipeline-Driven Model: High Burn, No Revenue, and Binary Value Creation
LIXTE operates the archetypal clinical-stage biopharma model: high fixed costs for research, clinical trials, and intellectual property protection, with negligible variable costs but no recurring revenue until (and unless) a product reaches market. The economic structure is characterized by negative operating leverage, as incremental progress in the clinic drives up expenses without offsetting revenue streams. Capital is typically raised in milestone-driven tranches, with value realization hinging on either a lucrative out-licensing deal, an acquisition by a larger pharmaceutical company, or regulatory approval and commercialization—each a rare and high-risk outcome.
LB-100’s commercial potential, if successful, would likely depend on its demonstrated ability to enhance outcomes in combination with standard regimens. Pricing for oncology drugs with novel mechanisms can be premium if clinical benefit and safety are proven, but the path to such outcomes is fraught with regulatory, competitive, and payer hurdles. The company’s majority stake in Liora Technologies Europe, which develops proton therapy systems, introduces capital-intensive hardware economics but remains peripheral to the core value thesis given the life-sciences portfolio’s legacy status post-acquisition. [S2]
With a current ratio of 0.78 and negative cash flows, LIXTE faces a funding cliff, making near-term capital raises, asset sales, or partnerships essential for survival. There is no evidence of sustainable revenue or cash flows from operations. [S2]
LB-100’s Differentiation Rests on Mechanism, But Commercial Moat Remains Unproven
LIXTE’s competitive narrative centers on LB-100’s unique targeting of protein phosphatase 2A (PP2A), a mechanism with limited direct competition and the potential to create synergy with chemotherapy, immunotherapy, and radiation. Patent coverage and exclusive licensing from the NIH provide intellectual property protection, and collaborations with leading cancer centers offer early validation and potential access to patient populations for pivotal studies.
However, the company operates in a fiercely competitive oncology landscape, where numerous small molecules and biologics are being developed for similar indications. Larger, better-capitalized peers can move quickly if LB-100’s mechanism proves valuable, and the lack of commercial infrastructure means LIXTE (or a future partner) would need to invest heavily in late-stage trials and market access. Furthermore, the temporary clinical hold in the Netherlands Cancer Institute trial following serious adverse events highlights the ever-present risk of setbacks that can erode any emerging advantage. [S2]
Without a commercial product, the company’s moat is entirely prospective and will only be validated if LB-100 demonstrates clear clinical benefit and safety superior to or complementary with existing standards of care.
A Strategic Transaction Could Unlock Value if Clinical Data Catalyzes Partnership or Acquisition
The most favorable outcome for LIXTE hinges on positive clinical data from ongoing LB-100 trials, particularly in combination regimens that address high-need indications such as ovarian clear cell carcinoma or metastatic colon cancer. If peer-reviewed results confirm additive efficacy without significant toxicity, major pharmaceutical companies could view LB-100 as a valuable pipeline addition, leading to a licensing deal or outright acquisition—especially given the company’s clean asset structure and NIH-licensed IP.
The parent company’s focus on asset disposition may actually accelerate this process, as Nomad Power Solutions has little strategic rationale to support long-term clinical development. A competitive bidding process or partnership could emerge if more than one potential partner sees value. Confirmation of this scenario would include the announcement of a licensing agreement, a sale of the life-sciences portfolio, or the initiation of pivotal late-stage trials funded by a partner.
This scenario would be falsified if clinical data fail to demonstrate meaningful benefit, if trial holds recur, or if asset sale/partnership discussions stall without external interest.
Clinical Progress Continues Under Resource Constraints, but Value Realization Remains Deferred
The most plausible outcome is that LIXTE continues to advance LB-100 through its current clinical milestones in collaboration with external research centers, but progress is gated by capital availability and the parent company’s willingness to support interim funding. The company may seek bridge financing or non-dilutive grants to sustain operations while continuing to pursue strategic alternatives.
No near-term revenue is likely, and the value of the pipeline remains latent until a clinical inflection point or transaction occurs. Asset disposition may be delayed if market conditions are unfavorable, or if potential partners are waiting for additional safety and efficacy readouts.
Confirmation would come from continued patient enrollment, additional funding announcements, or extensions of collaborative agreements. Falsification would be signaled by trial terminations, further adverse events, or explicit discontinuation of the life-sciences portfolio by Nomad.
Funding Shortfall or Negative Clinical Events Could Force Liquidation or Asset Write-Off
The principal risk for LIXTE is that ongoing losses and a reported cash balance force the company to halt clinical operations before LB-100’s value is tested in the clinic. A failure to secure bridge financing, coupled with further adverse events or regulatory holds, could lead to the abandonment of the pipeline or a distressed asset sale at minimal value.
Given Nomad’s lack of strategic interest in life sciences, a negative outcome could result in a write-off, with remaining intellectual property and clinical data sold opportunistically or simply shelved. This scenario would be confirmed by announcements of trial discontinuations, layoffs, or asset impairment charges, and would be falsified by any material new funding or a strategic partnership that extends runway.
Milestones and Events That Will Define LIXTE’s Legacy Asset Value
Clinical trial enrollment rates and completion status for ongoing LB-100 studies in ovarian clear cell carcinoma, metastatic colon cancer, and soft tissue sarcoma. [S2]
Any public disclosure of interim or final clinical data—especially efficacy and safety outcomes that could attract partnership or acquisition interest. [S2]
Announcements regarding the sale, licensing, or discontinuation of the life-sciences portfolio by Nomad Power Solutions. [S2]
Updates on bridge financing, grants, or other capital-raising activities that would extend operating runway. [S2]
Resolution, recurrence, or escalation of serious adverse events or regulatory holds in clinical trials. [S2]
Changes in collaborative agreements with major cancer centers or pharmaceutical partners. [S2]
If disclosed, potential changes to the patent status or exclusivity for LB-100 or related assets.
Progress or decisions regarding the Liora Technologies proton therapy business and its integration or divestiture.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments