
LSEB Creative: Luxury Swimwear Ambitions Confront Early-Stage Financial Strains
LSEB Creative Corp. targets the expanding luxury swimwear market with high-end, gender-coordinated collections and advanced materials, but faces acute execution and funding hurdles as it seeks to establish brand credibility and scale operations.
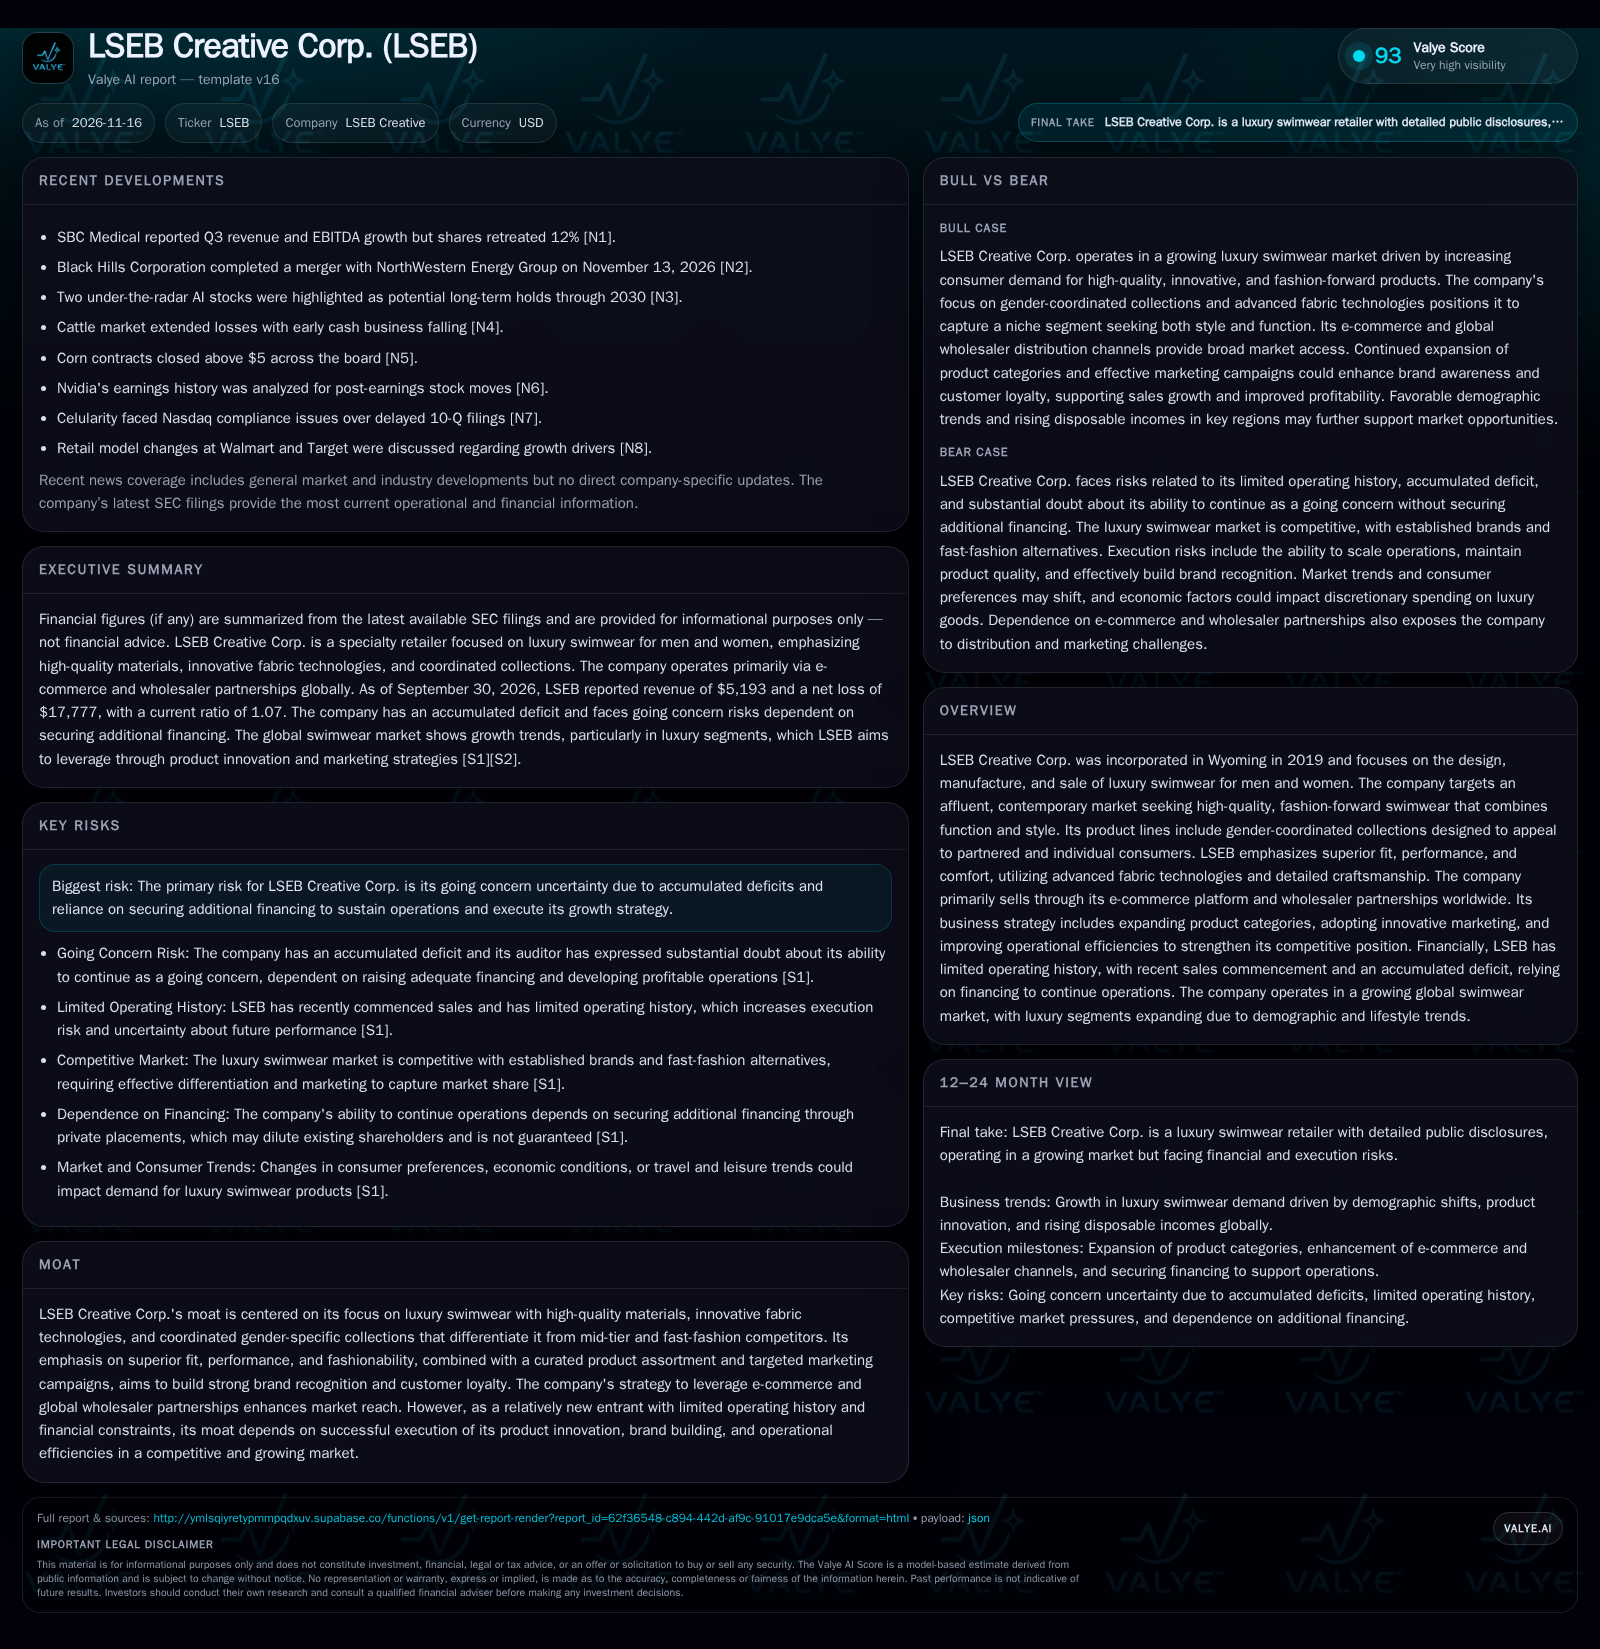
LSEB Creative Corp. is a young, U.S.-based luxury swimwear retailer emphasizing high-quality, fashion-forward products and operating mainly online and through wholesalers. As of September 30, 2026, the company remains in early commercialization with modest revenues ($5,193 for Q2 FY2027), a net loss, and a going concern warning from its auditor. LSEB’s long-term thesis depends on building brand loyalty and expanding its product line within a growing global luxury swimwear segment, but near-term viability hinges on securing new financing and proving its model can scale profitably in a competitive landscape [S1] [S2].
LSEB Creative Corp. has staked its future on capturing a share of the growing luxury swimwear market through high-quality, gender-coordinated product lines featuring advanced fabrics and fashion-forward design. While the global market for premium swimwear is buoyed by rising incomes and shifting lifestyle trends, LSEB’s journey is at a formative stage: revenue remains minimal, losses are ongoing, and the company’s auditor has raised doubts about its ability to continue as a going concern without further financing.
Early-Stage Operating Realities: Revenue, Losses, and Going Concern Uncertainty
As of September 30, 2026, LSEB Creative reported quarterly revenue of $5,193 and a net loss of $17,777, with an accumulated deficit of $774,530 recorded at the end of March 2026 [S1] [S2]. The company’s auditor has explicitly expressed substantial doubt about its ability to continue as a going concern, citing dependence on external financing and the need to develop profitable operations [S1]. LSEB’s current assets ($176,239) only slightly exceed current liabilities ($164,494), resulting in a current ratio of 1.07 and a cash ratio of zero as of the latest quarter [S2]. These facts underscore that LSEB remains in the nascent phase of commercialization, with a runway that is contingent on fresh capital. The financial profile places immediate pressure on management to secure funding and achieve operational traction before liquidity runs out.
How the Model Could Scale: Product Mix, Pricing, and Margin Potential
LSEB’s business model is predicated on selling premium-priced swimwear collections with differentiated design, advanced fabric technology, and an aspirational brand image. In luxury apparel, gross margins can be structurally higher than in mass-market retail due to premium pricing and lower price sensitivity among affluent consumers. However, fixed costs (design, marketing, e-commerce infrastructure) and variable costs (materials, fulfillment, customer acquisition) are likely to remain high in the early stages, especially as the company invests in brand building and category expansion.
The reliance on e-commerce theoretically improves margin potential by bypassing traditional retail markups, but also necessitates significant digital marketing spend to generate traffic and customer loyalty. Wholesaler partnerships may offer volume and brand exposure but typically at lower unit margins. LSEB’s expansion into adjacent categories (e.g., beachwear, men’s daywear) could support larger baskets and repeat purchases if executed well. The key economic challenge is to achieve sufficient scale to absorb fixed costs and reduce per-unit marketing and fulfillment expenses, while maintaining the brand’s premium positioning.
Brand Differentiation Versus Entrenched Rivals and Fast Fashion
The global luxury swimwear segment is dominated by established brands with strong heritage, significant marketing budgets, and robust wholesale/retail distribution. LSEB’s focus on gender-coordinated, technologically advanced swimwear provides a potential point of differentiation, appealing to affluent consumers seeking both performance and style. However, barriers to entry in luxury apparel are high: brand credibility, perceived exclusivity, and consistent product quality are prerequisites for pricing power and repeat business.
Fast-fashion entrants and digitally native vertical brands increase competitive intensity by rapidly iterating styles and undercutting on price. LSEB’s challenge is to avoid commoditization and discount-driven competition by cultivating a distinctive brand identity and loyal customer base. The company’s ability to deliver on its promise of superior fit and innovative materials will be critical in sustaining a premium positioning. Distribution via e-commerce offers global reach, but also exposes LSEB to intense digital marketing competition and the risk of high customer acquisition costs.
A Path to Premium Brand Status: What Would Signal Breakout Momentum
The favorable scenario for LSEB hinges on its ability to gain traction with affluent consumers and carve out a defensible niche in luxury swimwear. If the company can successfully translate its product innovation and design differentiation into strong brand recognition—evidenced by accelerating direct-to-consumer sales, positive customer reviews, and repeat purchase behavior—unit economics could improve markedly. Expansion into related categories may boost average order values and support cross-selling.
Early partnerships with influential retailers or curated wholesale platforms, along with effective digital marketing campaigns, could amplify brand visibility and drive incremental volume. Demonstrated pricing integrity (i.e., limited discounting) and strong gross margins would further validate the premium thesis. Evidence of fundraising at attractive terms or strategic investment from an industry player would signal external confidence and extend the operating runway. Key confirming data would include sustained revenue growth, improving gross margins, and rising customer lifetime value.
From Survival to Proof of Concept: Most Likely Trajectory Absent a Step Change
In the plausible middle case, LSEB secures interim financing, allowing it to continue operations and modestly grow sales through incremental e-commerce gains and selective wholesaler placements. Revenue growth may be lumpy as the company experiments with product launches, marketing strategies, and distribution partnerships. Operating losses likely persist until a critical mass of brand awareness and customer base is achieved, with fixed costs remaining high relative to scale.
Gross margins may fluctuate depending on channel mix and promotional activity, while cash burn is managed tightly but remains a constant constraint. The base scenario would be confirmed by the company’s ability to maintain operations through additional funding rounds, slow but steady revenue growth, and early indications of customer traction—such as improved conversion rates, increasing repeat purchases (if disclosed), and gradual expansion into new categories.
Liquidity Crunch and Brand Stagnation: How the Thesis Could Unravel
The adverse scenario materializes if LSEB fails to secure sufficient financing, leading to a cash crunch that forces operational cutbacks or a wind-down. In this case, limited marketing spend and inability to invest in inventory or product development would curtail sales growth, while fixed costs continue to weigh on the bottom line. Without meaningful brand traction or a compelling value proposition, the company risks being squeezed out by better-capitalized luxury incumbents and agile digital competitors.
Indicators of this scenario would include unsuccessful or highly dilutive fundraising efforts, declining or stagnant revenue, high product return rates, negative customer feedback, and a shift toward deep discounting to move inventory. Should LSEB’s brand fail to resonate or operational execution falter, the company may be forced into restructuring, asset sales, or ceasing operations altogether.
Milestones That Will Shape LSEB’s Viability in Premium Swimwear
Securing additional financing or closing a private placement to ensure operational continuity and fund growth initiatives.
Sustained quarter-over-quarter revenue growth, indicating early market traction and successful customer acquisition.
Gross margin trends by channel (e-commerce vs. wholesale), if disclosed, to assess pricing integrity and unit economics.
Growth in repeat purchase rate or customer lifetime value, if disclosed, as evidence of brand loyalty and product-market fit.
Expansion of product categories (e.g., beachwear, men’s daywear) and their contribution to overall sales mix.
Progress in establishing partnerships with premium retailers or curated wholesale platforms.
Signs of effective marketing ROI, as measured by digital traffic, conversion rates, and customer acquisition cost (if disclosed).
Management commentary or disclosure regarding runway extension, cost controls, and ability to scale operations efficiently.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments