
Life Time Group: Premium Fitness Expansion, Recurring Revenue Power, and the Realities of Asset-Light Growth
Life Time Group Holdings leverages a premium brand, affluent membership, and recurring revenue model to scale its resort-style fitness centers and digital ecosystem.
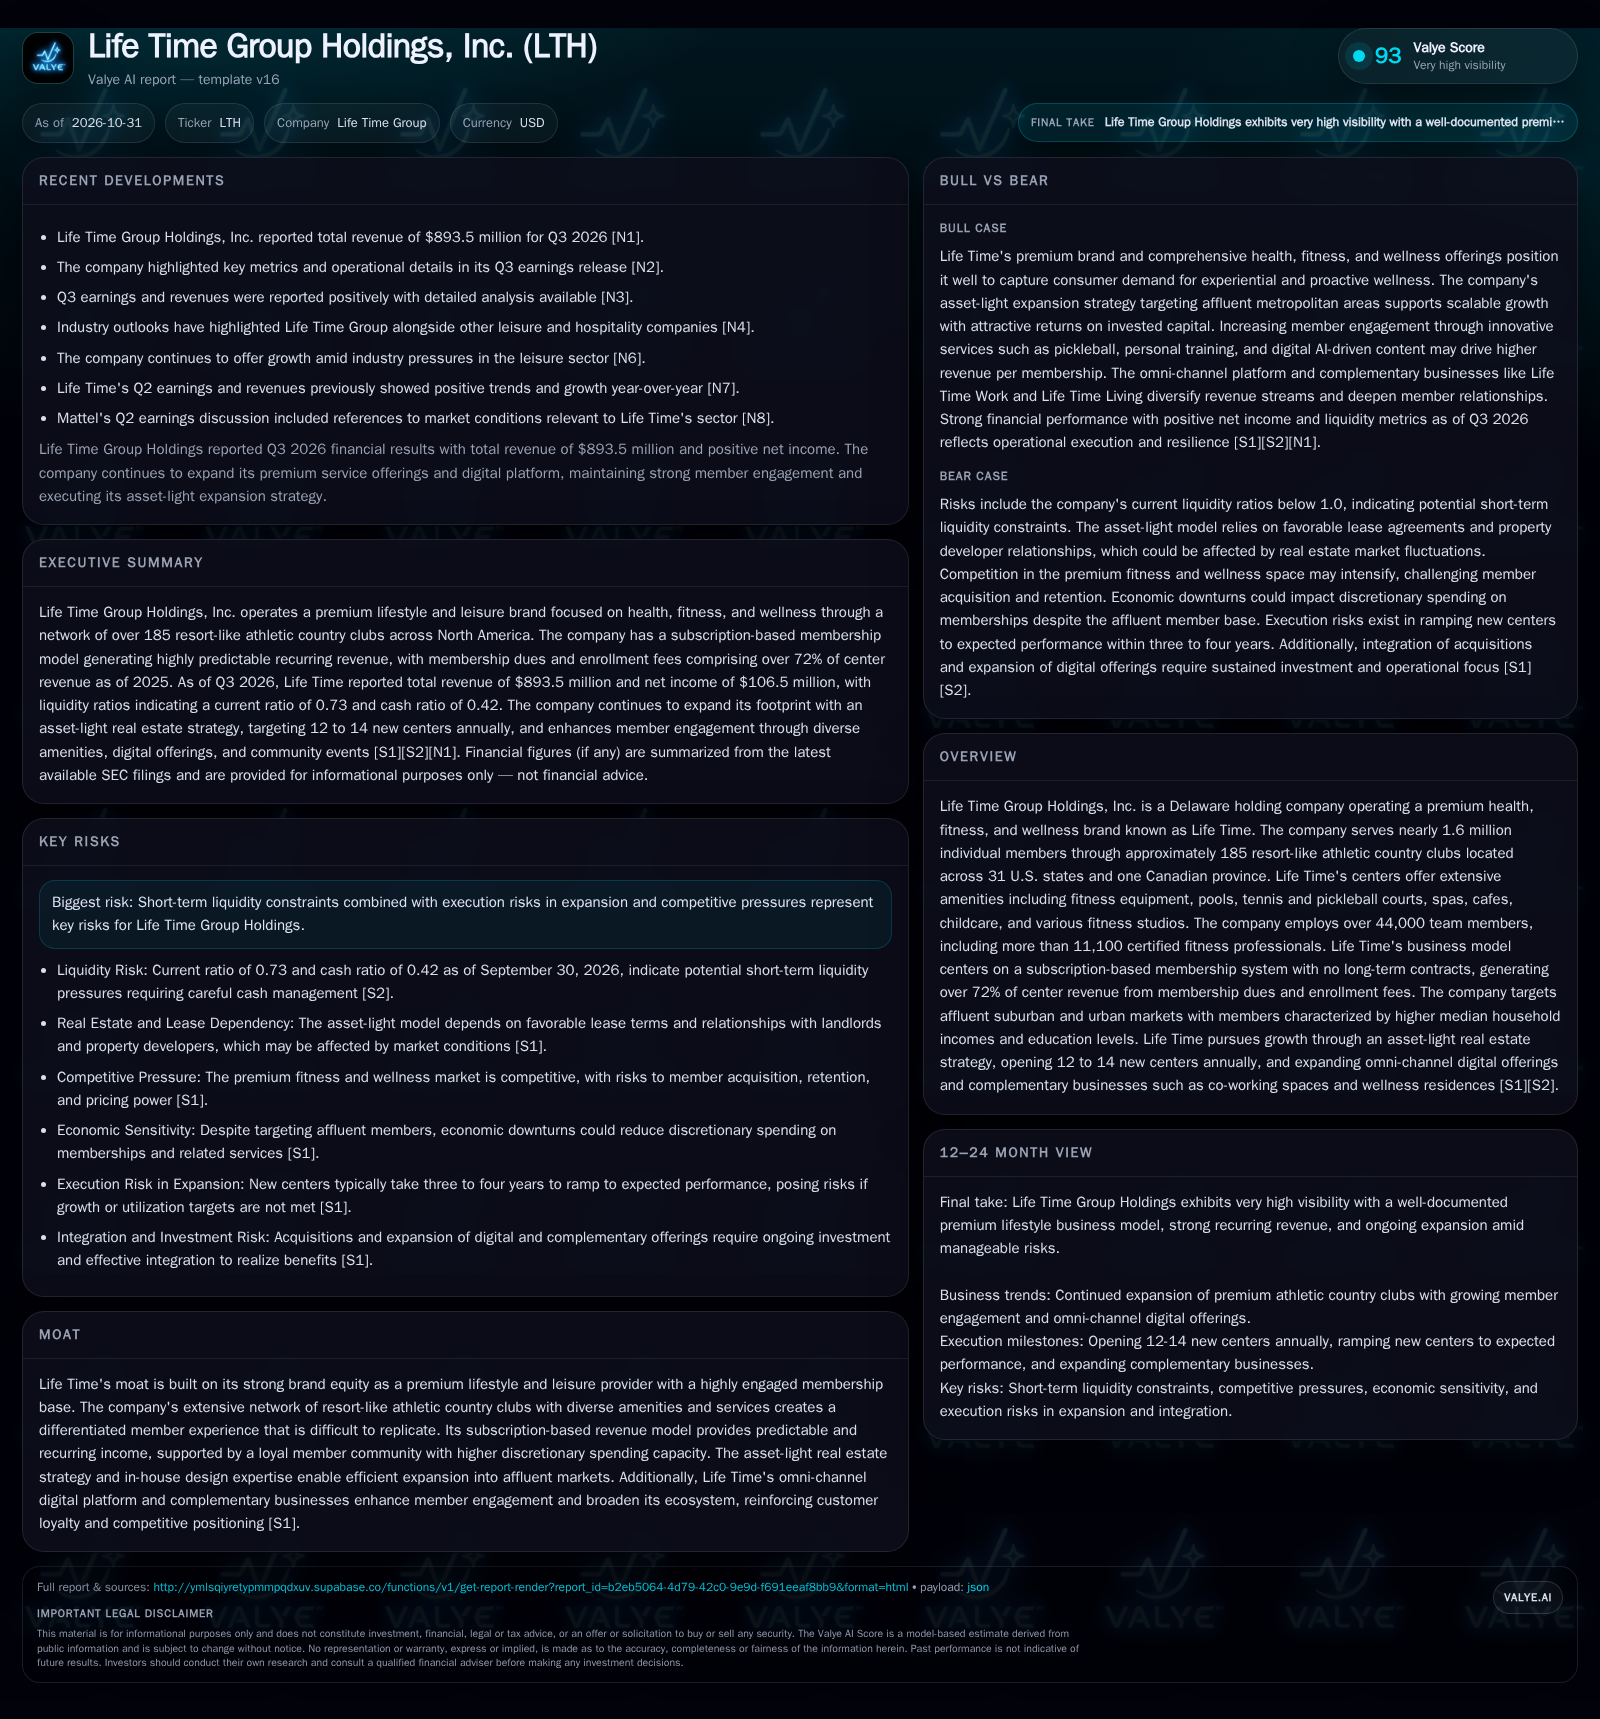
Life Time Group Holdings, Inc. (LTH) continues to expand its network of premium resort-style fitness centers, serving nearly 1.6 million individual members across 185+ locations. With over 72% of center revenue from recurring membership dues, the company enjoys high revenue predictability. However, a current ratio of 0.73 and ongoing capital needs for new center openings highlight the importance of disciplined execution and cash management as it targets affluent markets and enhances its omni-channel wellness platform. [S1] [S2] [N1]
Life Time Group Holdings, Inc. is scaling a differentiated model in the fitness and wellness sector, blending resort-like athletic centers, recurring subscription revenue, and omni-channel digital offerings. As Life Time targets 12–14 new center openings annually and bolsters digital engagement, the company must balance ambitious expansion with prudent financial discipline to sustain its premium positioning and defend against intensifying competition.
Recent Expansion and Financial Profile: A Snapshot of Scale and Execution
Life Time Group Holdings reported $893.5 million in Q3 2026 revenue, reflecting ongoing growth in its premium fitness and wellness business. The company serves nearly 1.6 million individual members through over 185 athletic country club centers across North America, with membership dues and enrollment fees accounting for more than 72% of center revenue. Life Time’s asset-light model—where 71% of centers are leased—supports its ambitious plan for 12–14 new center openings annually, primarily in affluent metropolitan areas. The company reported cash and liquidity metrics for the period; these figures do not by themselves establish operating runway, investment capacity, financial flexibility, or financing capacity. [S1] [S2] [N1]
Subscription Revenue, Member Economics, and Capital Intensity in a Premium Model
Life Time’s economics are anchored in a recurring revenue stream: over 72% of center revenues come from monthly membership dues and enrollment fees, providing high visibility and predictability. The company’s average revenue per membership reached $3,531 in 2025, supported by affluent members (median household income $160,000) and extensive amenities that justify premium pricing. Additional revenue is generated from personal training, spa services, childcare, and events, but these are largely variable and supplement the core subscription base.
The asset-light real estate model—leasing 71% of centers, including 84% of new openings since 2015—reduces upfront capital requirements relative to owning real estate, potentially enabling faster geographic expansion and higher returns on invested capital. However, the ramp-up period for new centers (typically three to four years) means that operating leverage is only realized as occupancy and utilization rates climb. Lease obligations add fixed costs that must be covered during this ramp phase, increasing the risk profile if membership growth lags expectations.
Ongoing investment in digital platforms, new amenities (pickleball, ARORA, MIORA), and complementary businesses (co-working, wellness residences) requires both operating and capital outlays. [S1] [S2]
Defending the High-End Fitness Niche: Brand, Experience, and Competitive Pressures
Life Time’s competitive position is built on differentiated, resort-like centers offering a breadth of amenities that most traditional gyms and boutique studios cannot match. The company targets affluent, health-conscious consumers who value not just fitness but a holistic lifestyle experience—including social events, wellness services, and digital engagement. Its brand equity and community orientation increase switching costs, as members often integrate Life Time into their routines and social lives.
However, the premium fitness and wellness segment is crowded and evolving. Life Time faces competition from luxury gym chains, boutique studios specializing in modalities like yoga or cycling, and emerging digital wellness platforms. Real estate costs, labor market pressures, and the need to continuously enhance amenities and digital offerings are persistent counterforces. Furthermore, as the company expands, it must avoid cannibalization and maintain its premium perception—especially as suburban and urban markets saturate.
Digital and hybrid competitors can undercut on price and convenience, but Life Time’s moat rests on physical experience, breadth of services, and community engagement. The question is whether these advantages are sustainable as consumer preferences and technology evolve.
When Premium Experience and Digital Engagement Drive Sustained Outperformance
In a favorable scenario, Life Time successfully leverages its brand, affluent customer base, and omni-channel platform to increase both membership and average revenue per member. New centers ramp to expected utilization within three to four years, benefiting from high pre-opening interest and efficient member acquisition. Expanded offerings—such as AI-driven digital content, new wellness programs, and social events—drive engagement and upsell opportunities, increasing ancillary revenue streams.
Complementary businesses (Life Time Work, Life Time Living) achieve critical mass, deepening member relationships and generating cross-selling opportunities. The asset-light model delivers attractive unit economics, with new locations delivering strong cash flow as fixed costs are leveraged over a growing member base. Liquidity is managed effectively, supported by positive cash flow from mature centers and possibly strategic refinancing.
Confirmation of this scenario would include sustained revenue growth above industry averages, rising average revenue per member, rapid ramp-up of new centers, and material profit contribution from digital and complementary businesses. Evidence of robust member retention, successful launches in new geographies, and positive free cash flow would further validate the thesis.
Balancing Expansion Ambitions with Operational Discipline
The most plausible outcome is that Life Time continues to expand its center footprint and digital engagement, but at a measured pace dictated by capital availability and market absorption. Membership growth and average revenue per member trend upward, but new center ramp-up periods occasionally exceed expectations, particularly in less-established markets or during periods of economic uncertainty.
The company maintains its premium positioning and core recurring revenue stream, but faces intermittent margin pressure from rising lease costs, labor expenses, and the need to continuously invest in amenities and digital infrastructure. Liquidity remains tight, requiring disciplined capital deployment and possibly periodic access to external financing to fund new center openings and digital initiatives.
This scenario would be confirmed by steady (but not accelerating) revenue growth, modest improvement in margins as mature centers offset ramp-up drag from new locations, and stable member retention rates. Evidence of prudent cash management, manageable leverage, and a consistent pipeline of successful new center launches would support this trajectory.
Liquidity Constraints and Execution Risks Undermine Expansion
If new center openings underperform—due to slower-than-expected member acquisition, competitive encroachment, or economic downturns—the fixed lease obligations from the asset-light model become a drag on profitability.
Member churn rises or average revenue per membership stagnates as competitive offerings proliferate and consumer discretionary spending weakens. The company is forced to slow its expansion pipeline, delay digital investments, or seek dilutive external capital. Negative operating leverage from underutilized centers and inflexible lease commitments could erode margins and threaten covenant compliance.
What Will Distinguish Durable Premium Fitness Growth from Overreach?
Pace and success of new center openings—tracking actual versus targeted 12–14 per year, and monitoring ramp-up periods and utilization rates.
Trends in average revenue per membership, as an indicator of pricing power, upsell success, and member engagement.
Liquidity management, particularly the evolution of current and cash ratios, and any changes in access to external capital or refinancing activity.
Retention and churn rates, if disclosed, to gauge member loyalty and the stickiness of the subscription base.
Operating margins and free cash flow generation from mature centers, to assess the sustainability of the expansion model.
Growth and profitability of complementary businesses (Life Time Work, Life Time Living), and their impact on overall member ecosystem value.
Competitive developments in premium fitness and digital wellness, including new entrant activity and price-based competition in core markets.
Adoption and monetization of digital and AI-driven offerings, with metrics such as app engagement, digital subscription revenue, or incremental spend per member, if disclosed.
Disclaimer: This is research-only, informational analysis and not investment advice. It may include AI-generated interpretation and general industry context. Always verify important details using primary sources.

Comments